Hungary
Hungary: personal and corporate taxation, local tax and residence
Hungary appeals to entrepreneurs and mobile employees because of its flat-rate income tax and its low nominal corporate tax rate within the European Union. These rates do not measure the total burden: social security contributions, the social contribution, the local business tax and the taxation of dividends come on top, and the new government is preparing changes for 2027.
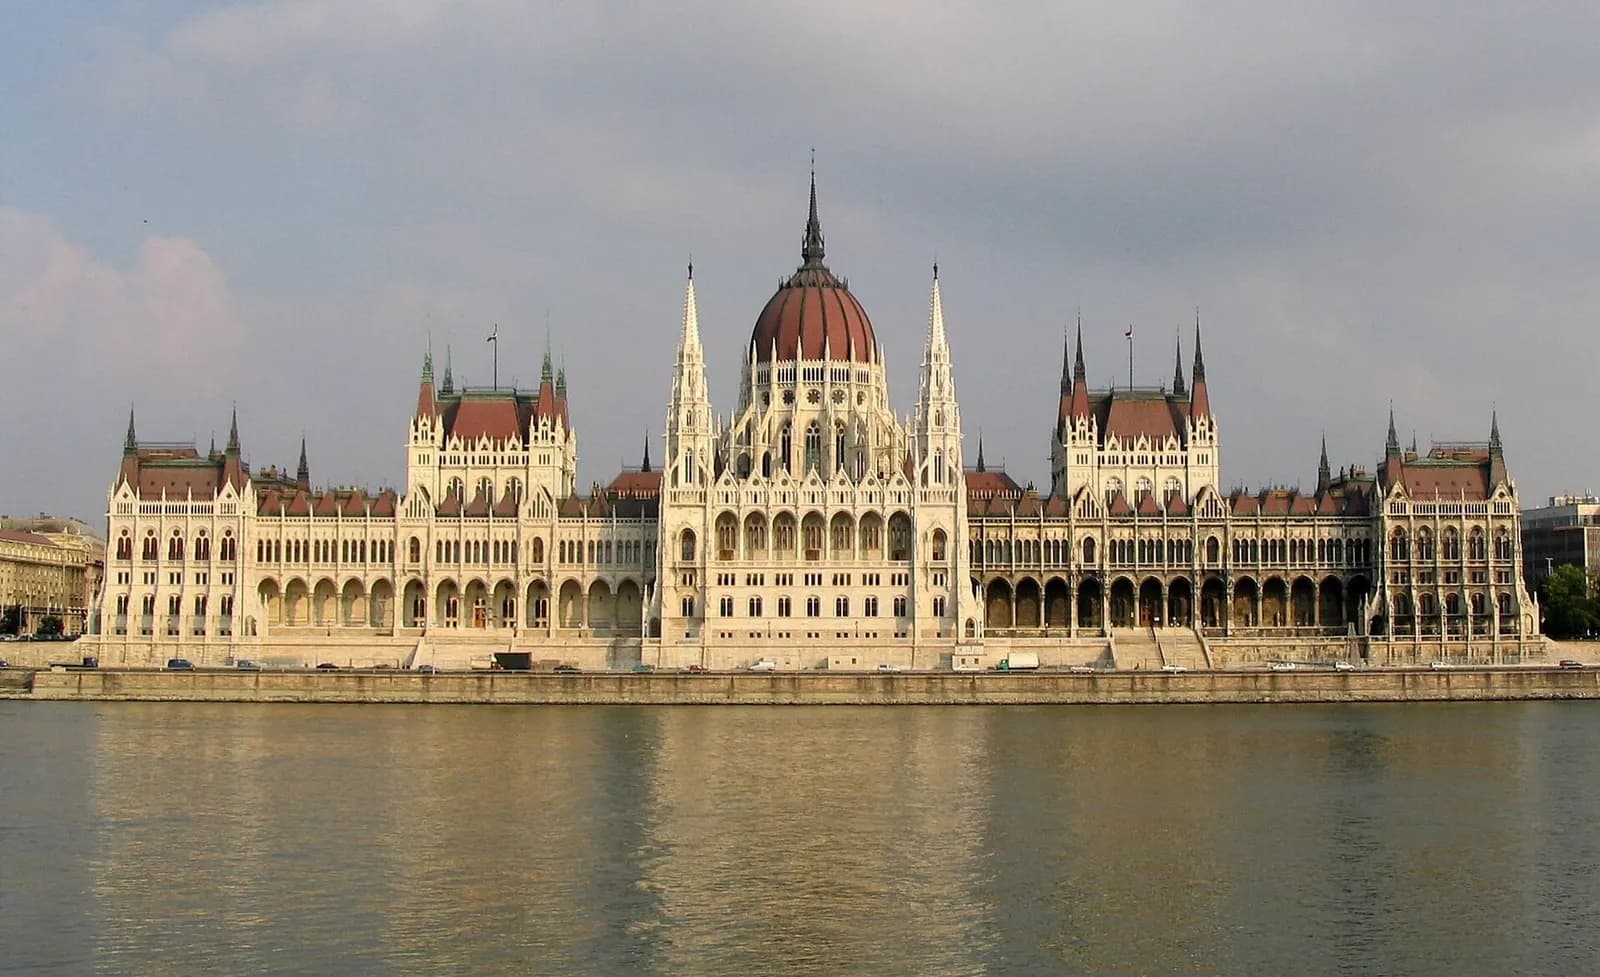
- Capital
- Budapest
- Currency
- HUF
- Region
- Europe
- Memberships
- European Union, European Economic Area, Schengen Area
Tax regimes at a glance
Each regime answers the same questions. A zero rate applies only to the income, person and period stated.
Your personal taxation
Personal income tax (személyi jövedelemadó, SZJA)General regime
- Who for?
- Hungarian tax residents within the meaning of Article 3 of the income tax act; non-residents only on their Hungarian-source income.
- Which income?
- All income: salaries, self-employment income, pensions, investment income and capital gains, under tax base rules specific to each category.
- Which source?
- Worldwide for residents (full tax liability); Hungarian for non-residents (limited liability), subject to tax treaties.
- Conditions
- Single rate on the tax base, unless the law provides otherwise. It does not include the employee's social security contribution or the social contribution. Family allowances and exemptions linked to age or maternity are not quantified here.
- Duration
- Permanent for as long as tax residence is in Hungary.
- Since when?
- Single rate applicable since 1 January 2016 (Act LXXXI of 2015) and confirmed for 2026 by the Budapest Government Office; the government that emerged from the April 2026 elections has announced a reduction for the lowest incomes, at the earliest from 1 January 2027, with no text adopted as of 1 November 2026.
- 15% Hungary: personal income tax rate (SZJA)
- from 183 days Hungary: EEA national must be present during the calendar year to be a tax resident
Social security contribution (TB-járulék) and social contribution (SZOCHO) on earned incomeGeneral regime
- Who for?
- Employees, sole proprietors and active partners insured under the Hungarian scheme; employers for the social contribution.
- Which income?
- Remuneration and earned income subject to contributions.
- Which source?
- Activity carried out in Hungary, subject to the European coordination regulations and social security agreements.
- Conditions
- Contribution borne by the insured person and levied in addition to income tax; social contribution borne by the employer and calculated on the remuneration paid. Minimum bases linked to the minimum wage exist for some self-employed persons; they are not detailed here.
- Duration
- Permanent during affiliation.
- Since when?
- Rates read in the versions of the consolidated acts as of 1 October 2026; 2026 minimum wage according to the Budapest Government Office.
- 18.5% Hungary: rate of the social security contribution payable by the insured person (TB-járulék)
- 13% Hungary: rate of the social contribution tax (SZOCHO), notably borne by the employer
- HUF 322,800 Hungary: gross monthly minimum wage in 2026
Taxation of dividends, interest and securities gains of individualsGeneral regime
- Who for?
- Individuals taxable in Hungary on this income.
- Which income?
- Dividends, capital gains on the sale of securities, interest.
- Which source?
- Hungarian-source or foreign-source income for residents; credit for foreign tax within the limits of the applicable treaty.
- Conditions
- Income tax at the single rate, to which is added the social contribution due by the recipient. For dividends and capital gains, the social contribution ceases to be due above an annual ceiling expressed as a multiple of the minimum wage, which takes account of other income subject to it; this ceiling does not apply to interest.
- Duration
- Annual taxation, for the year in which the income is received.
- Since when?
- Social contribution ceiling provided for by Act LII of 2018, consolidated version as of 1 October 2026; 2026 amount according to the Budapest Government Office. Tax rates on dividends and capital gains taken from the press: the corresponding articles of the act could not be read.
- 15% Hungary: personal income tax payable by an individual on dividends
- 13% Hungary: social contribution tax (SZOCHO) payable by an individual on capital income
- 24 Hungary: cap on the social contribution on certain capital income, as a multiple of the monthly minimum wage
- HUF 7,747,200 Hungary: cap on the social contribution on capital income in 2026
- 15% Hungary: income tax due on capital gains from the sale of securities (árfolyamnyereség)
Long-term investment account (tartós befektetési számla, TBSZ)Conditional
- Who for?
- Individuals who open this account with an investment services provider.
- Which income?
- Gains realised on the investments held in the account.
- Which source?
- Not verified for foreign securities.
- Conditions
- Exemption from income tax and social contribution at the end of the lock-in period if no withdrawal is made; reduced rates in the event of an interim withdrawal. Press information: the act was not read on this point.
- Duration
- Lock-in period counted in calendar years after the year of collection.
- Since when?
- Not verified.
- from 5 years Hungary: holding period after which gains on a long-term investment account (TBSZ) are exempt
Sale of real estate by an individualGeneral regime
- Who for?
- Individuals selling real estate or a property right.
- Which income?
- Income derived from the sale, after deduction of allowable costs.
- Which source?
- Property located in Hungary; not verified for property located abroad.
- Conditions
- Income tax at the single rate on taxable income; no tax is due beyond a minimum holding period. The progressive reduction of taxable income according to the holding period has not been verified.
- Duration
- Depending on the holding period.
- Since when?
- Undated NAV information page.
- 15% Hungary: income tax rate on income from the sale of real estate
- from 5 years Hungary: holding period beyond which the sale of real estate is not taxable
Flat-rate tax for small taxpayers (kisadózó vállalkozók tételes adója, KATA)Special regime
- Who for?
- Sole proprietors carrying on this activity as their main occupation, who opt in with the tax authority; the act excludes in particular certain employees and holders of an old-age pension.
- Which income?
- Receipts of the sole proprietorship.
- Which source?
- Not verified.
- Conditions
- Monthly flat-rate tax that replaces income tax and contributions on these receipts, depending on the regime; above an annual receipts ceiling, a special tax applies to the excess. The pre-2022 regime, open to business clients, no longer exists.
- Duration
- As long as the option is maintained and the conditions are met.
- Since when?
- Act XIII of 2022, consolidated version dated 1 August 2023. An extension is announced for 2027, with no text adopted as of 1 November 2026.
- HUF 50,000 Hungary: monthly flat-rate KATA tax
- HUF 18,000,000 Hungary: annual KATA revenue ceiling before the special tax applies
- 40% Hungary: KATA special tax on revenue exceeding the ceiling
Franco-Hungarian tax treatyGeneral regime
- Who for?
- Residents of France or Hungary receiving income from the other State, and persons resident in both States under their domestic law.
- Which income?
- Dividends, real estate income and capital gains, earned income, pensions, according to the articles of the treaty.
- Which source?
- Hungarian-source income received by a resident of France, and vice versa.
- Conditions
- Cap on Hungarian tax on dividends paid to a resident of France, reduced for a company holding a qualifying shareholding. On the French side, dividends, non-commercial income and Hungarian-source income of directors and artistes are taxable at their gross amount with a tax credit equal to the Hungarian tax, capped at the corresponding French tax; other income taxable in Hungary under the treaty is exempt in France. Real estate capital gains are taxable in the State where the property is located.
- Duration
- Permanent.
- Since when?
- Treaty signed in Paris on 28 April 1980, amended by the Multilateral Convention (applicable since 2019 for France and 2021 for Hungary according to the consolidated version).
- up to 5% France–Hungary Convention: Cap on Source-State Tax on Dividends (Qualifying Shareholding)
- from 25% France–Hungary Convention: minimum shareholding qualifying for the reduced cap on dividends
- up to 15% France–Hungary Convention: cap on source-State tax on dividends (other cases)
Residence registration for EU and EEA nationalsGeneral regime
- Who for?
- Citizens of the Union (other than Hungarians) and of EEA States.
- Which income?
- Not applicable.
- Which source?
- Not applicable.
- Conditions
- Beyond a short stay, application for a registration certificate from the OIF: employment, sufficient resources with comprehensive health insurance, or studies; proof of address.
- Duration
- Certificate valid without time limit as long as the identity document is valid.
- Since when?
- Application within a period counted from entry into Hungary.
- more than 90 days Hungary: length of stay beyond which an EEA national must register
- 180 days Hungary: reference period for calculating the length of stay of EEA nationals
- up to 93 days Hungary: deadline to apply for the registration certificate (EEA national)
- HUF 1,000 Hungary: fees for the registration certificate of an EEA national
Guest investor residence permit (Guest Investor Program)Conditional
- Who for?
- Third-country nationals.
- Which income?
- Not applicable: residence permit, with no tax effect of its own.
- Which source?
- Not applicable.
- Conditions
- Acquisition of units in a real estate investment fund registered with the National Bank of Hungary, or a donation to a higher education institution. Application made from Hungary. Right to work without restriction.
- Duration
- Maximum duration of the permit, renewable once.
- Since when?
- Act XC of 2023; OIF information sheet amended on 3 March 2026.
- from €250,000 Hungary: minimum investment in real estate fund units for the guest investor residence permit
- from €1,000,000 Hungary: minimum donation to a higher education institution for the guest investor residence permit
- up to 10 years Hungary: maximum duration of the guest investor residence permit
White Card (digital nomads)Conditional
- Who for?
- Third-country nationals working for a foreign employer or running their own foreign company.
- Which income?
- Not applicable: residence permit. The tax treatment of the holder's income is governed by the general residence rules.
- Which source?
- Foreign-source income required.
- Conditions
- Minimum net income received before entry and maintained during the stay; no gainful activity or shareholding in a company in Hungary; no family reunification.
- Duration
- Short-term permit, renewable only once.
- Since when?
- OIF information sheet amended on 11 March 2026.
- from €3,000 Hungary: minimum net monthly income required for the White Card (digital nomads)
- from 6 months Hungary: required period of receipt of the minimum income before entry for the White Card
- up to 1 year Hungary: maximum duration of the White Card
Announced income tax cut for low incomesNot documentedProposal
- Who for?
- Taxpayers with the lowest incomes, according to government announcements.
- Which income?
- Income subject to income tax.
- Which source?
- Not determined.
- Conditions
- Announced project; no adopted text had been read as of 1 November 2026. The rate and thresholds are not published here. The draft 2027 budget presented in October 2026 also mentions the end of the exemption for mothers of two children beyond a certain age, a new wealth tax and an extension of KATA; the tax package submitted in summer 2026 does not affect the income tax rate.
- Duration
- Not determined.
- Since when?
- At the earliest on 1 January 2027, according to press reports from July 2026.
Your company
Corporate income tax (társasági adó, TAO)General regime
- Who for?
- Resident companies (registered office in Hungary or, for a foreign person, place of management in Hungary) and permanent establishments of foreign companies.
- Which income?
- Taxable profit, after tax adjustments to the accounting result.
- Which source?
- Worldwide for resident companies, subject to treaties; according to private sources, capital gains on reported shareholdings and dividends received are in principle not taxable.
- Conditions
- Single nominal rate. This rate is not the total burden: the local business tax, social charges and the taxation of the dividend in the hands of the shareholder come on top. Loss carry-forward limited in time and as a proportion of the result, according to a private source.
- Duration
- Permanent.
- Since when?
- Rate read from a private source dated 2026; no readable official source: the consolidated Act LXXXI of 1996 could only be read as far as its definitions.
- 9% Hungary: nominal corporate income tax (CIT) rate
- up to 5 years Hungary: carry-forward period for corporate tax losses
- up to 50% Hungary: annual limit on the use of carried-forward losses, as a share of profit
Local business tax (helyi iparűzési adó, HIPA)General regime
- Who for?
- Businesses carrying on an activity in a municipality that has introduced the tax.
- Which income?
- Net turnover reduced in particular by the purchase cost of goods sold, mediated services, subcontracting and materials: the tax base is not the same as profit.
- Which source?
- Activity carried out within the municipality's territory; apportionment between municipalities in the case of multiple establishments.
- Conditions
- Rate set by each municipality within a statutory annual ceiling (Act C of 1990, Article 40). Example read: the town of Nagykanizsa applies a rate equal to this ceiling.
- Duration
- Annual.
- Since when?
- Ceiling applicable since 2000 under Act C of 1990 on local taxes, consolidated version as of 1 October 2026.
- up to 2% Hungary: maximum rate of the local business tax (HIPA)
Small business tax (kisvállalati adó, KIVA)Special regime
- Who for?
- Businesses that opt into the regime and comply with ceilings on headcount, turnover and balance sheet total, with a financial year matching the calendar year.
- Which income?
- Substitute tax base: remuneration subject to contributions, approved dividends, capital reductions and adjustments to the result; it cannot be lower than the remuneration.
- Which source?
- Not verified.
- Conditions
- Replaces corporate income tax and the employer's social contribution. Exit from the regime if a turnover ceiling or a headcount ceiling higher than the entry ceiling is exceeded.
- Duration
- As long as the conditions are met; exit in the quarter in which the turnover ceiling is exceeded.
- Since when?
- Act CXLVII of 2012, consolidated version as of 14 May 2026, whose tax base was amended by Act XIV of 2026 from the 2026 financial year.
- 10% Hungary: small business tax rate (KIVA)
- up to 100 Hungary: maximum average headcount to opt for KIVA
- up to HUF 6,000,000,000 Hungary: maximum turnover and balance sheet total to opt for the KIVA
- up to HUF 12,000,000,000 Hungary: turnover threshold above which a company leaves KIVA
- up to 200 Hungary: average headcount above which a company leaves the KIVA regime
Global minimum tax for large groups (Pillar Two)Conditional
- Who for?
- Constituent entities of multinational groups and of large domestic groups whose consolidated turnover exceeds the statutory threshold in at least two of the four preceding financial years. Companies outside these groups are not concerned.
- Which income?
- Profits subject to an effective rate below the minimum rate, calculated by jurisdiction.
- Which source?
- Hungarian for the qualified domestic top-up tax; foreign for the income inclusion rule top-up tax.
- Conditions
- Qualified domestic top-up tax and income inclusion rule top-up tax, under Act LXXXIV of 2023.
- Duration
- Permanent.
- Since when?
- Applicable from the 2024 financial year according to private sources; version of the act consulted: status as of 20 November 2025.
- from €750,000,000 Hungary: consolidated revenue threshold for groups subject to the global minimum tax
- 15% Hungary: minimum effective tax rate for large groups (Pillar Two)
Compare with other countries:Foreign incomeCompany taxationRegimes for new residents
In brief
Hungary is a member of the European Union and the Schengen area but has not adopted the euro: its currency is the forint. Its personal income tax is a flat tax of 15%1 and its corporate income tax has a nominal rate of 9%2, one of the lowest in the Union.
These two rates do not measure any total burden. On a salary, the employee's social security contribution (18.5%3) is added to the tax, and the employer pays the social contribution tax (13%4). In a company, the local business tax (up to up to 2%5 of a base close to turnover) is added to corporate income tax, and the dividend distributed to the shareholder in turn bears income tax and, up to a ceiling, the social contribution tax.
The political context matters: the Tisza party won the parliamentary elections of April 2026 and the new government has announced an income tax cut for low earners and a wealth tax, as part of the 2027 budget. As of the date we consulted the sources, these measures are proposals; this page describes the law in force in 2026.
Your personal taxation
Tax residence and scope of taxation
The Personal Income Tax Act (Act CXVII of 1995, Article 3, point 2) defines the tax resident by category. A Hungarian citizen is resident, unless he or she holds another nationality and has no registered address in Hungary. A national of an EEA state, and therefore a French citizen, is resident if he or she exercises the right of residence in Hungary for at least from 183 days6 during the calendar year, counting the days of entry and exit. For other persons, three criteria apply in order: a permanent home located only in Hungary, then the centre of vital interests (the closest personal, family and economic ties), then habitual abode (Nemzeti Jogszabálytár, SZJA Act).
A resident is taxable on all income, wherever it arises; a non-resident is taxable only on income of Hungarian source or on income that Hungary may tax under a treaty (Article 2, paragraph 4). No temporary exemption regime for the foreign income of new arrivals was identified in the texts read.
The general regime: flat tax and contributions
Personal income tax (személyi jövedelemadó, SZJA) is levied at the flat rate of 15%1 on the tax base, unless the law provides otherwise. This rate results from Act LXXXI of 2015, applicable since 2016 (Magyar Közlöny, 2015, No. 90); it is restated for 2026 in the information sheet of the Budapest government office (Budapest Főváros Kormányhivatala, Mennyi is 2026-ban ?), which states that it is indicative only.
In addition, for employees and insured self-employed persons, there is the social security contribution (társadalombiztosítási járulék) of 18.5%3 (Act CXXII of 2019, Article 25). The employer also pays the social contribution tax (szociális hozzájárulási adó, SZOCHO) of 13%4 on remuneration paid (Act LII of 2018, Article 2). These three levies are distinct: adding the tax and the employee's contribution gives a deduction from gross pay well above the tax rate alone.
The gross monthly minimum wage, a reference point for several bases and ceilings, is HUF 322,8007 as of the first day of 2026 (Budapest government office, January 2026); it is set by Government Decree 426/2025 (XII. 23.), which we have not read.
Family allowances, age- or maternity-related exemptions, the minimum contribution base for the self-employed and the flat-rate regime for sole traders (átalányadózás): not verified in this page.
Investment income
Dividends received by an individual bear income tax of 15%8 (Financera, October 2026), and capital gains on the sale of securities bear the same rate of 15%9 (Biztosdöntés, March 2026). The social contribution tax of 13%10 is added, borne by the recipient (Act LII of 2018, Article 1, paragraph 5).
For dividends and capital gains, this contribution is capped: it ceases to be due when all the income taken into account reaches 2411 times the monthly minimum wage (Article 2, paragraph 2), that is HUF 7,747,20012 for 2026 according to the Budapest government office. Salaries count in this calculation: a shareholder who is already well paid can reach the ceiling before any distribution. The ceiling does not apply to interest.
The long-term investment account (TBSZ) allows an exemption from tax and social contribution tax on gains after from 5 years13, counted in calendar years after the year of collection, with no intermediate withdrawal; this point rests on a press source.
Real estate, pensions and foreign income
Taxable income from the sale of real estate is taxed at 15%14; no tax is due if the property has been held for at least from 5 years15 (NAV, real estate sale).
Hungarian income of a French resident: the treaty
The France–Hungary treaty of 28 April 1980, as modified by the Multilateral Convention, caps the tax that Hungary may levy on a dividend paid to a French resident: up to 15%16 of the gross amount as a general rule, and up to 5%17 where the recipient is a company directly holding at least from 25%18 of the capital of the distributing company (Article 10). In France, this dividend is taxable on its gross amount, and the Hungarian tax gives entitlement to a tax credit capped at the corresponding French tax (Article 24) (impots.gouv.fr, consolidated version of the treaty). Capital gains from the sale of real estate are taxable in the state where the property is located (Article 13).
The rate actually withheld under Hungarian law on dividends paid to a non-resident individual, the progressive reduction of taxable income according to the holding period of a property, the taxation of rents and the treatment of foreign pensions: not verified. Articles 8 and 62 to 67 of the Personal Income Tax Act (rates, real estate income, interest, dividends, capital gains) could not be read in their consolidated version.
Your business
A company is resident if it is incorporated in Hungary or, for a foreign entity, if its place of management is located there, that is, the place where management is established in order to run the business (Act LXXXI of 1996, Articles 2 and 4). The tax burden is built up in several layers:
- corporate income tax (társasági adó, TAO), at the nominal rate of 9%2 on taxable profit (PwC, 2026; a private source, as the law could not be read on this point);
- the local business tax (helyi iparűzési adó, HIPA), set by each municipality within the annual limit of up to 2%5 (Act C of 1990, Article 40), on a base built on net turnover less the cost of goods sold, intermediated services, subcontracting and materials (town of Nagykanizsa, January 2025, which applies the ceiling rate);
- social charges on remuneration: the employer's social contribution tax and the employee's contribution;
- on distribution, income tax and social contribution tax for the individual shareholder.
Losses may be carried forward for up to 5 years19 and set off up to up to 50%20 of the profit for the year, according to a private source (Moore Global). According to the same sources, capital gains on reported participations and dividends received from subsidiaries are in principle exempt, and domestic law does not provide for withholding tax on dividends, interest and royalties paid to foreign companies; these points remain to be confirmed against the law.
The KIVA regime for small businesses
The kisvállalati adó (KIVA) replaces, by option, corporate income tax and the employer's social contribution tax with a tax of 10%21 based on remuneration, approved dividends, capital reductions and adjustments to profit (Act CXLVII of 2012, Articles 20 and 21). The option requires an average headcount of no more than up to 10022 employees and turnover and a balance sheet total of no more than up to HUF 6,000,000,00023. The company leaves the regime if its turnover exceeds up to HUF 12,000,000,00024 or if its headcount exceeds up to 20025.
Whether KIVA is worthwhile depends on the structure of the business: the base includes the payroll, so a labour-intensive company with little profit may lose out. The comparison is made on the cumulative burden, never on rates alone.
KATA
The pre-2022 KATA was set out in Chapter II of Act CXLVII of 2012, repealed by Act XIII of 2022. The current regime, arising from the latter act, is reserved for sole traders operating as their main activity who opt in with the tax authority; it does not apply to companies. It consists of a flat tax of HUF 50,00026 per month. Above HUF 18,000,00027 of annual receipts, the excess portion bears a special tax of 40%28 (Act XIII of 2022, Articles 3 and 7).
This threshold makes KATA a regime for small activities: the special tax makes exceeding it costly. The Minister of Finance mentioned in May 2026 an expansion of the regime for 2027; no text had been adopted as of 1 November 2026.
Full list of exclusions, effects of the regime on social coverage and retirement, and the flat-rate regime for sole traders (átalányadózás): not verified.
Minimum tax for large groups
Act LXXXIV of 2023 implements Pillar Two. It targets multinational groups and large domestic groups whose consolidated turnover reaches from €750,000,00029 in at least two of the four preceding financial years, with a minimum rate of 15%30 assessed by jurisdiction (Act LXXXIV of 2023, Articles 1 and 3). An SME or a company held by an entrepreneur outside such a group is not concerned.
Controlled foreign company rules, sector-specific taxes (banks, retail, energy), the innovation contribution, and accounting and filing obligations: not verified against the primary source. The draft 2027 budget provides for a tightening of corporate income tax and the innovation contribution, not quantified here.
Residence routes
European Union citizens
A French national does not need a visa. If he or she stays for more than more than 90 days31 within a period of 180 days32, he or she applies for a registration certificate from the General Directorate of Foreigners (OIF), within up to 93 days33 of entry. The applicant shows proof of employment, sufficient resources with comprehensive health insurance, or studies, as well as an address. The fee is HUF 1,00034 and the certificate is valid with no time limit as long as the identity document is valid (OIF, Registration Certificate for EEA Nationals).
Third-country investors
The guest investor residence permit (Act XC of 2023) is open to third-country nationals who acquire at least from €250,00035 of units in a real estate investment fund registered with the National Bank of Hungary, or who make a donation of at least from €1,000,00036 to a higher education institution. The permit lasts for at most up to 10 years37, may be extended once, and allows unrestricted work (OIF, Residence permit for guest investor). Direct purchase of a home is not among the routes described by the OIF.
Remote workers from third countries
The White Card is intended for people who work for a foreign employer or company and can show a net income of at least from €3,00038 per month during the from 6 months39 preceding entry. It lasts for a maximum of up to 1 year40 and can be extended once; any gainful activity in Hungary and any shareholding in a Hungarian company are excluded, and family reunification is not available (OIF, White Card). A prolonged stay may nonetheless make the holder a tax resident under the criteria set out in the law.
Residence permits for salaried employment, self-employment, annuitants and retirees, and the permanent right of residence of Union citizens: not verified.
Tax residence, presence and transitions
For a French national, the presence criterion is central: a stay of at least from 183 days6 in the calendar year makes a person resident; below that threshold, the permanent home, the centre of vital interests and the habitual abode may still lead to residence. The law also addresses a change of residence during the year; its terms have not been read.
In the case of dual residence, the France–Hungary tax treaty applies the following tie-breaker rules in this order: permanent home, then centre of vital interests if the person has a home in both States, then habitual abode, then nationality, and failing that, agreement between the administrations (Article 4, paragraph 2; impots.gouv.fr). Departure from France is assessed under French criteria and the treaty: registration in Hungary is not, by itself, enough to establish that the home and the centre of economic interests have left France.
Treatment of the year of arrival and the year of departure, and treaty allocation rules for the salaries of teleworkers: not verified.
Cost of living and real estate
We publish no typical budget, no property prices and no transfer taxes: no official series has been consulted. The rules governing the acquisition of real estate by third-country nationals have not been verified.
Procedures and points to watch
VAT (ÁFA) has a standard rate of 27%41, the highest in the Union, and two reduced rates of 18%42 and 5%43 (European Commission, Your Europe, July 2026). The goods and services subject to the reduced rates are not detailed here.
- Think in terms of total burden: corporate income tax, local business tax, social charges and dividend taxation, not just the nominal rate.
- Check the municipality of establishment: the local business tax is set locally, within the statutory ceiling.
- Distinguish between income tax, the employee's contribution and the employer's contribution: the tax rate quoted in comparisons is only one part of them.
- Take into account the ceiling on the social contribution on dividends, which includes the year's salaries.
- Compare KIVA and the standard regime on the cumulative burden, payroll included.
- For a Hungarian dividend received in France, check the withholding applied in Hungary against the treaty ceiling, then the tax credit in France.
- Follow the 2027 budget: the announced income tax cut, a wealth tax, a tightening of corporate income tax; none of these texts had been adopted at the date of consultation (444.hu, 20 October 2026).
Steps and timelines for obtaining the Hungarian tax number and for setting up a company: not verified.
Frequently asked questions
Is the corporate income tax rate the total burden?
No. The 9%2 rate is a nominal rate on profit. To it are added the local business tax, assessed on a base close to turnover, social charges, and, on distribution, the shareholder's income tax and social contribution.
Does the income tax rate include contributions?
No. The employee also pays the social security contribution of 18.5%3, and the employer the social contribution of 13%4.
How long do you need to spend in Hungary to be a tax resident there?
For an EEA national, a presence of at least from 183 days6 in the calendar year is enough. Below that, residence may result from the permanent home or the centre of vital interests.
Does a French national need a residence permit?
No, but they must apply for a registration certificate if they stay for more than more than 90 days31 within a period of 180 days32.
Will income tax go down?
The government has announced a cut for the lowest incomes, at the earliest for 2027 (VG, July 2026). Until a text is adopted, the flat rate currently in force remains the reference.
Is a dividend of Hungarian source received by a resident of France taxed twice?
It may be taxed in both States, but the treaty caps Hungarian tax at up to 15%16 of the gross amount for an individual, and France grants a tax credit equal to the Hungarian tax, up to the amount of the corresponding French tax.
Is KATA open to a company?
No. Since Act XIII of 2022, it has been reserved for sole proprietors operating as their main activity. A small company can, however, consider KIVA.
Banks and accounts
Accept residents of this country
See this country on the tax map
Please note
Sources and verification dates
- 1.
Hungary: personal income tax rate (SZJA) : 15%
« Az Szja. törvény hatálya alá tartozó jövedelem után az adó mértéke - ha az Szja. törvény másként nem rendelkezik - az adóalap 15 százaléka. »
Budapest Főváros Kormányhivatala, Rehabilitációs Főosztály, « Mennyi is 2026-ban? (tájékoztató, készült 2026. január 5.) »Verified on Nov 2, 2026Verified source
- 2.
Hungary: nominal corporate income tax (CIT) rate : 9%
« The Hungarian corporate income tax ('CIT') rate is a flat rate of 9%. »
PwC Magyarország, « Investing in Hungary 2026 »Verified on Nov 2, 2026Verified source
- 3.
Hungary: rate of the social security contribution payable by the insured person (TB-járulék) : 18.5%
« A társadalombiztosítási járulék mértéke 18,5 százalék. »
Nemzeti Jogszabálytár, « 2019. évi CXXII. törvény a társadalombiztosítás ellátásaira jogosultakról, valamint ezen ellátások fedezetéről »Verified on Nov 2, 2026Verified source
- 4.
Hungary: rate of the social contribution tax (SZOCHO), notably borne by the employer : 13%
« Az adó mértéke az adóalap 13 százaléka »
Nemzeti Jogszabálytár, « 2018. évi LII. törvény a szociális hozzájárulási adóról »Verified on Nov 2, 2026Verified source
- 5.
Hungary: maximum rate of the local business tax (HIPA) : 2%
« 2000. évtől az adóalap 2%-a. »
Nemzeti Jogszabálytár, « 1990. évi C. törvény a helyi adókról (állapot: 2026.10.01.) »Verified on Nov 2, 2026Verified source
- 6.
Hungary: EEA national must be present during the calendar year to be a tax resident : 183 days
« legalább 183 napig Magyarország területén gyakorolja »
Nemzeti Jogszabálytár, « 1995. évi CXVII. törvény a személyi jövedelemadóról »Verified on Nov 2, 2026Verified source
- 7.
Hungary: gross monthly minimum wage in 2026 : HUF 322,800
« az év első napján érvényes minimálbérrel kell számolni, 24 x 322.800,- Ft, ami 7.747.200,-Ft/év. »
Budapest Főváros Kormányhivatala, Rehabilitációs Főosztály, « Mennyi is 2026-ban? (tájékoztató, készült 2026. január 5.) »Verified on Nov 2, 2026Verified source
- 8.
Hungary: personal income tax payable by an individual on dividends : 15%
« 15%-os személyi jövedelemadó »
Financera, « Osztalék adózása Magyarországon 2026 », financera.hu (press article)Verified on Nov 2, 2026Verified source
- 9.
Hungary: income tax due on capital gains from the sale of securities (árfolyamnyereség) : 15%
« A árfolyamnyereségre vonatkozó adókulcs mértéke 15 százalék, amely személyi jövedelemadó (kamatadó). »
Biztosdöntés, « Árfolyamnyereség adózása », biztosdontes.hu (press article)Verified on Nov 2, 2026Verified source
- 10.
Hungary: social contribution tax (SZOCHO) payable by an individual on capital income : 13%
« Az adó mértéke az adóalap 13 százaléka »
Nemzeti Jogszabálytár, « 2018. évi LII. törvény a szociális hozzájárulási adóról »Verified on Nov 2, 2026Verified source
- 11.
Hungary: cap on the social contribution on certain capital income, as a multiple of the monthly minimum wage : 24
« a minimálbér összegének huszonnégyszeresét »
Nemzeti Jogszabálytár, « 2018. évi LII. törvény a szociális hozzájárulási adóról »Verified on Nov 2, 2026Verified source
- 12.
Hungary: cap on the social contribution on capital income in 2026 : HUF 7,747,200
« az év első napján érvényes minimálbérrel kell számolni, 24 x 322.800,- Ft, ami 7.747.200,-Ft/év. »
Budapest Főváros Kormányhivatala, Rehabilitációs Főosztály, « Mennyi is 2026-ban? (tájékoztató, készült 2026. január 5.) »Verified on Nov 2, 2026Verified source
- 13.
Hungary: holding period after which gains on a long-term investment account (TBSZ) are exempt : 5 years
« ötödik naptári évet követően pedig mentesülsz a két adónem megfizetése alól »
Biztosdöntés, « Árfolyamnyereség adózása », biztosdontes.hu (press article)Verified on Nov 2, 2026Verified source
- 14.
Hungary: income tax rate on income from the sale of real estate : 15%
« Ha az ingatlan értékesítésből adóköteles jövedelme keletkezett, akkor annak 15 százalékát kell adóként megfizetnie. »
Nemzeti Adó- és Vámhivatal (NAV), « Ingatlan adásvétel — eladó »Verified on Nov 2, 2026Verified source
- 15.
Hungary: holding period beyond which the sale of real estate is not taxable : 5 years
« legalább 5 éve szerezte »
Nemzeti Adó- és Vámhivatal (NAV), « Ingatlan adásvétel — eladó »Verified on Nov 2, 2026Verified source
- 16.
France–Hungary Convention: cap on source-State tax on dividends (other cases) : 15%
« 15 p. cent du montant brut des dividendes, dans tous les autres cas. »
Direction générale des Finances publiques (impots.gouv.fr), « Version consolidée de la Convention entre la France et la Hongrie tendant à éviter les doubles impositions (Paris, 28 avril 1980), modifiée par la Convention multilatérale »Verified on Nov 2, 2026Verified source
- 17.
France–Hungary Convention: Cap on Source-State Tax on Dividends (Qualifying Shareholding) : 5%
« 5 p. cent du montant brut des dividendes si le bénéficiaire effectif est une société »
Direction générale des Finances publiques (impots.gouv.fr), « Version consolidée de la Convention entre la France et la Hongrie tendant à éviter les doubles impositions (Paris, 28 avril 1980), modifiée par la Convention multilatérale »Verified on Nov 2, 2026Verified source
- 18.
France–Hungary Convention: minimum shareholding qualifying for the reduced cap on dividends : 25%
« (autre qu'une société de personnes) qui détient directement au moins 25 p. cent du capital »
Direction générale des Finances publiques (impots.gouv.fr), « Version consolidée de la Convention entre la France et la Hongrie tendant à éviter les doubles impositions (Paris, 28 avril 1980), modifiée par la Convention multilatérale »Verified on Nov 2, 2026Verified source
- 19.
Hungary: carry-forward period for corporate tax losses : 5 years
« Company is entitled to utilize the tax losses for 5 years up to 50% of the pre-tax profit of the financial year. »
Moore Global, « Hungary — International corporate tax »Verified on Nov 2, 2026Verified source
- 20.
Hungary: annual limit on the use of carried-forward losses, as a share of profit : 50%
« Company is entitled to utilize the tax losses for 5 years up to 50% of the pre-tax profit of the financial year. »
Moore Global, « Hungary — International corporate tax »Verified on Nov 2, 2026Verified source
- 21.
Hungary: small business tax rate (KIVA) : 10%
« Az adó mértéke az adó alapjának 10 százaléka. »
Nemzeti Jogszabálytár, « 2012. évi CXLVII. törvény a kisadózó vállalkozások tételes adójáról és a kisvállalati adóról »Verified on Nov 2, 2026Verified source
- 22.
Hungary: maximum average headcount to opt for KIVA : 100
« az átlagos statisztikai állományi létszáma az adóévet megelőző adóévben várhatóan nem haladja meg az 100 főt; »
Nemzeti Jogszabálytár, « 2012. évi CXLVII. törvény a kisadózó vállalkozások tételes adójáról és a kisvállalati adóról »Verified on Nov 2, 2026Verified source
- 23.
Hungary: maximum turnover and balance sheet total to opt for the KIVA : HUF 6,000,000,000
« elszámolandó bevétele várhatóan nem haladja meg a 6 milliárd forintot »
Nemzeti Jogszabálytár, « 2012. évi CXLVII. törvény a kisadózó vállalkozások tételes adójáról és a kisvállalati adóról »Verified on Nov 2, 2026Verified source
- 24.
Hungary: turnover threshold above which a company leaves KIVA : HUF 12,000,000,000
« a 12 milliárd forintos bevételi értékhatár negyedév első napján történő meghaladása esetén, a túllépést megelőző nappal; »
Nemzeti Jogszabálytár, « 2012. évi CXLVII. törvény a kisadózó vállalkozások tételes adójáról és a kisvállalati adóról »Verified on Nov 2, 2026Verified source
- 25.
Hungary: average headcount above which a company leaves the KIVA regime : 200
« ha a létszámnövekedés miatt az adóalany átlagos statisztikai állományi létszáma meghaladta a 200 főt. »
Nemzeti Jogszabálytár, « 2012. évi CXLVII. törvény a kisadózó vállalkozások tételes adójáról és a kisvállalati adóról »Verified on Nov 2, 2026Verified source
- 26.
Hungary: monthly flat-rate KATA tax : HUF 50,000
« A tételes adó mértéke havonta 50 ezer forint. »
Nemzeti Jogszabálytár, « 2022. évi XIII. törvény a kisadózó vállalkozók tételes adójáról (állapot: 2023.08.01.) »Verified on Nov 2, 2026Verified source
- 27.
Hungary: annual KATA revenue ceiling before the special tax applies : HUF 18,000,000
« A (4) bekezdésben meghatározott keretösszeg 18 millió forint. »
Nemzeti Jogszabálytár, « 2022. évi XIII. törvény a kisadózó vállalkozók tételes adójáról (állapot: 2023.08.01.) »Verified on Nov 2, 2026Verified source
- 28.
Hungary: KATA special tax on revenue exceeding the ceiling : 40%
« keretösszeget meghaladó rész után 40 százalékos mértékű különadót (a továbbiakban: különadó) fizet. »
Nemzeti Jogszabálytár, « 2022. évi XIII. törvény a kisadózó vállalkozók tételes adójáról (állapot: 2023.08.01.) »Verified on Nov 2, 2026Verified source
- 29.
Hungary: consolidated revenue threshold for groups subject to the global minimum tax : €750,000,000
« az adóévet közvetlenül megelőző négy adóév közül legalább kettőben eléri vagy meghaladja a 750 000 000 eurót. »
Nemzeti Jogszabálytár, « 2023. évi LXXXIV. törvény a globális minimum-adószintet biztosító kiegészítő adókról »Verified on Nov 2, 2026Verified source
- 30.
Hungary: minimum effective tax rate for large groups (Pillar Two) : 15%
« minimum-adómérték: tizenöt százalék (15%) »
Nemzeti Jogszabálytár, « 2023. évi LXXXIV. törvény a globális minimum-adószintet biztosító kiegészítő adókról »Verified on Nov 2, 2026Verified source
- 31.
Hungary: length of stay beyond which an EEA national must register : 90 days
« the right of residence exceeding ninety days within a one hundred and eighty day period »
Országos Idegenrendészeti Főigazgatóság (OIF), « Registration Certificate for EEA Nationals »Verified on Nov 2, 2026Verified source
- 32.
Hungary: reference period for calculating the length of stay of EEA nationals : 180 days
« the right of residence exceeding ninety days within a one hundred and eighty day period »
Országos Idegenrendészeti Főigazgatóság (OIF), « Registration Certificate for EEA Nationals »Verified on Nov 2, 2026Verified source
- 33.
Hungary: deadline to apply for the registration certificate (EEA national) : 93 days
« at the latest on the ninety-third day from the date of entry »
Országos Idegenrendészeti Főigazgatóság (OIF), « Registration Certificate for EEA Nationals »Verified on Nov 2, 2026Verified source
- 34.
Hungary: fees for the registration certificate of an EEA national : HUF 1,000
« The administrative service fee charged for the issue of a registration certificate is HUF 1,000, payable by way of electronic payment instrument (bank card) or in the form of bank deposit (using the cheque supplied by the regional directorate). »
Országos Idegenrendészeti Főigazgatóság (OIF), « Registration Certificate for EEA Nationals »Verified on Nov 2, 2026Verified source
- 35.
Hungary: minimum investment in real estate fund units for the guest investor residence permit : €250,000
« acquisition of an investment fund share of at least EUR 250 000 »
Országos Idegenrendészeti Főigazgatóság (OIF), « Residence permit for guest investor »Verified on Nov 2, 2026Verified source
- 36.
Hungary: minimum donation to a higher education institution for the guest investor residence permit : €1,000,000
« provision of a financial donation in an amount of at least EUR 1 000 000 »
Országos Idegenrendészeti Főigazgatóság (OIF), « Residence permit for guest investor »Verified on Nov 2, 2026Verified source
- 37.
Hungary: maximum duration of the guest investor residence permit : 10 years
« Validity period of the document is maximised in 10 years »
Országos Idegenrendészeti Főigazgatóság (OIF), « Residence permit for guest investor »Verified on Nov 2, 2026Verified source
- 38.
Hungary: minimum net monthly income required for the White Card (digital nomads) : €3,000
« equal to or exceeds EUR 3,000 net for at least 6 months prior to entry »
Országos Idegenrendészeti Főigazgatóság (OIF), « White Card residency for digital nomads »Verified on Nov 2, 2026Verified source
- 39.
Hungary: required period of receipt of the minimum income before entry for the White Card : 6 months
« equal to or exceeds EUR 3,000 net for at least 6 months prior to entry »
Országos Idegenrendészeti Főigazgatóság (OIF), « White Card residency for digital nomads »Verified on Nov 2, 2026Verified source
- 40.
Hungary: maximum duration of the White Card : 1 year
« Validity period of the document is maximised in 1 year »
Országos Idegenrendészeti Főigazgatóság (OIF), « White Card residency for digital nomads »Verified on Nov 2, 2026Verified source
- 41.
Hungary: standard VAT rate (ÁFA) : 27%
« Magyarország 27 5 / 18 »
Commission européenne — Your Europe, « Áfa – szabályok, adókulcsok: általános, egyedi és kedvezményes adókulcsok (utolsó frissítés: 13/07/2026) »Verified on Nov 2, 2026Verified source
- 42.
Hungary: reduced VAT rate (ÁFA) : 18%
« Magyarország 27 5 / 18 »
Commission européenne — Your Europe, « Áfa – szabályok, adókulcsok: általános, egyedi és kedvezményes adókulcsok (utolsó frissítés: 13/07/2026) »Verified on Nov 2, 2026Verified source
- 43.
Hungary: reduced VAT rate (ÁFA) : 5%
« Magyarország 27 5 / 18 »
Commission européenne — Your Europe, « Áfa – szabályok, adókulcsok: általános, egyedi és kedvezményes adókulcsok (utolsó frissítés: 13/07/2026) »Verified on Nov 2, 2026Verified source