News brief · Taxation
Hong Kong: strict territoriality and tax capped at 15%
Hong Kong combines strict territoriality, a capped rate schedule and no taxation of capital gains. The issue is no longer tax: it is political, and that is what now determines whether a Hong Kong project makes sense.
By Editorial team · on July 14, 2026
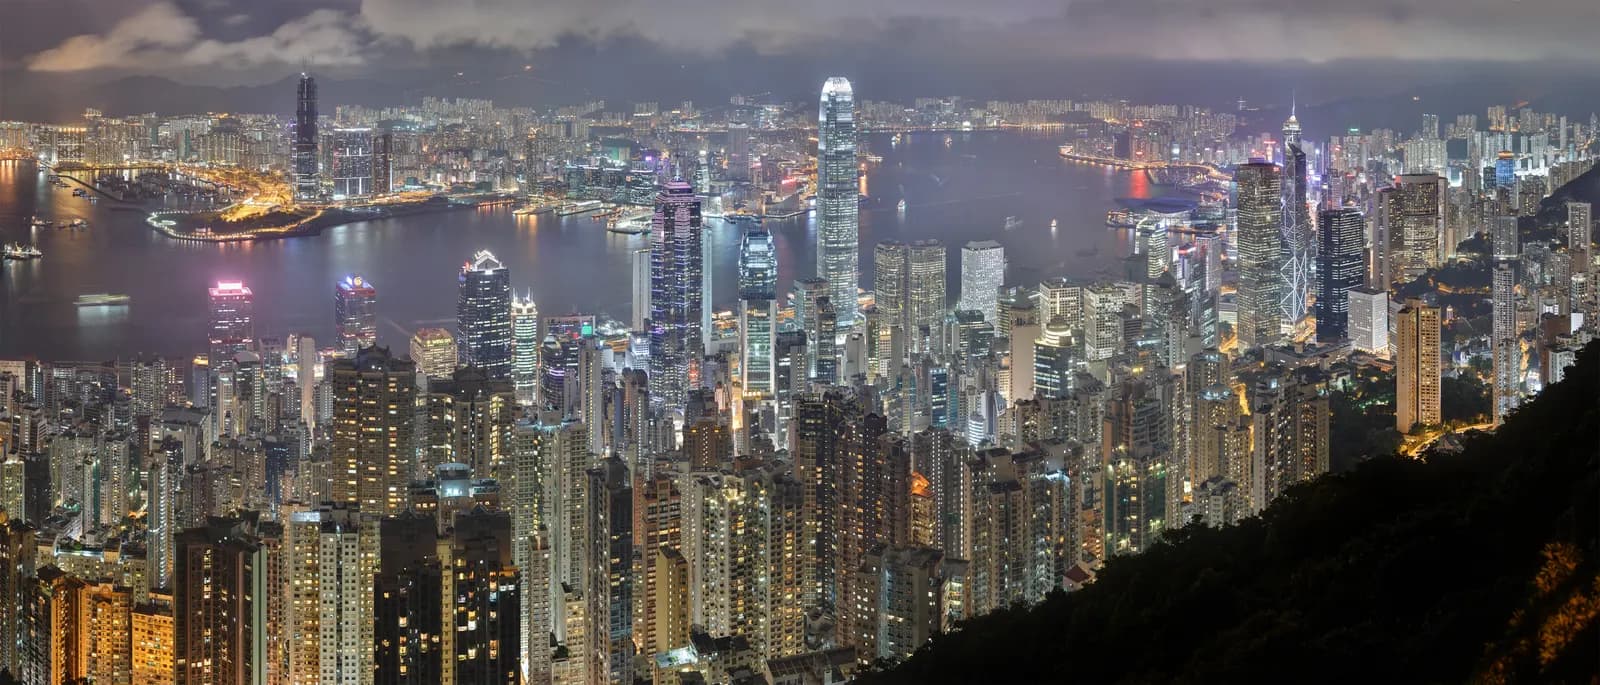
What Hong Kong taxes
Hong Kong applies strict territoriality: only Hong Kong-source income is taxable. Foreign-source income is not included in the tax base, even when received by a resident.
Salaries tax is calculated using whichever method is most favourable to the taxpayer: a progressive schedule ranging from 2%1 to 17%2, or a standard rate applied to net income.
This standard rate has two tiers: 16%3 on the first portion, then 16%4 above it. In practice it acts as a tax ceiling.
Capital gains are not taxed: the applicable rate is 0%5. Nor is there any inheritance tax or value added tax.
Corporate profits tax is 8.25%6 on the first band, then 16.5%7 at the standard rate.
Hong Kong's territoriality deserves clarification, as it is more demanding than it appears. What determines the source of employment income is neither the payer's residence nor the location of the bank account, but where the services are rendered. An employee working from Hong Kong earns Hong Kong-source income, whoever their employer.
Conversely, an executive who lives in Hong Kong but performs their duties abroad may escape salaries tax on the corresponding portion. The tax authority examines days of presence and the nature of the duties, and this analysis is the real technical work in a Hong Kong case.
Routes of entry
The investor programme requires a minimum net investment of HK$30,000,0008, or approximately about $3,800,0009. This is one of the highest thresholds in the world.
The talent scheme is the most widely used route. Its income-based category requires annual income of from HK$2,500,00010 and grants an initial stay of 36 months11.
The degree-based categories grant an initial stay of 24 months12, with a professional experience requirement of from 3 years13 in one of them.
This scheme is open without a prior job offer, which is rare: it allows people to settle first and look for work afterwards. This is Hong Kong's main asset for a qualified professional.
The issue that is not about tax
The decisive question for a Hong Kong project is no longer the tax rate. It lies in the evolution of the political and legal framework since the 2020 National Security Law, and in the path of integration with the rest of China.
This evolution has concrete effects: on freedom of expression and association, on the perceived independence of the judicial system, on the make-up of the expatriate population, and on international companies' decisions about where to locate.
It has not, however, changed the tax regime, which remains one of the simplest and lightest in the developed world. The contradiction is real and should be stated as such.
A Hong Kong project therefore comes down to a trade-off that tax does not settle: an exceptional tax environment against an institutional uncertainty that no one can put a date on.
We do not publish data on changes in the expatriate population or in company establishments: we did not find an up-to-date official series documenting these movements.
Key takeaways
- Territoriality is strict: only Hong Kong-source income is taxable.
- The standard rate caps salaries tax at 16%4 on the second tier.
- No capital gains tax, no inheritance tax, no value added tax.
- The talent scheme can be obtained without a prior job offer.
- Institutional uncertainty is now the decisive factor, and it cannot be quantified.
Finally, housing costs are the main practical constraint: Hong Kong is among the most expensive markets in the world per square metre, and for a family the tax advantage is largely eaten up by this item and by international schooling.
Please note
Sources and verification dates
- 1.
Hong Kong: rate of the first bracket of the progressive salaries tax scale : 2%
« Year of Assessment 2020/21 onwards — Net chargeable Income / Rate : On the First $50,000 — 2% ; On the Next $50,000 — 6% ; On the Next $50,000 — 10% ; On the Next $50,000 — 14% ; Remainder — 17%. Standard Rate — 2024/25 onwards : Two-tiered Standard Rates — On the first $5,000,000 of net income 15% ; Remainder 16%. — GovHK / Inland Revenue Department, « Tax Rates of Salaries Tax & Personal Assessment ». »
gov.hkVerified on Nov 2, 2026Verified source
- 2.
Hong Kong: top rate of the progressive salaries tax scale : 17%
« On the Next 50,000 14% 7,000 200,000 16,000 Remainder 17% »
gov.hkVerified on Nov 2, 2026Verified source
- 3.
Hong Kong: second tier of the standard rate : 16%
« Standard Rate — Year of Assessment 2020/21 to 2023/24 : 15% ; 2024/25 onwards : Two-tiered Standard Rates — On the first $5,000,000 of net income 15% ; Remainder 16%. — GovHK / Inland Revenue Department, « Tax Rates of Salaries Tax & Personal Assessment ». »
gov.hkVerified on Nov 2, 2026Verified source
- 4.
Hong Kong: second tier of the standard rate : 16%
« Standard Rate — Year of Assessment 2020/21 to 2023/24 : 15% ; 2024/25 onwards : Two-tiered Standard Rates — On the first $5,000,000 of net income 15% ; Remainder 16%. — GovHK / Inland Revenue Department, « Tax Rates of Salaries Tax & Personal Assessment ». »
gov.hkVerified on Nov 2, 2026Verified source
- 5.
Hong Kong: taxation of capital gains : 0%
« We only levy taxes on business profits under profits tax, property rental income under property tax and employment income under salaries tax. Salaries tax rate is capped at 15% whereas profits tax rate for corporations is 16.5%. There is no value-added or sales tax; no capital gains tax; no withholding tax on dividends and interest; and no estate duty in Hong Kong. — Financial Services and the Treasury Bureau, « Prevailing Tax Policy ». »
fstb.gov.hkVerified on Nov 2, 2026Verified source
- 6.
Hong Kong: profits tax rate on the first tier of profits : 8.25%
« Two-tiered rates (for the year of assessment 2018/19 onwards) Corporations: 8.25% on assessable profits up to $2,000,000; and 16.5% on any part of assessable profits over $2,000,000 »
ird.gov.hkVerified on Nov 2, 2026Verified source
- 7.
Hong Kong: standard profits tax rate for corporations : 16.5%
« Normal rate (for the year of assessment 2008/09 onwards) Corporations: 16.5% »
ird.gov.hkVerified on Nov 2, 2026Verified source
- 8.
Hong Kong: minimum net investment under the investor programme : HK$30,000,000
« An Applicant must make investment of a minimum of HK$30 million Net (or equivalent in foreign currencies) in the Permissible investment assets. Assets acquired before the launch date of the Scheme shall not be counted towards the fulfillment of minimum investment threshold. […] net assets […] with a Market value of not less than HK$30 million Net (or equivalent in foreign currencies) throughout the six months preceding the date he lodged his application for Net Asset Assessment — New Capital Investment Entrant Scheme (InvestHK / Immigration Department), « Eligibility Criteria ». »
newcies.gov.hkVerified on Nov 2, 2026Verified source
- 9.
Hong Kong: approximate equivalent of the investor programme threshold : $3,800,000
« An Applicant must make investment of a minimum of HK$30 million Net (or equivalent in foreign currencies) in the Permissible investment assets. — New Capital Investment Entrant Scheme, « Eligibility Criteria ». 30 M HK$ ≈ 3,85 M US$ (parité quasi fixe 7,8 HKD/USD). »
newcies.gov.hkVerified on Nov 2, 2026Verified source
- 10.
Hong Kong, Top Talent Pass: annual income required under category A : HK$2,500,000
« persons with annual income reaching HK$2.5 million or above, or its equivalent in foreign currency, in the year immediately preceding the date of application »
immd.gov.hkVerified on Nov 2, 2026Verified source
- 11.
Hong Kong, Top Talent Pass: initial period of stay granted in category A : 36 months
« Successful TTPS applicant will normally be granted an initial stay of 36 months (Category A) / 24 months (Categories B and C) on time limitation only »
immd.gov.hkVerified on Nov 2, 2026Verified source
- 12.
Hong Kong, Top Talent Pass: initial period of stay granted in categories B and C : 24 months
« Successful TTPS applicant will normally be granted an initial stay of 36 months (Category A) / 24 months (Categories B and C) on time limitation only »
immd.gov.hkVerified on Nov 2, 2026Verified source
- 13.
Hong Kong, Top Talent Pass: work experience required in category B, over the previous five years : 3 years
« degree graduatesNote 2 & 3 of the eligible universitiesNote 4 with at least three years of work experienceNote 5 over the past five years immediately preceding the date of applicationNote 6 (Category B) »
immd.gov.hkVerified on Nov 2, 2026Verified source