News brief · Cost of living
Colombia: Medellín, Latin America's nomad capital
Medellín has become a leading destination for remote workers in Latin America. The Colombian visa is accessible, but the tax residency threshold is counted over a rolling period — which makes it easier to cross than elsewhere.
By Editorial team · on June 19, 2026
Why Medellín
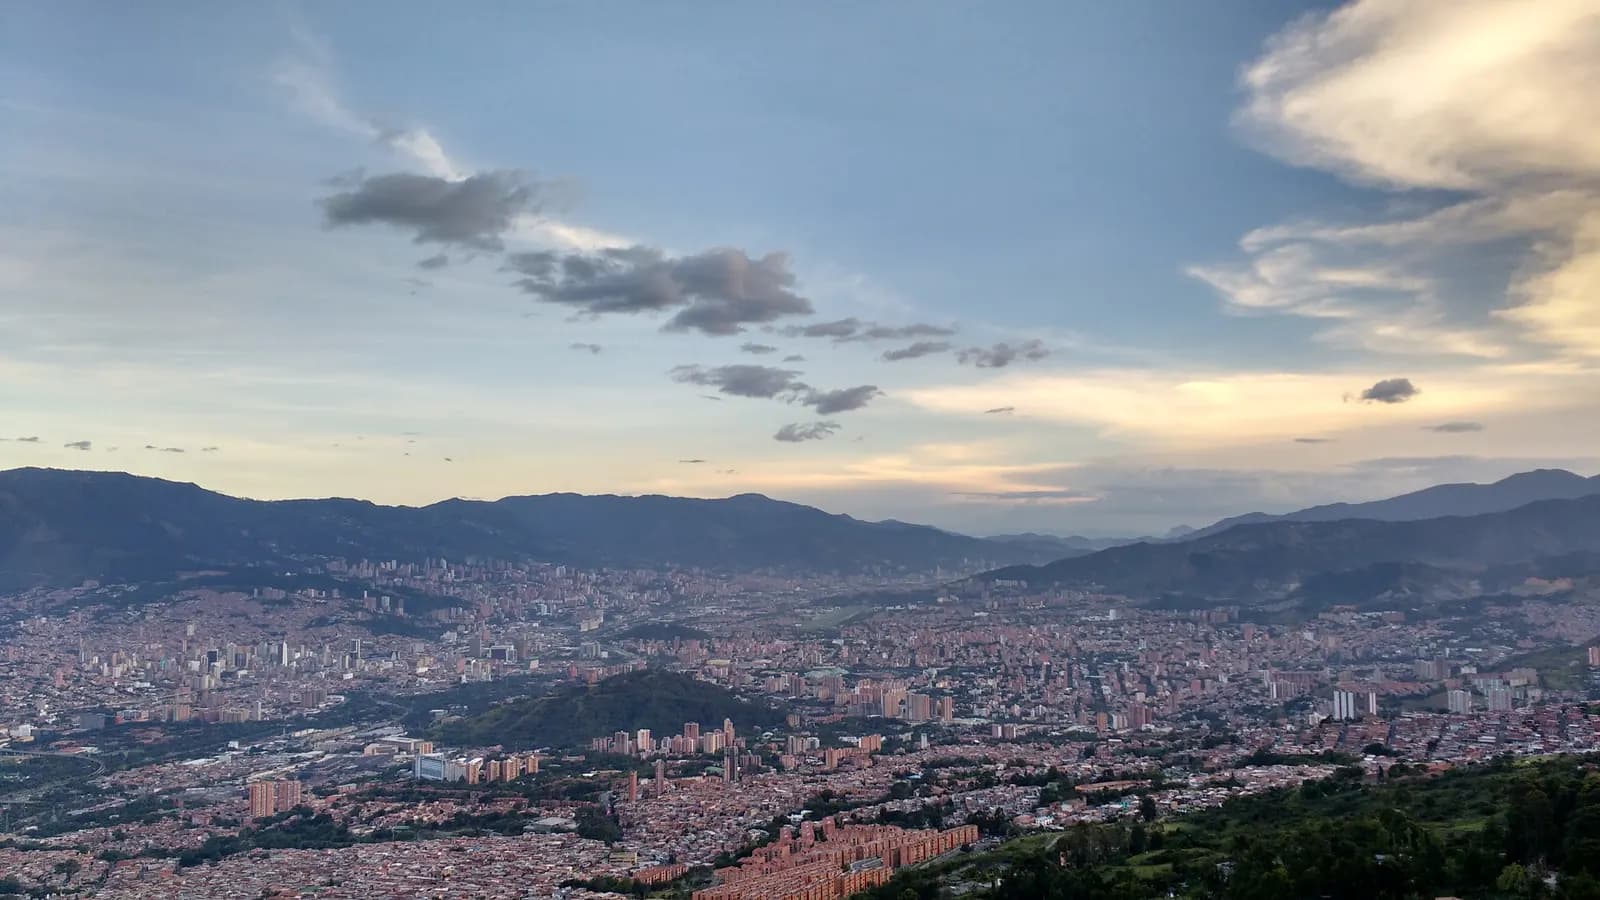
The city brings together three things that are rarely combined: a constantly mild climate thanks to its altitude, a cost of living far below European levels, and good-quality digital connectivity in the central neighbourhoods.
It has also undergone a well-documented urban transformation — metro, cable cars, neighbourhood libraries — which has changed its image and part of its reality.
The influx of remote workers has had the now familiar effects on rents in a few neighbourhoods, El Poblado and Laureles in particular, and it has fuelled a local public debate about this presence.
We do not publish a rent index for Medellín: we have not found an official Colombian series publishing rents by neighbourhood, and we do not reproduce platform estimates.
The contrast with Bogotá explains part of this enthusiasm. The capital is higher, colder and more sprawling, and commuting times there are considerable; Medellín fits within a valley, can be crossed by metro and enjoys a constant temperature all year round. For someone who works from home, this difference in daily life weighs more than the cultural offering.
On the other hand, Medellín's international air connections remain limited: most routes to Europe go through Bogotá or a North American hub, which significantly lengthens journeys and increases the cost of trips back to France.
The visa, and its threshold
Colombia issues a visa for digital nomads and remote workers, reserved for people working for an employer or clients located outside the country.
The required reference monthly income stands at about $1,4001, among the lowest thresholds of comparable schemes.
The maximum duration of the permit is up to 2 years2. It does not allow the holder to be employed by a Colombian company and does not, in itself, constitute a path to permanent residence.
The decisive technical point lies elsewhere: Colombian tax residency is acquired through presence, continuous or not, of more than from 183 days3 within any period of three hundred and sixty-five days.
This rolling period does not coincide with the calendar year. A stay straddling two calendar years, which would not reach the threshold in either of them, can cross it over the rolling period — and this is a frequent source of error.
What tax residency entails
A Colombian tax resident is taxed on worldwide income. The scale reaches 39%4 at its top marginal rate.
Occasional gains of resident individuals are taxed at a flat rate of 15%5, and dividends are subject to a special rate of 20%6 in the case provided for by law.
Corporate income tax stands at 35%7. Colombia is therefore in no respect a low-tax jurisdiction.
A remote worker settled long-term in Medellín therefore becomes a Colombian taxpayer subject to a scale close to European levels. This is the reality that the cost-of-living narrative obscures, and it is rarely set out.
What to do
- Keep a count of days over a rolling period of three hundred and sixty-five days, not over the calendar year.
- Check the required income amount as at the date of application, as it is indexed.
- Do not work for a Colombian client without another permit.
- If tax residency is acquired, declare and pay tax on worldwide income.
- Handle the departure from France according to its own criteria and under the France–Colombia tax treaty.
Finally, safety remains a factor that national averages conceal and comparisons ignore. It varies considerably from one neighbourhood to another within Medellín itself, and it is a location criterion at least as decisive as rent. The neighbourhoods with the densest foreign presence are not necessarily those where integration is best, nor the most representative of the city.
Please note
Sources and verification dates
- 1.
Colombia: reference monthly means required of a digital nomad visa applicant : $1,400
« 4. En el caso de los solicitantes de Visa V para Nómadas Digitales, Emprendedores y Trabajadores remotos, […] el solicitante deberá demostrar mediante extractos bancarios que cuenta con ingresos mínimos equivalentes a tres (3) Salarios Mínimos Legales Mensuales Vigentes (smlmv). — Resolución 5477 de 2022 del Ministerio de Relaciones Exteriores. Salaire minimum 2026 : 1 750 905 COP → 3 smlmv = 5 252 715 COP par mois. »
cancilleria.gov.coVerified on Nov 2, 2026Verified source
- 2.
Colombia: maximum duration of the visa for digital nomads and remote workers : 2 years
« ARTÍCULO 46. Visa V Nómadas digitales — Alcance: Para prestar servicios de trabajo remoto o teletrabajo, desde Colombia, a través de medios digitales e internet, exclusivamente para empresas extranjeras […] Vigencia: Hasta por dos (2) años. — Resolución 5477 de 2022 (22 de julio) del Ministerio de Relaciones Exteriores, art. 46. »
cancilleria.gov.coVerified on Nov 2, 2026Verified source
- 3.
Colombia: presence within a three-hundred-and-sixty-five-day period giving rise to tax residency : 183 days
« ARTICULO 10. RESIDENCIA PARA EFECTOS TRIBUTARIOS. Se consideran residentes en Colombia para efectos tributarios las personas naturales que cumplan con cualquiera de las siguientes condiciones: 1. Permanecer continúa o discontinúamente en el país por más de ciento ochenta y tres (183) días calendario incluyendo días de entrada y salida del país, durante un periodo cualquiera de trescientos sesenta y cinco (365) días calendario consecutivos — Estatuto Tributario, art. 10 (modifié par la Ley 1607 de 2012), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 4.
Colombia: top marginal income tax rate for resident individuals : 39%
« ARTICULO 241. TARIFA PARA LAS PERSONAS NATURALES RESIDENTES Y ASIGNACIONES Y DONACIONES MODALES. El impuesto sobre la renta de las personas naturales residentes en el país […] se determinará de acuerdo con la siguiente tabla: — Estatuto Tributario, art. 241 (modifié par la Ley 2010 de 2019, art. 34) : barème progressif en UVT de 0 % (jusqu'à 1 090 UVT) à 39 % (au-delà de 31 000 UVT). »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 5.
Colombia: single rate on occasional gains for resident individuals : 15%
« ARTICULO 314. PARA PERSONAS NATURALES RESIDENTES. La tarifa única del impuesto correspondiente a las ganancias ocasionales de las personas naturales residentes en el país […] es quince por ciento (15%). ARTICULO 313. […] Fijase en quince por ciento (15%) la tarifa única sobre las ganancias ocasionales de las sociedades — Estatuto Tributario, art. 313 et 314 (modifiés par la Ley 2277 de 2022), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 6.
Colombia: special rate applicable to dividends and profit shares under article 245 : 20%
« ARTICULO 245. TARIFA ESPECIAL PARA DIVIDENDOS O PARTICIPACIONES RECIBIDOS POR SOCIEDADES Y ENTIDADES EXTRANJERAS Y POR PERSONAS NATURALES NO RESIDENTES. […] La tarifa del impuesto sobre la renta correspondiente a dividendos o participaciones percibidos por sociedades u otras entidades extranjeras sin domicilio principal en el país, por personas naturales sin residencia en Colombia y por sucesiones ilíquidas de causantes que no eran residentes en Colombia será del veinte por ciento (20%). — Estatuto Tributario, art. 245 (modifié par la Ley 2277 de 2022), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 7.
Colombia: standard corporate income tax rate : 35%
« ARTÍCULO 240. TARIFA GENERAL PARA PERSONAS JURÍDICAS. La tarifa general del impuesto sobre la renta aplicable a las sociedades nacionales y sus asimiladas, los establecimientos permanentes de entidades del exterior y las personas jurídicas extranjeras con o sin residencia en el país, obligadas a presentar la declaración anual del impuesto sobre la renta y complementarios, será del treinta y cinco por ciento (35%). — Estatuto Tributario, art. 240 (modifié par la Ley 2277 de 2022), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source