International mobility news

Antigua and Barbuda

Moving to Antigua and Barbuda in 2026: passport by investment and beaches

Antigua and Barbuda offers a competitive citizenship-by-investment programme, particularly attractive for families, with a minimal presence requirement (5 days over 5 years). No income tax and a renowned seaside setting.

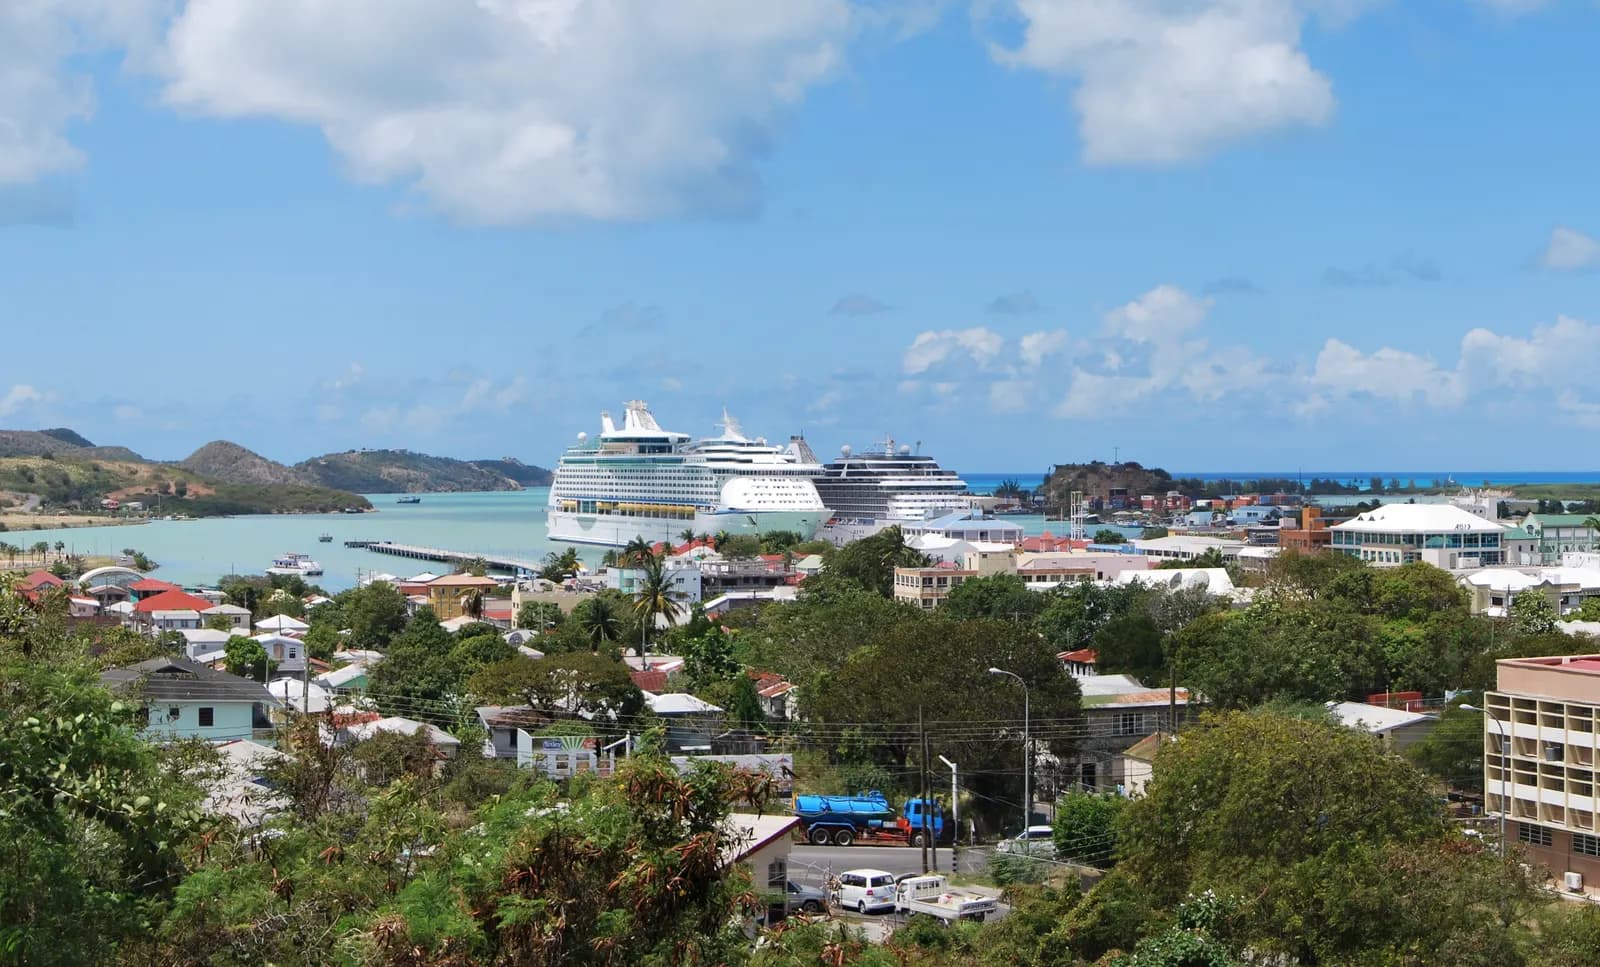
View of Antigua and Barbuda
Photo: This image or media was taken or created by Matt H. Wade. To see his entire portfolio, click here.@thatmattwade This image is protected by copyright! If you would like to use it, please read this first. — Wikimedia Commons (CC BY-SA)
Capital
St. John's
Currency
XCD
Region
Caribbean
Memberships
Commonwealth

Tax regimes at a glance

Each regime answers the same questions. A zero rate applies only to the income, person and period stated.

Your personal taxation

  • Residents: no personal income taxGeneral regime

    Who for?
    Resident individuals who are employees, retirees or live on investment income.
    Which income?
    Salaries, pensions, savings interest, dividends and capital gains received by a resident individual: personal income tax has been repealed.
    Which source?
    Not applicable to residents; self-employment income falls under the Unincorporated Business Tax.
    Conditions
    Social security contributions remain payable. The sales tax (ABST) applies to consumption at the standard rate. For a French national, citizenship by investment does not move tax residence: Article 4 B of the French General Tax Code (code général des impôts) applies as long as the household remains in France.
    Duration
    Permanent situation since the repeal.
    Since when?
    Personal Income Tax applicable from April 2005 to June 2016, repealed with effect from 1 July 2016.
    • 17% Antigua and Barbuda: standard rate of the Antigua and Barbuda Sales Tax (ABST)

    Official source · ird.gov.ag

  • Unincorporated Business Tax (self-employed individuals and sole proprietorships)General regime

    Who for?
    Sole proprietors, partnerships and other unincorporated businesses.
    Which income?
    Net profit from the activity (revenue minus business expenses), excluding personal expenses.
    Which source?
    Activity carried on in Antigua and Barbuda; the rule applicable to foreign income has not been verified.
    Conditions
    Progressive scale with a tax-free band; the bands are raised for partnerships according to the number of partners. Annual return and annual registration fee depending on turnover.
    Duration
    Permanent regime.
    Since when?
    Unincorporated Business Tax Act 2016, in force since 1 July 2016; scale taken from the 2021 FAQ, to be confirmed for 2026.
    • up to EC$42,000 Antigua and Barbuda: upper limit of the untaxed bracket of the Unincorporated Business Tax (sole proprietor)
    • 8% Antigua and Barbuda: intermediate rate of the Unincorporated Business Tax
    • 25% Antigua and Barbuda: top rate of the Unincorporated Business Tax

    Official source · ird.gov.ag

  • Non-residents: withholding tax on payments of Antiguan sourceGeneral regime

    Who for?
    Non-resident individuals and companies receiving payments from an Antiguan payer.
    Which income?
    Payments covered by Section 40 of the Income Tax Act (detailed categories not verified here).
    Which source?
    Income of Antiguan source only.
    Conditions
    Tax withheld by the payer at the standard rate; reduced rate for beneficiaries covered by the CARICOM tax agreement.
    Duration
    Permanent regime.
    Since when?
    In force; the Inland Revenue Department form is undated.
    • 25% Antigua and Barbuda: withholding tax on payments to non-residents (standard rate)

    Official source · forms.gov.ag

Your company

  • Corporate income tax: standard rateGeneral regime

    Who for?
    Companies subject to tax in Antigua and Barbuda.
    Which income?
    Taxable income of the company.
    Which source?
    Detailed territoriality rules not verified.
    Conditions
    Separate sector-specific rates are said to exist for certain financial institutions and regulated sectors: not verified here. Tax concessions and the former IBC regime not verified.
    Duration
    Permanent regime.
    Since when?
    Rate in force since the Income Tax (Amendment) Act 2008, with effect from 2008.
    • 25%

    Official source · laws.gov.ag

Compare with other countries:Foreign incomeCompany taxationRegimes for new residents

Key figures

  • Flight from Parisabout12 hoursVerified on Nov 2, 2026

Personal taxation

Antigua and Barbuda no longer levies personal income tax on residents' salaries, pensions and investment income. This is the feature that structures the country's appeal, and it explains why taxation is almost never the subject of the cases we handle: citizenship is.

This absence is confirmed by the tax authority: personal income tax, applied from April 2005 to June 2016, was repealed on 1 July 2016. There are two exceptions. Income from self-employment or from an unincorporated business falls under the Unincorporated Business Tax, a progressive scale on net profit: nil up to up to EC$42,0002 for a sole proprietor, then 8%3 and finally 25%4 on the upper band, according to the scale published in 2021, to be confirmed for 2026. Non-residents, for their part, are subject on certain payments of Antiguan source to withholding tax of 25%5 at the standard rate, reduced under the CARICOM tax agreement.

We do not publish any rule on inheritance and gift tax: they do not appear in the sources we reviewed.

This situation calls for a caveat for an applicant. An absence of taxation observed today is neither a commitment nor a guarantee of stability: several states in the region have introduced or reintroduced levies under budget recovery programmes or international commitments.

Above all, the absence of local tax settles nothing for a French national. As long as the household or the centre of economic interests remains in France, French tax domicile continues within the meaning of Article 4 B of the French General Tax Code (code général des impôts), and an Antiguan passport changes nothing. This is the most frequent mistake regarding this destination: confusing the acquisition of a nationality with the transfer of tax residence.

Value added tax and excise duties make up the bulk of revenue, which shifts the burden to consumption. For an actual resident, the cost of living therefore includes indirect taxation that the absence of income tax does not always offset.

Residence routes and visas

The country runs one of the oldest citizenship-by-investment programmes in the Caribbean. It is managed by a dedicated unit, which publishes its amounts.

The National Development Fund

The most commonly used route is the contribution to the National Development Fund. It requires a payment of at least $230,0006, or approximately about €230,0007.

The real estate route

Applicants who choose the real estate option must make an investment of at least from $300,0008 in an approved project.

Other options exist, notably a contribution of at least from $260,0009 to the University of the West Indies fund, reserved for large families and often the least expensive per person beyond a certain number of members.

The presence requirement

This is the Antiguan particularity, and it is decisive. Citizenship may be withdrawn if the citizen does not spend at least 5 days10 in the territory during the 5 years11 following its acquisition.

The requirement is modest in volume, but it is real and enforced. It means organising at least one trip, documenting it and keeping proof of it — something many holders neglect, believing their naturalisation to be final.

Application fees, due diligence fees and government fees applicable to each option are not included here: they do not appear in full in our extracts and should be requested from an authorised agent.

Real estate

Acquisition by a foreigner requires, as in several states of the region, a land holding licence issued by the authorities, except where the purchase is made under the citizenship programme, which carries its own regime.

The market open to citizenship applicants is a sub-market: approved projects are limited in number, priced above the threshold of from $300,0008, and their resale is most often aimed at another applicant to the programme.

Two consequences follow. Liquidity depends on the continuity of the programme itself, not on local demand. And a minimum holding period is generally imposed before any resale that in turn qualifies for citizenship.

Finally, the holding costs specific to an island must be factored in: insurance against climate risks, maintenance in a tropical climate, remote management. They weigh more heavily on net yield than a tax differential.

We do not publish transfer duties, Antiguan property tax, or the minimum holding period imposed on properties acquired through the programme: they do not appear in our sources.

Cost of living

Antigua is a small island economy that relies heavily on imports. Food, capital goods and fuel arrive by ship, and their price includes freight and excise duties.

We do not publish a typical monthly budget: we have not found an official Antiguan series measuring a basket of expenses comparable to that of an expatriate.

Three items dominate the budget of an actual resident. Electricity, produced from imported fuels and significantly more expensive than in Europe. Healthcare, where serious cases require evacuation to a regional or North American centre, which makes international insurance indispensable. And private schooling for an international curriculum.

For the vast majority of citizenship holders, however, the question does not arise in these terms: they do not live on the island and stay there only as long as necessary to satisfy the presence requirement.

For those who actually settle, the island offers, by contrast, a quality of life that few low-tax destinations match: an established English-speaking community, direct flights to North America and Europe in season, and a human scale that simplifies administrative life. These are real factors in a relocation project, even if they cannot be quantified.

The hurricane season, from June to November, is the flip side of this picture. It determines the cost of home insurance, the availability of tradespeople and sometimes the continuity of services. An annual budget that ignores it is a six-month budget.

Procedures and timelines

  1. Go through an authorised agent: direct filing is not provided for by the programme;
  2. choose the option according to the family's composition, as the cost per person varies widely from one option to another;
  3. budget for the whole — contribution or investment, application fees, due diligence, professional fees — and not just the advertised threshold;
  4. plan, as soon as citizenship is obtained, the trip that will satisfy the presence requirement, and keep proof of it;
  5. treat the departure from France as a separate matter: nationality does not amount to a transfer of tax residence.

We do not publish processing times: we have no official, dated and quantified source for the Antiguan programme.

The order of steps has a direct consequence here: the presence requirement runs from the acquisition of citizenship, not from the decision to settle. A holder who postpones the first stay uses up part of the period without realising it, and ends up having to travel within a shortened window.

Points to watch

  • The presence requirement of 5 days10 over 5 years11 is backed by possible forfeiture of citizenship: it is not a formality.
  • Citizenship carries neither tax residence nor an exit from French tax domicile.
  • A property acquired through the programme is traded on a sub-market whose liquidity depends on the programme itself.
  • The amounts displayed are not the full cost: government fees, due diligence and professional fees come on top.
  • The Antiguan passport gives visa-free access to about 15112 — markedly fewer than a European Union passport.

Finally, Caribbean programmes are under continuous international pressure: stricter vetting requirements, threshold revisions, and visa exemptions being called into question by major partners. For a French national, the value of a second, Antiguan passport therefore lies neither in mobility, which it reduces, nor in taxation, which it does not settle — it is, where relevant, a legal diversification whose value must be assessed on its own merits.

Pros & cons

Pros

  • No personal income tax

  • “365 beaches”, excellent air connections for the region

  • Passport with ~150 visa-free destinations

Cons

  • Minimum presence requirement of 5 days13 over more than 5 years14

  • High cost of living (imports)

  • Limited local healthcare

  • CBI prices and rules regulated at regional level — check at the time of the application

Frequently asked questions

What investment is required for Antiguan citizenship?

From from $230,00015 (donation to the national fund or real estate), in 4 months16 to 8 months17.

Do you have to live there?

A minimum presence of 5 days13 over the first 5 years is required.

Is there an income tax?

No.

Residence and citizenship by investment programmes

Data shared with the comparison tool: same amounts, same sources. Compare with other programmes

Antigua and Barbuda Citizenship by Investment Programme

Citizenship · Open · Official page

Minimum entry
  • from $230,000 — non-refundable contribution, familyOne-off non-refundable contribution to the NDF, same amount for a single applicant or a family of up to 4 people (fees in addition).cip.gov.ag · Verified on Oct 13, 2026
  • from $260,000 — non-refundable contribution, familyReserved for families of at least 6 people; amount includes processing fees; entitles the family to a one-year scholarship (tuition fees) at the UWI.cip.gov.ag · Verified on Nov 2, 2026
  • from $300,000 — investment, main applicantApproved property, resale prohibited for 5 years (unless another approved property is purchased); processing fees in addition.cip.gov.ag · Verified on Nov 2, 2026
  • from $400,000 — investment, main applicantMinimum share of each investor in a joint project of at least 2 people totalling at least USD 5,000,000.cip.gov.ag · Verified on Oct 13, 2026
  • from $1,500,000 — investment, main applicantInvestment by the applicant alone in an approved business; amount unchanged by the 2024 reform (original date not verified).cip.gov.ag · Verified on Oct 13, 2026
Government fees (main applicant)
  • $300 — government fees, per personPassport fee payable by each family member.cip.gov.ag · Verified on Oct 13, 2026
  • $8,500 — due diligence fees, main applicantNon-refundable fee, paid in full on submission; same schedule for all options.cip.gov.ag · Verified on Oct 13, 2026
  • $10,000 — government fees, main applicantGovernment processing fee, NDF, real estate and business options; 10% on application, balance after approval.cip.gov.ag · Verified on Oct 13, 2026
Family
  • $2,000 — cost per family member, per childPer dependent child aged 12 to 17; free from 0 to 11 years.cip.gov.ag · Verified on Oct 13, 2026
  • $4,000 — cost per family member, per dependantPer dependant aged 18 to 30 or parent aged 55 and over.cip.gov.ag · Verified on Oct 13, 2026
  • $5,000 — cost per family member, spouseNon-refundable background check fee for the spouse.cip.gov.ag · Verified on Oct 13, 2026
  • $10,000 — cost per family member, per dependantFrom the 5th dependant onwards (all options; for the UWI option, beyond a family of 6).cip.gov.ag · Verified on Oct 13, 2026
  • $20,000 — cost per family member, familyProcessing fee for a family of no more than 4 people, NDF, real estate and business options.cip.gov.ag · Verified on Oct 13, 2026
Processing time
Not provided
Required stay
  • from 5 days — minimum stay, per personDays to be spent in the country during the 5 calendar years following the grant of citizenship, failing which citizenship may be revoked.cip.gov.ag · Verified on Oct 13, 2026
Permit duration
Not provided

Banks and accounts

Banks and accounts for this country

See this country on the tax map

Please note

General information, as of the date shown. A draft reform is not a rule in force: check the conditions with the authorities or a professional before deciding. Terms of use and disclaimers

Sources and verification dates

  1. 1.

    Flight from Paris : 12 hours

    Verified on Nov 2, 2026

  2. 2.

    Antigua and Barbuda: upper limit of the untaxed bracket of the Unincorporated Business Tax (sole proprietor) : EC$42,000

    « Sole Trader $0 to $42,000 $42,001 to $186,000 $186,001 and over 0% 8% 25% »

    Inland Revenue Department, Antigua and Barbuda, « Unincorporated Business Tax (UBT) Frequently Asked Questions »Verified on Nov 2, 2026Verified source

  3. 3.

    Antigua and Barbuda: intermediate rate of the Unincorporated Business Tax : 8%

    « Sole Trader $0 to $42,000 $42,001 to $186,000 $186,001 and over 0% 8% 25% »

    Inland Revenue Department, Antigua and Barbuda, « Unincorporated Business Tax (UBT) Frequently Asked Questions »Verified on Nov 2, 2026Verified source

  4. 4.

    Antigua and Barbuda: top rate of the Unincorporated Business Tax : 25%

    « Sole Trader $0 to $42,000 $42,001 to $186,000 $186,001 and over 0% 8% 25% »

    Inland Revenue Department, Antigua and Barbuda, « Unincorporated Business Tax (UBT) Frequently Asked Questions »Verified on Nov 2, 2026Verified source

  5. 5.

    Antigua and Barbuda: withholding tax on payments to non-residents (standard rate) : 25%

    « (765) Amount paid to companies not qualifying for a reduced rate (765) (770) Tax Rate (25%) (770) .25 »

    Inland Revenue Department, Antigua and Barbuda, « Corporate Income Tax Annual Return — Work sheet for withholding tax (Appendix B2) »Verified on Nov 2, 2026Verified source

  6. 6.

    Antigua and Barbuda: minimum contribution to the National Development Fund : $230,000

    « Acquisition of citizenship under the NDF investment option requires a contribution to the National Development Fund in the minimum sum of US$230,000 per application. »

    cip.gov.agVerified on Nov 2, 2026Verified source

  7. 7.

    antigua-et-barbuda.cbi.eur.230000 : €230,000

    Verified on Nov 2, 2026

  8. 8.

    Antigua and Barbuda, CIP: approved real estate investment : $300,000

    « may choose to purchase property valued at minimum US$300,000 »

    cip.gov.agVerified on Nov 2, 2026Verified source

  9. 9.

    Antigua and Barbuda, CIP: contribution to the University of the West Indies (UWI) fund : $260,000

    « US$260,000 contribution (inclusive of processing fees) »

    cip.gov.agVerified on Nov 2, 2026Verified source

  10. 10.

    Antigua and Barbuda: minimum presence required of the new citizen : 5 days

    « Deprivation of citizenship may occur if the citizen does not spend at least 5 days in Antigua and Barbuda during the period of five calendar years after having obtained citizenship and they will not be entitled to repayment of any investment, contribution or purchase price made by them in their original application for citizenship. »

    cip.gov.agVerified on Nov 2, 2026Verified source

  11. 11.

    Antigua and Barbuda: period over which the minimum presence is assessed : 5 years

    « Deprivation of citizenship may occur if the citizen does not spend at least 5 days in Antigua and Barbuda during the period of five calendar years after having obtained citizenship »

    cip.gov.agVerified on Nov 2, 2026Verified source

  12. 12.

    Antigua and Barbuda passport: visa-free destinations : 151

    « Henley Passport Index — classement des passeports par nombre de destinations accessibles sans visa préalable (données IATA), consulté à la date indiquée. Valeur reprise de l’index de l’ancien site (barème à 227 destinations). »

    henleyglobal.comVerified on Nov 2, 2026Verified source

  13. 13.

    antigua-et-barbuda.golden-visa.jours.5 : 5 days

    « The passport will be valid for a period of 5 years and will be considered for renewal subject to the recipient having spent a total of 5 days in Antigua and Barbuda, since gaining citizenship, within the 5 year period. — Citizenship by Investment Unit, Antigua and Barbuda, « Antigua and Barbuda Passport ». »

    cip.gov.agVerified on Nov 2, 2026Verified source

  14. 14.

    antigua-et-barbuda.golden-visa.ans.5 : 5 years

    « The passport will be valid for a period of 5 years and will be considered for renewal subject to the recipient having spent a total of 5 days in Antigua and Barbuda, since gaining citizenship, within the 5 year period. »

    cip.gov.agVerified on Nov 2, 2026Verified source

  15. 15.

    antigua-et-barbuda.cbi.usd.230000 : $230,000

    « Acquisition of citizenship under the NDF investment option requires a contribution to the National Development Fund in the minimum sum of US$230,000 per application. »

    cip.gov.agVerified on Nov 2, 2026Verified source

  16. 16.

    antigua-et-barbuda.cbi.mois.4 : 4 months

    Verified on Nov 2, 2026

  17. 17.

    antigua-et-barbuda.cbi.mois.8 : 8 months

    Verified on Nov 2, 2026