Colombia
Moving to Colombia in 2026: nomad visa, low cost of living and diversity
Colombia attracts nomads and entrepreneurs with an accessible nomad visa, a low cost of living and a wide variety of climates and landscapes. Tax residence beyond 183 days entails worldwide taxation, which should be planned for in advance.
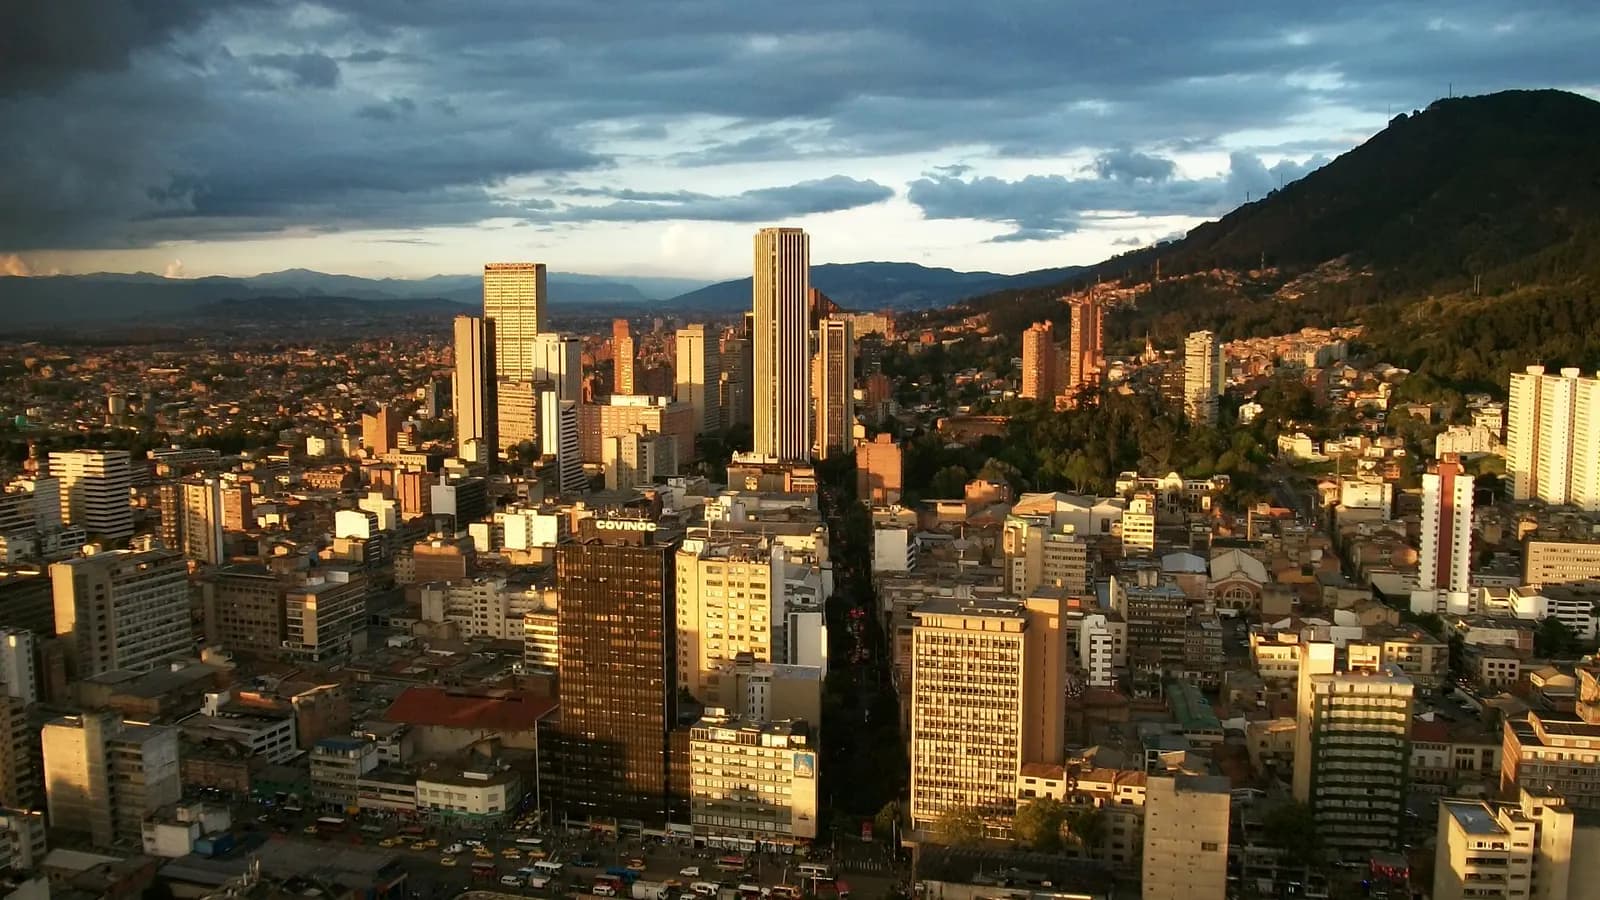
- Capital
- Bogotá
- Currency
- COP
- Region
- Americas
Tax regimes at a glance
Each regime answers the same questions. A zero rate applies only to the income, person and period stated.
Your personal taxation
Personal income tax for residentsGeneral regime
- Who for?
- Tax residents: individuals present in Colombia beyond the day threshold over a rolling period, not per calendar year, and other cases under article 10 of the tax statute.
- Which income?
- Income under the general schedules (employment, capital, non-professional income), pensions and dividends.
- Which source?
- Residents: worldwide-source income, with a foreign tax credit. Non-residents: Colombian-source income only. The France–Colombia tax treaty allocates the right to tax.
- Conditions
- Progressive scale; dividends from Colombian companies are included in the tax base with a tax credit; dividends paid to non-residents are subject to the special rate in article 245.
- Duration
- Permanent regime.
- Since when?
- Scale resulting from Law 2277 of 2022, applied since 2023.
- from 183 days Colombia: presence within a three-hundred-and-sixty-five-day period giving rise to tax residency
- 39% Colombia: top marginal income tax rate for resident individuals
- 20% Colombia: special rate applicable to dividends and profit shares under article 245
Occasional gainsSpecial regime
- Who for?
- Resident individuals.
- Which income?
- Capital gains on the disposal of assets held beyond the statutory minimum period, inheritances, gifts, bequests, lotteries.
- Which source?
- Residents: worldwide-source gains.
- Conditions
- Proportional tax separate from the progressive scale; the same rate covers disposals of fixed assets and transfers free of charge.
- Duration
- Permanent regime.
- Since when?
- Rate raised by Law 2277 of 2022, applicable since 2023.
- 15% Colombia: single rate on occasional gains for resident individuals
Wealth tax (impuesto al patrimonio)General regime
- Who for?
- Resident individuals and, for their assets in Colombia, the non-residents and non-filing foreign companies covered by the law.
- Which income?
- Net wealth (assets minus debts) as of 1 January.
- Which source?
- Residents: worldwide wealth. Non-residents: wealth held in Colombia (exact scope to be verified in the tax statute).
- Conditions
- Threshold expressed in tax value units (UVT); marginal scale by bracket; partial exclusion of the main residence. Legislative Decree 1474 of 2025, issued under the state of economic emergency, lowered the threshold and raised the rates for 2026: it was suspended on 29 January 2026 and then declared unenforceable (inexequible) (ruling C-079 of 2026). Decrees 173 and 240 of 2026 target legal entities.
- Duration
- Permanent annual tax since Law 2277; the rate for the top bracket was announced as temporary, and its duration remains to be verified.
- Since when?
- Law 2277 of 2022, tax due since 2023.
- from 72,000 Colombia: net worth threshold for the individual wealth tax, expressed in UVT (regime of Law 2277 of 2022)
- 0.5% Colombia: minimum rate of the wealth tax scale (Law 2277 of 2022)
- 1.5% Colombia: top rate of the wealth tax scale (Law 2277 of 2022)
Visa for digital nomads and remote workersSpecial regime
- Who for?
- Foreign nationals working remotely for foreign employers or clients, or digital entrepreneurs.
- Which income?
- No tax advantage: beyond the presence threshold, the holder becomes a resident and is taxable on worldwide income, including income paid by a foreign employer.
- Which source?
- Not applicable (general regime).
- Conditions
- Minimum monthly resources; health insurance; application to the Ministry of Foreign Affairs (resolution 5477 of 2022, article 46).
- Duration
- Maximum duration set by the visa regulations.
- Since when?
- In force since resolution 5477 of 2022.
- up to 2 years Colombia: maximum duration of the visa for digital nomads and remote workers
- about $1,400 Colombia: reference monthly means required of a digital nomad visa applicant
Your company
Corporate income taxGeneral regime
- Who for?
- Domestic companies (incorporated in Colombia or with their place of effective management there) and permanent establishments of foreign entities.
- Which income?
- Taxable profit for the financial year.
- Which source?
- Domestic companies: worldwide-source income; permanent establishments: income attributable to them.
- Conditions
- General rate under article 240; special sector-specific rates and surtaxes not detailed here; dividends to non-residents subject to the rate in article 245.
- Duration
- Permanent regime.
- Since when?
- Rate set by Law 2277 of 2022.
- 35% Colombia: standard corporate income tax rate
Simplified tax regime (SIMPLE)Conditional
- Who for?
- Individuals carrying on a business or professional activity and companies whose shareholders are resident individuals, below an annual gross income ceiling, by election.
- Which income?
- Gross income from the activity.
- Which source?
- Depends on the taxpayer's residence (general regime).
- Conditions
- Single annual tax with bimonthly advance payments, replacing income tax and incorporating the national consumption tax and the consolidated municipal industry and commerce tax; VAT is not included; progressive rates depending on the activity group and income level; ceiling and rates expressed in UVT, revised by Law 2277 of 2022 and then by ruling C-540 of 2023.
- Duration
- By election, as long as the conditions are met.
- Since when?
- Regime created in 2018 (Law 1943), made permanent by Law 2155 of 2021; scale for liberal professions applicable since 2024.
Compare with other countries:Foreign incomeCompany taxationRegimes for new residents
Key figures
- Population52,000,000Verified on Nov 2, 2026
- Flight from Parisabout11 hoursVerified on Nov 2, 2026
Personal taxation
Article 10 of the Colombian tax statute treats as residents individuals who remain in the country, continuously or not, for more than from 183 days3 within a period of three hundred and sixty-five consecutive days.
Because the reference period is rolling rather than calendar-based, a stay spread over two calendar years can establish residence even if neither year exceeds the threshold. This mechanism needs watching by anyone who alternates stays.
The income tax scale for resident individuals is progressive and peaks at 39%4. A Colombian tax resident is taxed on worldwide-source income, which clearly sets Colombia apart from the territorial jurisdictions of the region.
Capital income and occasional gains
Dividends and shareholdings received by foreign companies and entities, as well as by certain individuals, are subject to a special rate set at 20%5 by article 245.
So-called occasional gains — a category that includes, in particular, capital gains on the disposal of assets held beyond a certain period, inheritances and gifts — are taxed at a single rate of 15%6 for resident individuals.
This single rate therefore covers both the sale of an asset and transfer on death, which makes Colombia markedly lighter than France on transfers, and comparable on disposals.
In addition, there is an annual wealth tax (impuesto al patrimonio), made permanent by Law 2277 of 2022. Under article 294-3 of the tax statute, it applies to individuals whose net wealth — assets minus debts — reaches at least from 72,0007 tax value units (UVT) on 1 January, a unit indexed every year. A resident is subject to it on worldwide wealth, a non-resident in principle on assets located in Colombia. The scale is marginal and progressive, with a partial exclusion of the main residence; we do not reproduce the rates, as we have not checked them against an official source.
Corporate income tax is set at 35%8 at the general rate, one of the highest in the region.
Sole proprietors, independent professionals and companies held by resident individuals may, below a gross income ceiling, opt for the simplified tax regime (SIMPLE), created in 2018 and made permanent in 2021. It replaces income tax with a single tax on gross income, depending on the activity group, which incorporates the national consumption tax and the municipal industry and commerce tax; VAT remains payable separately. The ceiling and the rates, expressed in UVT and progressive, are not reproduced here.
One correction to this reading is nevertheless necessary: the treaty concluded between France and Colombia allocates the right to tax and provides mechanisms for eliminating double taxation. A pension, French real estate income or a French-source dividend are not governed by the same rule, and Colombian worldwide taxation applies only after this allocation. The analysis therefore starts from the treaty, income by income.
Residence routes and visas
Colombia has formalised a visa for remote workers, entrepreneurs and digital nomads, provided for by article 46 of the visa regulations.
It is intended for the provision of remote work or teleworking services from Colombia, for a maximum duration of up to 2 years9.
The applicant must show proof of resources, with a reference amount of around about $1,40010 per month. This level, far below that of most European nomad visas, explains part of the country's appeal to this population.
The interaction between this visa and taxation must be understood. Its maximum duration far exceeds the tax residence threshold: a holder who stays in the country becomes a resident, and is then taxable on worldwide income, including income paid by a foreign employer.
This is the point most often overlooked by applicants: the Colombian nomad visa does not come with a favourable tax regime, unlike what some competing schemes offer.
The other visa categories — investor, retiree, work — and their respective resource thresholds do not appear in our extracts: they must be verified with the Ministry of Foreign Affairs.
There is also a residence route through investment, notably in real estate, which grants a permit of longer duration. It targets a different audience from the nomad visa and requires the investment to be registered with the central bank, a condition that overlaps with the repatriation of funds discussed below.
The choice between these routes is not made on the amount required alone: it depends on the intended duration, on the ability to show regular income, and on whether one intends to settle for the long term. A short visa renewed several times often costs more, in paperwork and uncertainty, than a long permit obtained from the outset.
Real estate
Acquisition by a foreign national is free and requires no prior authorisation. Registration of the foreign investment with the central bank is, however, a decisive formality: it determines whether the proceeds of a later resale can be repatriated.
The market is concentrated in Bogotá, Medellín and Cartagena, each with its own dynamics. Medellín has seen strong foreign demand linked to the arrival of remote workers, with noticeable effects on rents in certain neighbourhoods and local tensions over short-term rentals.
Two checks are essential. First, the title deed and its history, in a country where some properties have a complex legal background. Second, the socio-economic stratification, which determines the tariff for household public utilities and is as much a budget item as an indicator of the neighbourhood.
We do not publish registration duties, the property tax (impuesto predial) or the taxation of Colombian rental income: they do not appear in the extracts of the tax statute available to us.
Cost of living
The Colombian cost of living is far below European levels, particularly for services, dining out and labour. It is one of the most favourable gaps among French-speaking expatriation destinations.
We do not publish a typical monthly budget: we have not found an official Colombian series measuring a basket of expenses comparable to that of an expatriate.
Three factors temper this finding. First, imported goods, which are heavily taxed. Then healthcare: the system is of good quality, but enrolment of a foreign national involves procedures, and many take out private coverage. Finally, exchange-rate risk, since income in euros and spending in pesos move independently.
Security, often highlighted, should be treated as a local matter: it varies sharply from one neighbourhood to another within the same city, and it should be assessed at neighbourhood level, not country level.
One last item deserves a provision: altitude and climate shape day-to-day expenses more than people tend to expect. Bogotá, high up and cool all year round, does not have the same energy budget or the same equipment needs as Cartagena, which is tropical and humid, and where air conditioning becomes a permanent expense.
Procedures and timelines
- Count your days over a rolling three-hundred-and-sixty-five-day window, not by calendar year;
- obtain the Colombian tax identification number, which is a prerequisite for banking and property transactions;
- register any foreign investment with the central bank, failing which later repatriation of the funds will be hindered;
- file the visa application that matches your situation, bearing in mind that the nomad visa carries no tax advantage;
- deal with your departure from France according to its own criteria and the applicable tax treaty.
The third point is the costliest one to neglect: the investment is registered when the funds enter the country, and it cannot easily be regularised after the fact.
We do not publish processing times for Colombian visas: we have no official source that is both quantified and dated.
Points to watch
- Colombia taxes residents on their worldwide income: it is not a territorial jurisdiction, unlike several of its neighbours.
- The nomad visa, valid for a maximum of up to 2 years9, leads automatically to tax residence if you stay on, with no preferential regime attached.
- Residence is assessed over a rolling window, not over the calendar year.
- Registering the foreign investment is a condition for repatriating the funds.
- The Colombian passport gives visa-free access to about 13611: no mobility gain for a European national.
Finally, Colombia illustrates a frequent and poorly understood case: a country that is very attractive for its cost of living and the ease of obtaining a residence permit, but whose personal taxation is anything but a haven. For a remote worker who stays there long term, worldwide taxation at Colombian rates may prove heavier than the one they thought they were leaving behind.
Pros & cons
Pros
Very low cost of living, eternal spring in Medellín
Accessible nomad visa, inexpensive property with strong potential
Large community of French-speaking and Spanish-speaking nomads
Cons
Uneven safety depending on the city and neighbourhood
Worldwide taxation from 183 days12 of residence
No tax treaty with France
Safety: choose neighbourhoods carefully
Frequently asked questions
Does Colombia have a nomad visa?
Yes, a visa for remote workers and self-employed people, available to those who can show regular income.
How are residents taxed?
Beyond from 183 days12, Colombia taxes worldwide income; below that, taxation is limited to local income.
Is the cost of living low?
Yes, among the lowest of the major destinations in Latin America.
Banks and accounts
Accounts held in this country
Accept residents of this country
See this country on the tax map
Please note
Sources and verification dates
- 1.
Population : 52,000,000
Verified on Nov 2, 2026
- 2.
Flight from Paris : 11 hours
Verified on Nov 2, 2026
- 3.
Colombia: presence within a three-hundred-and-sixty-five-day period giving rise to tax residency : 183 days
« ARTICULO 10. RESIDENCIA PARA EFECTOS TRIBUTARIOS. Se consideran residentes en Colombia para efectos tributarios las personas naturales que cumplan con cualquiera de las siguientes condiciones: 1. Permanecer continúa o discontinúamente en el país por más de ciento ochenta y tres (183) días calendario incluyendo días de entrada y salida del país, durante un periodo cualquiera de trescientos sesenta y cinco (365) días calendario consecutivos — Estatuto Tributario, art. 10 (modifié par la Ley 1607 de 2012), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 4.
Colombia: top marginal income tax rate for resident individuals : 39%
« ARTICULO 241. TARIFA PARA LAS PERSONAS NATURALES RESIDENTES Y ASIGNACIONES Y DONACIONES MODALES. El impuesto sobre la renta de las personas naturales residentes en el país […] se determinará de acuerdo con la siguiente tabla: — Estatuto Tributario, art. 241 (modifié par la Ley 2010 de 2019, art. 34) : barème progressif en UVT de 0 % (jusqu'à 1 090 UVT) à 39 % (au-delà de 31 000 UVT). »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 5.
Colombia: special rate applicable to dividends and profit shares under article 245 : 20%
« ARTICULO 245. TARIFA ESPECIAL PARA DIVIDENDOS O PARTICIPACIONES RECIBIDOS POR SOCIEDADES Y ENTIDADES EXTRANJERAS Y POR PERSONAS NATURALES NO RESIDENTES. […] La tarifa del impuesto sobre la renta correspondiente a dividendos o participaciones percibidos por sociedades u otras entidades extranjeras sin domicilio principal en el país, por personas naturales sin residencia en Colombia y por sucesiones ilíquidas de causantes que no eran residentes en Colombia será del veinte por ciento (20%). — Estatuto Tributario, art. 245 (modifié par la Ley 2277 de 2022), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 6.
Colombia: single rate on occasional gains for resident individuals : 15%
« ARTICULO 314. PARA PERSONAS NATURALES RESIDENTES. La tarifa única del impuesto correspondiente a las ganancias ocasionales de las personas naturales residentes en el país […] es quince por ciento (15%). ARTICULO 313. […] Fijase en quince por ciento (15%) la tarifa única sobre las ganancias ocasionales de las sociedades — Estatuto Tributario, art. 313 et 314 (modifiés par la Ley 2277 de 2022), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 7.
Colombia: net wealth tax threshold for individuals, based on liquid assets, in UVT (article 294-3 of the Tax Statute) : 72,000
« El artículo 294-3 del Estatuto Tributario (ET) establece que el impuesto al patrimonio se genera […] cuyo valor sea igual o superior a setenta y dos mil (72.000) UVT. »
Dirección de Impuestos y Aduanas Nacionales (DIAN), « Concepto DIAN 011166 (int 1045) del 26 de junio de 2026 »Verified on Nov 2, 2026Verified source
- 8.
Colombia: standard corporate income tax rate : 35%
« ARTÍCULO 240. TARIFA GENERAL PARA PERSONAS JURÍDICAS. La tarifa general del impuesto sobre la renta aplicable a las sociedades nacionales y sus asimiladas, los establecimientos permanentes de entidades del exterior y las personas jurídicas extranjeras con o sin residencia en el país, obligadas a presentar la declaración anual del impuesto sobre la renta y complementarios, será del treinta y cinco por ciento (35%). — Estatuto Tributario, art. 240 (modifié par la Ley 2277 de 2022), compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source
- 9.
Colombia: maximum duration of the visa for digital nomads and remote workers : 2 years
« ARTÍCULO 46. Visa V Nómadas digitales — Alcance: Para prestar servicios de trabajo remoto o teletrabajo, desde Colombia, a través de medios digitales e internet, exclusivamente para empresas extranjeras […] Vigencia: Hasta por dos (2) años. — Resolución 5477 de 2022 (22 de julio) del Ministerio de Relaciones Exteriores, art. 46. »
cancilleria.gov.coVerified on Nov 2, 2026Verified source
- 10.
Colombia: reference monthly means required of a digital nomad visa applicant : $1,400
« 4. En el caso de los solicitantes de Visa V para Nómadas Digitales, Emprendedores y Trabajadores remotos, […] el solicitante deberá demostrar mediante extractos bancarios que cuenta con ingresos mínimos equivalentes a tres (3) Salarios Mínimos Legales Mensuales Vigentes (smlmv). — Resolución 5477 de 2022 del Ministerio de Relaciones Exteriores. Salaire minimum 2026 : 1 750 905 COP → 3 smlmv = 5 252 715 COP par mois. »
cancilleria.gov.coVerified on Nov 2, 2026Verified source
- 11.
Colombian passport: visa-free destinations : 136
« Henley Passport Index — classement des passeports par nombre de destinations accessibles sans visa préalable (données IATA), consulté à la date indiquée. Valeur reprise de l’index de l’ancien site (barème à 227 destinations). »
henleyglobal.comVerified on Nov 2, 2026Verified source
- 12.
colombie.visa-nomade.jours.183 : 183 days
« ARTICULO 10. RESIDENCIA PARA EFECTOS TRIBUTARIOS. […] 1. Permanecer continúa o discontinúamente en el país por más de ciento ochenta y tres (183) días calendario incluyendo días de entrada y salida del país, durante un periodo cualquiera de trescientos sesenta y cinco (365) días calendario consecutivos — Estatuto Tributario, art. 10, compilation juridique de la DIAN. »
normograma.dian.gov.coVerified on Nov 2, 2026Verified source