Indonesia (Bali)
Moving to Indonesia (Bali) in 2026: long-stay visas and a low cost of living
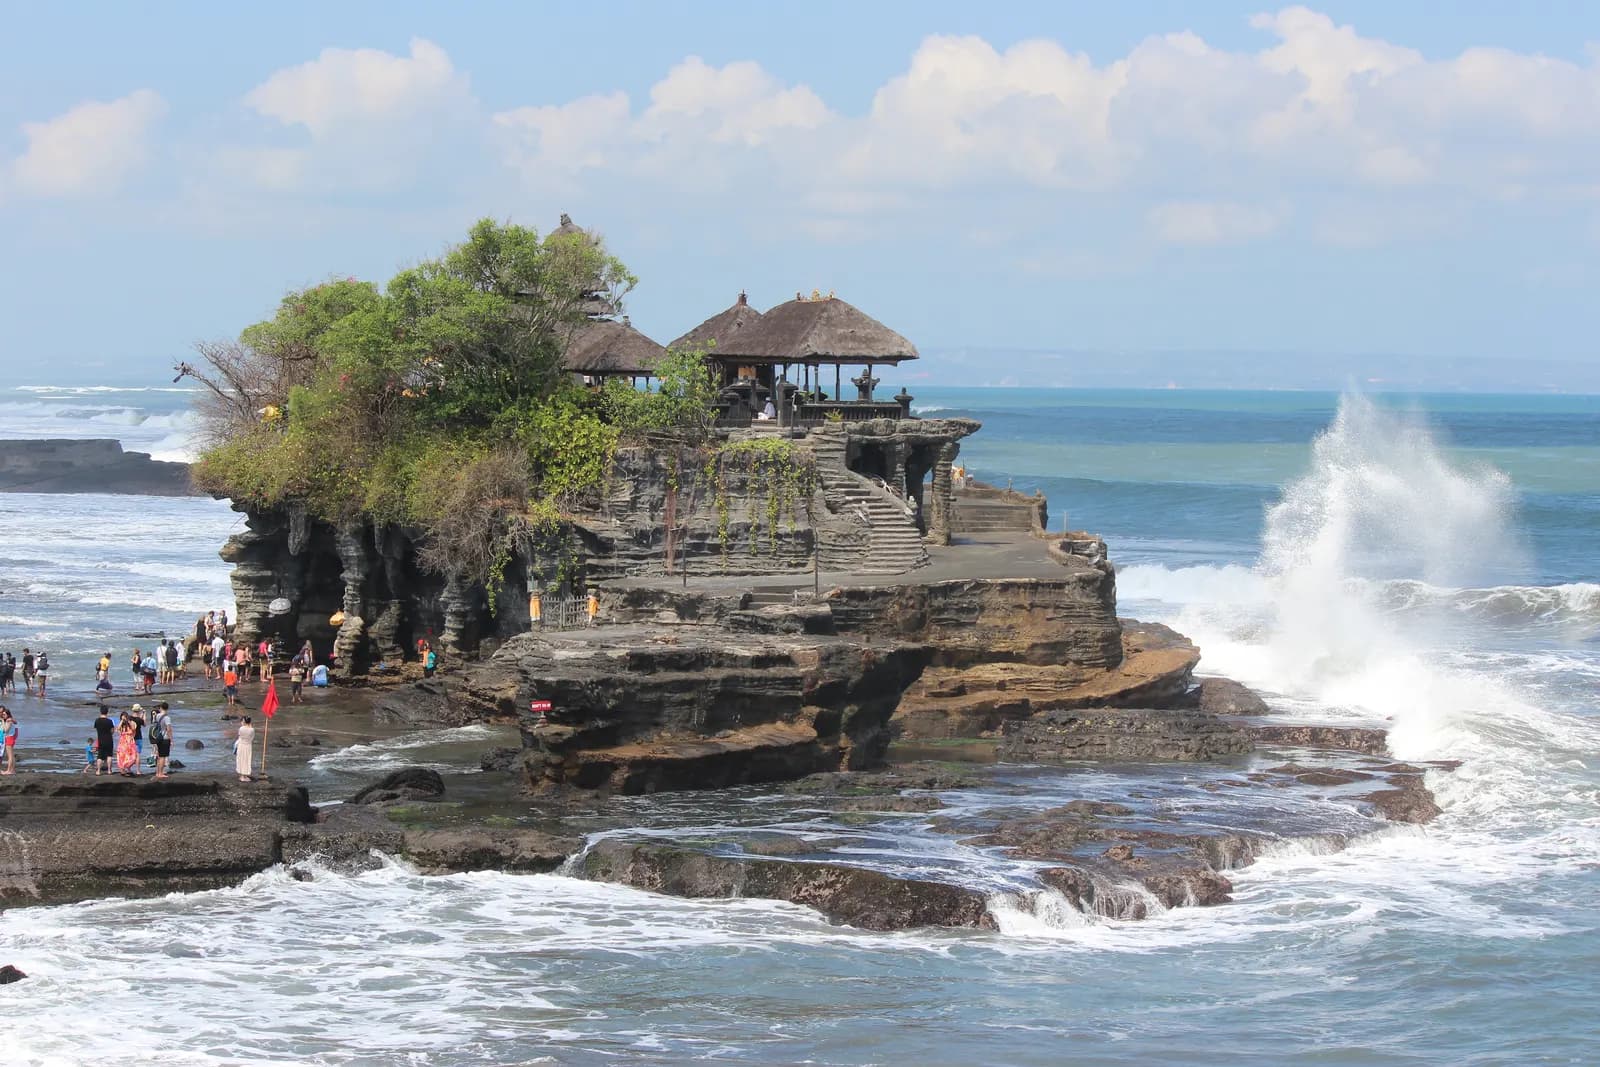
Bali is one of the world's digital nomad capitals: a very low cost of living, an international community and a tropical setting. Indonesia has developed long-stay visas (nomad, Second Home) to attract this population.
- Capital
- Jakarta
- Currency
- IDR
- Region
- Asia
Tax regimes at a glance
Each regime answers the same questions. A zero rate applies only to the income, person and period stated.
Your personal taxation
Personal income tax: general regimeGeneral regime
- Who for?
- Tax residents: a person domiciled in Indonesia, present beyond the day threshold over the relevant rolling period, or present during the year with the intention of residing there; any part of a day counts as a full day.
- Which income?
- Employment income, investment income and other income under the five-bracket progressive scale of the 2021 Tax Harmonisation Law; dividends paid to a resident are subject to a final withholding tax, and are exempt if reinvested in Indonesia under the conditions and for the period set by law.
- Which source?
- Residents: worldwide income. Non-residents: Indonesian-source income.
- Conditions
- The France–Indonesia tax treaty resolves cases of dual residence; holding a given visa does not prevent a person from becoming a tax resident.
- Duration
- Permanent regime.
- Since when?
- Scale applicable since 2022; residence criteria clarified by Regulation PER-23/PJ/2025.
- 183 days Indonesia: length of stay that confers tax resident status (PER-23/PJ/2025)
- 5% Indonesia: first bracket of the income tax scale (UU HPP)
- 15% Indonesia: second bracket of the income tax scale (UU HPP)
- 25% Indonesia: third bracket of the income tax scale (UU HPP)
- 30% Indonesia: fourth bracket of the income tax scale (UU HPP)
- 35% Indonesia: top bracket of the income tax scale (UU HPP)
- 10% Indonesia: final tax on dividends paid to a resident individual
Territorial taxation of qualified foreigners who have become residentsTemporary
- Who for?
- Foreign nationals who have become Indonesian tax residents and hold specified expertise: employees in certain positions defined by regulation, and foreign researchers.
- Which income?
- All income: only income received or earned in Indonesia is taxed.
- Which source?
- Indonesian-source income only; foreign-source income is outside the scope during the period.
- Conditions
- Expertise recognised under the regulatory list; the benefit is excluded if the person relies on a tax treaty (a choice between the two). Legal basis: Article 4 ayat (1a) of the Income Tax Law, introduced by the 2020 Cipta Kerja Law, and Regulation PMK 18/PMK.03/2021.
- Duration
- A limited number of tax years, counted from the acquisition of tax residence.
- Since when?
- Applicable since the 2020 Cipta Kerja Law and its 2021 implementing regulation.
- 4 years Indonesia: duration of taxation limited to Indonesian-source income for qualified foreigners who have become residents
Final tax on the turnover of sole proprietors (UMKM)Conditional
- Who for?
- Individuals carrying on a commercial or professional activity whose annual turnover remains below the statutory ceiling.
- Which income?
- Gross turnover of the business, taxed by a final withholding tax instead of the progressive scale; an initial annual portion of turnover is not taxed.
- Which source?
- The ceiling is assessed on total turnover, including foreign-source turnover; the turnover of spouses and of their single-member companies is aggregated.
- Conditions
- The turnover ceiling for the year must be respected; above it, the general regime applies again.
- Duration
- No time limit for individuals as long as the criteria are met, under Regulation PP 20/2026; taxpayers already under the regime before this regulation keep their current period.
- Since when?
- Regulation PP 20/2026 in force since 22 April 2026, amending PP 55/2022; text of the regulation to be confirmed on the official legal database.
- 0.5% Indonesia: final tax rate on turnover for micro and small businesses (PP 20/2026)
- up to IDR 4,800,000,000 Indonesia: annual turnover ceiling for the final tax on micro and small businesses
- IDR 500,000,000 Indonesia: annual portion of turnover not taxed for individual entrepreneurs subject to the final tax
Second Home Visa (second residence visa)Special regime
- Who for?
- Foreigners with substantial financial means, and their families.
- Which income?
- No tax benefit of its own: it is a residence permit. According to the Directorate General of Taxes, holding it makes the holder an Indonesian tax resident, the visa's period of validity establishing the intention to reside.
- Which source?
- That of the general regime (worldwide income), unless the regime for qualified foreigners applies.
- Conditions
- Proof of minimum funds, in the foreigner's name or that of a guarantor, or proof of property ownership in Indonesia; the permit does not authorise work for an Indonesian employer or Indonesian clients.
- Duration
- Two possible lengths of stay.
- Since when?
- Rules published by the Directorate General of Immigration in 2022; the version in force in 2026 is not confirmed on the immigration website.
- from IDR 2,000,000,000 Indonesia: minimum funds required for the second home visa (Second Home Visa)
- 5 years Indonesia: short-stay option under the Second Home Visa
- up to 10 years Indonesia: maximum length of stay under the Second Home Visa
Your company
Corporate income tax: standard rateGeneral regime
- Who for?
- Resident companies and permanent establishments of foreign companies.
- Which income?
- Taxable profit for the financial year.
- Which source?
- Resident company: worldwide profits; permanent establishment: profits attributable to Indonesia.
- Conditions
- Reductions specific to small companies and sector incentives not verified here.
- Duration
- Permanent regime.
- Since when?
- Rate applicable since the 2022 financial year (Tax Harmonisation Law).
- 22% Indonesia: tax rate on the profits of resident companies
Final tax on the turnover of small entities (UMKM)Conditional
- Who for?
- Single-member companies (perseroan perorangan) and cooperatives below the turnover ceiling. CVs, firms, limited liability companies (PT) and newly registered village enterprises are excluded and are subject to the standard rate.
- Which income?
- Gross turnover, taxed by a final withholding tax instead of tax on profits.
- Which source?
- All of the entity's turnover.
- Conditions
- The annual turnover ceiling must be respected; entities already under the regime before Regulation PP 20/2026 keep it until the end of their period.
- Duration
- No limit for single-member companies as long as the criteria are met; the duration applicable to cooperatives has not been verified.
- Since when?
- Regulation PP 20/2026 in force since 22 April 2026.
- 0.5% Indonesia: final tax rate on turnover for micro and small businesses (PP 20/2026)
- up to IDR 4,800,000,000 Indonesia: annual turnover ceiling for the final tax on micro and small businesses
Compare with other countries:Foreign incomeCompany taxationRegimes for new residents
Key figures
- Population275,000,000Verified on Nov 2, 2026
- Flight from Parisabout16 hoursVerified on Nov 2, 2026
Personal taxation
The Indonesian Directorate General of Taxes clarified the definition of tax resident in a 2025 regulation. An individual is resident if they have their domicile in Indonesia, stay there for more than 183 days3 within a twelve-month period, or, during a tax year, stay there with the intention of residing.
The same text sets out the method of calculation: the length of stay is assessed on a continuous or split basis, and any part of a day counts as a full day. This rule is strict and works against taxpayers who make frequent trips back and forth.
This is the point that remote workers based in Bali most often underestimate. A stay of more than more than 183 days4 within twelve months entails Indonesian tax residence, whatever the visa held and wherever the income comes from.
An exception applies to certain qualified foreigners. Since 2020 (Job Creation Law, Regulation PMK 18/PMK.03/2021), a foreigner who has become a tax resident and holds recognised expertise — an employee in one of the positions defined by regulation, or a researcher — is taxed only on Indonesian-source income for 4 years5, counted in tax years, provided they give up the benefit of a tax treaty.
The tax scale
The scale introduced by the 2021 Tax Harmonisation Law has five brackets. It starts at 5%6, rises to 15%7, then to 25%8, then to 30%9, and reaches 35%10 in the top bracket.
Indonesia is therefore not a low-tax country for high earners: its top marginal rate is comparable to that of many European states. The image of a Balinese tax haven does not survive a reading of the scale.
We do not publish the thresholds of each of these brackets in euros: the statutory amounts are denominated in Indonesian rupiah and their value in euros varies with the exchange rate. They must be converted at the date of the calculation.
Companies and dividends
Tax on the profits of resident companies and permanent establishments has been set at 22%11 since the 2022 financial year.
Small businesses fall under the UMKM regime: a final tax of 0.5%12 on gross turnover replaces tax on profit, for annual turnover ranging up to IDR 4,800,000,00013, of which the first IDR 500,000,00014 is not taxed for a sole proprietor. According to the Directorate General of Taxes, Regulation PP 20/2026, in force since 22 April 2026, removes any time limit for individuals and single-member companies, but excludes newly registered PTs and CVs.
Dividends paid to a resident individual are subject to a final withholding tax of at most 10%15. Since the 2020 Job Creation Law, dividends reinvested in Indonesia for three years are exempt.
For a French national, the rule remains: the Indonesian connection has an effect only after an actual transfer of residence, and the France–Indonesia tax treaty determines the allocation of taxing rights in cases of dual residence.
Residence routes and visas
Indonesia has substantially overhauled its immigration law in recent years, multiplying the visa categories intended for investors, retirees and remote workers.
The so-called second home visa, intended for foreigners with substantial financial means, and investor visas coexist with more conventional permits tied to employment or marriage. A scheme for remote workers has also been announced and then clarified in stages.
Unless a dated indication is given below, we do not publish the financial thresholds, durations or conditions of these visas: they have been amended several times and, in their current version, do not appear in the official sources we were able to consult and verify. They must be established with the Directorate General of Immigration before any project is undertaken.
The second home visa does, however, have an established tax effect: according to the Directorate General of Taxes, its holder becomes an Indonesian tax resident. The 2022 rules required funds from IDR 2,000,000,00016, or a property in Indonesia, for a stay of 5 years17 or up to 10 years18; their current version remains to be confirmed.
This instability is in itself a fact to bear in mind. Conditions announced by the press or by intermediaries have often preceded their actual implementation by several months, and some have been changed before even being applied.
One point, however, is constant and decisive: working for an Indonesian employer or Indonesian clients requires a work permit, which the visas intended for wealthy foreigners or visitors do not include. Carrying on a locally paid activity without the appropriate permit exposes the person to penalties and deportation.
The gap between the practice observed in Bali and the applicable law is real, and checks have tightened. Building a project on de facto tolerance is a gamble, not a strategy.
Real estate
Indonesian land law reserves full ownership to nationals. A foreigner can hold only a right of use or a right to build, titles that are distinct from ownership and granted for limited, renewable periods.
This rule is constitutional in principle and cannot be circumvented. Arrangements under which a property is acquired through an Indonesian nominee are unlawful: Indonesian case law penalises them, and the foreigner then loses everything, with no effective recourse.
This is the most serious and most frequent risk in Bali projects, and it is systematically played down by intermediaries. A real estate investment in Indonesia is structured exclusively through a properly granted right of use or through a foreign investment company set up for that purpose.
The Bali market is moreover highly dependent on tourism, and its liquidity varies considerably from one area to another. Questions of urban planning, access to water and building compliance have become sensitive there, as the local authorities have begun checks on undeclared accommodation.
We do not publish the statutory durations of rights of use, transfer duties, or the taxation of Indonesian rental income: they do not appear in our extracts.
Cost of living
The cost of living in Indonesia is far below European levels, and it is the main driver of relocation to Bali. The gap is particularly marked for services, labour and local food.
We do not publish a typical monthly budget: we have not found an official Indonesian series measuring a basket of expenses comparable to that of an expatriate.
The currency is the Indonesian rupiah, whose value against the euro fluctuates. Income received in euros benefits from this difference, but assets built up locally are exposed to it.
Three items shape a budget. The first is housing in the sought-after areas of Bali, where rents have risen sharply because of foreign demand and can no longer be compared with the rest of the country. The second is healthcare, as local facilities often require evacuation to Singapore for major procedures. The third is international schooling, which is expensive and concentrated in a few places.
Two quality-of-life constraints are hard to gauge from a distance: road congestion in southern Bali, which considerably lengthens journeys, and pressure on water supply and waste treatment, which have become a local public issue. They weigh on daily life more than on the budget.
Procedures and timeframes
- Check the current conditions of the intended visa with the Directorate General of Immigration, as the rules have changed a great deal;
- count days of presence precisely, since any part of a day counts as a full day;
- never use a nominee to acquire property: the arrangement is unlawful and the loss is total;
- make sure that any paid activity carried out locally is covered by a work permit;
- deal with your departure from France according to your own circumstances and under the France–Indonesia tax treaty.
The second point deserves particular attention. The Indonesian counting rule is stricter than most equivalent rules: a one-day round trip counts as a full day of presence, which means the threshold is crossed faster than an intuitive calculation would suggest.
We do not publish processing times: we have no official Indonesian source that is both quantified and dated.
Points to watch
- The top marginal rate reaches 35%10: Indonesia is not a low-tax destination for a high income.
- The 183 days3 threshold is assessed including parts of a day, each part counting as a full day.
- Full ownership of land is reserved for Indonesian nationals: a foreigner holds only a right of use.
- Nominee arrangements are unlawful and expose the buyer to a total loss of the property.
- Visa conditions have been amended several times: any documentation must be dated and verified.
Finally, Bali is the destination where the gap between the story and the law is the widest of all those covered by this site. The cost of living and the quality of life are real; legal certainty, however, is weak for a foreigner, both on land and on the right to work. A serious Indonesian project is built with a local notary and a local tax adviser, accepting a right of use rather than ownership, and counting one's days. Those who proceed otherwise expose themselves to losses that neither the climate nor the cost of living can offset.
Advantages & disadvantages
Pros
Global capital of digital nomads (Bali): very low costs, huge community
One-year E33G nomad visa, foreign income not taxed outside tax residence
Exceptional tropical setting and way of life
Cons
Foreigners cannot own land (right of use/leasehold only)
Limited local healthcare, evacuation to Singapore for serious cases
Stricter monitoring of foreign income since 2026
The E33G visa prohibits any work for Indonesian clients
Frequently asked questions
Which long-stay visas exist in Indonesia?
A digital nomad visa and a Second Home visa (backed by a deposit or a property) allow extended stays.
Does taxation affect nomads?
Tax residence beyond 183 days3 may lead to local taxation; this should be planned with an adviser.
Is the cost of living low?
Yes, among the lowest of the nomad destinations.
Banks and accounts
Accounts held in this country
Accept residents of this country
See this country on the tax map
Please note
Sources and verification dates
- 1.
Population : 275,000,000
Verified on Nov 2, 2026
- 2.
Flight from Paris : 16 hours
Verified on Nov 2, 2026
- 3.
Indonesia: length of stay that confers tax resident status (PER-23/PJ/2025) : 183 days
« berada di Indonesia lebih dari 183 (seratus delapan puluh tiga) hari dalam jangka waktu 12 (dua belas) bulan »
pajak.go.idVerified on Nov 2, 2026Verified source
- 4.
Indonesia: presence threshold above which a remote worker becomes a tax resident : 183 days
« berada di Indonesia lebih dari 183 (seratus delapan puluh tiga) hari dalam jangka waktu 12 (dua belas) bulan »
pajak.go.idVerified on Nov 2, 2026Verified source
- 5.
Indonesia: duration of taxation limited to Indonesian-source income for qualified foreigners who have become residents : 4 years
« berlaku selama empat tahun pajak yang dihitung sejak WNA menjadi SPDN »
Direktorat Jenderal Pajak (article d’un agent publié sur pajak.go.id, 3 septembre 2021), « WNA Hanya Dipajaki atas Penghasilan dari Indonesia, Kok Bisa? »Verified on Nov 2, 2026Verified source
- 6.
Indonesia: first bracket of the income tax scale (UU HPP) : 5%
« Untuk lapisan I (rentang PKP: 0 sampai dengan Rp60 juta) tarif pajaknya 5% »
pajak.go.idVerified on Nov 2, 2026Verified source
- 7.
Indonesia: second bracket of the income tax scale (UU HPP) : 15%
« Untuk lapisan II (rentang PKP: lebih dari Rp60 juta sampai dengan Rp250 juta) tarif pajaknya 15% »
pajak.go.idVerified on Nov 2, 2026Verified source
- 8.
Indonesia: third bracket of the income tax scale (UU HPP) : 25%
« Untuk lapisan III (rentang PKP: lebih dari Rp250 juta sampai dengan Rp500 juta) tarif pajaknya 25%. »
pajak.go.idVerified on Nov 2, 2026Verified source
- 9.
Indonesia: fourth bracket of the income tax scale (UU HPP) : 30%
« Untuk lapisan IV (rentang PKP: lebih dari Rp500 juta sampai dengan Rp5 miliar) tarif pajaknya 30% »
pajak.go.idVerified on Nov 2, 2026Verified source
- 10.
Indonesia: top bracket of the income tax scale (UU HPP) : 35%
« Untuk lapisan V (rentang PKP: lebih dari Rp5 miliar) tarif pajaknya 35% »
pajak.go.idVerified on Nov 2, 2026Verified source
- 11.
Indonesia: tax rate on the profits of resident companies : 22%
« Disebutkan dalam Pasal 17 ayat (1) bagian b UU No. 7 Tahun 2021 tentang Harmonisasi Peraturan Perpajakan (HPP), tarif pajak yang diterapkan atas Penghasilan Kena Pajak bagi Wajib Pajak Badan dalam negeri dan bentuk usaha tetap sebesar 22% mulai berlaku pada tahun pajak 2022. »
pajak.go.idVerified on Nov 2, 2026Verified source
- 12.
Indonesia: final tax rate on turnover for micro and small businesses (PP 20/2026) : 0.5%
« Wajib Pajak dengan omzet melebihi Rp4,8 Miliar tidak dapat menggunakan tarif PPh Final 0,5%. »
Direktorat Jenderal Pajak (article d’opinion d’un agent publié sur pajak.go.id), « PP 20/2026: Tarif PPh 0,5% bagi UMKM Orang Pribadi Berlaku Selamanya »Verified on Nov 2, 2026Verified source
- 13.
Indonesia: annual turnover ceiling for the final tax on micro and small businesses : IDR 4,800,000,000
« Wajib Pajak dengan omzet melebihi Rp4,8 Miliar tidak dapat menggunakan tarif PPh Final 0,5%. »
Direktorat Jenderal Pajak (article d’opinion d’un agent publié sur pajak.go.id), « PP 20/2026: Tarif PPh 0,5% bagi UMKM Orang Pribadi Berlaku Selamanya »Verified on Nov 2, 2026Verified source
- 14.
Indonesia: annual portion of turnover not taxed for individual entrepreneurs subject to the final tax : IDR 500,000,000
« Omzet usaha hingga Rp500 Juta pertama yang diperoleh Wajib Pajak Orang Pribadi »
Direktorat Jenderal Pajak (article d’opinion d’un agent publié sur pajak.go.id), « PP 20/2026: Tarif PPh 0,5% bagi UMKM Orang Pribadi Berlaku Selamanya »Verified on Nov 2, 2026Verified source
- 15.
Indonesia: final tax on dividends paid to a resident individual : 10%
« Tarif yang dikenakan atas penghasilan berupa dividen yang dibagikan kepada Wajib Pajak orang pribadi dalam negeri adalah paling tinggi sebesar 10% (sepuluh persen) dan bersifat final. »
pajak.go.idVerified on Nov 2, 2026Verified source
- 16.
Indonesia: minimum funds required for the second home visa (Second Home Visa) : IDR 2,000,000,000
« dengan nilai minimal dua miliar rupiah atau sekitar US$130.000,00 »
Direktorat Jenderal Pajak (article du 22 novembre 2022), « Pajak untuk Pemegang Second Home Visa »Verified on Nov 2, 2026Verified source
- 17.
Indonesia: short-stay option under the Second Home Visa : 5 years
« dapat tinggal selama lima atau sepuluh tahun »
Direktorat Jenderal Pajak (article du 22 novembre 2022), « Pajak untuk Pemegang Second Home Visa »Verified on Nov 2, 2026Verified source
- 18.
Indonesia: maximum length of stay under the Second Home Visa : 10 years
« dapat tinggal selama lima atau sepuluh tahun »
Direktorat Jenderal Pajak (article du 22 novembre 2022), « Pajak untuk Pemegang Second Home Visa »Verified on Nov 2, 2026Verified source