International mobility news

Greece

Moving to Greece in 2026: 7% for retirees, Golden Visa and taxation

Greece has established itself as one of the most attractive destinations in Europe for retirees, thanks to a flat 7% regime on foreign pensions for 15 years. A moderate cost of living, a Mediterranean setting and an accessible Golden Visa complete the picture, at the price of a slow administration and an uneven public healthcare system.

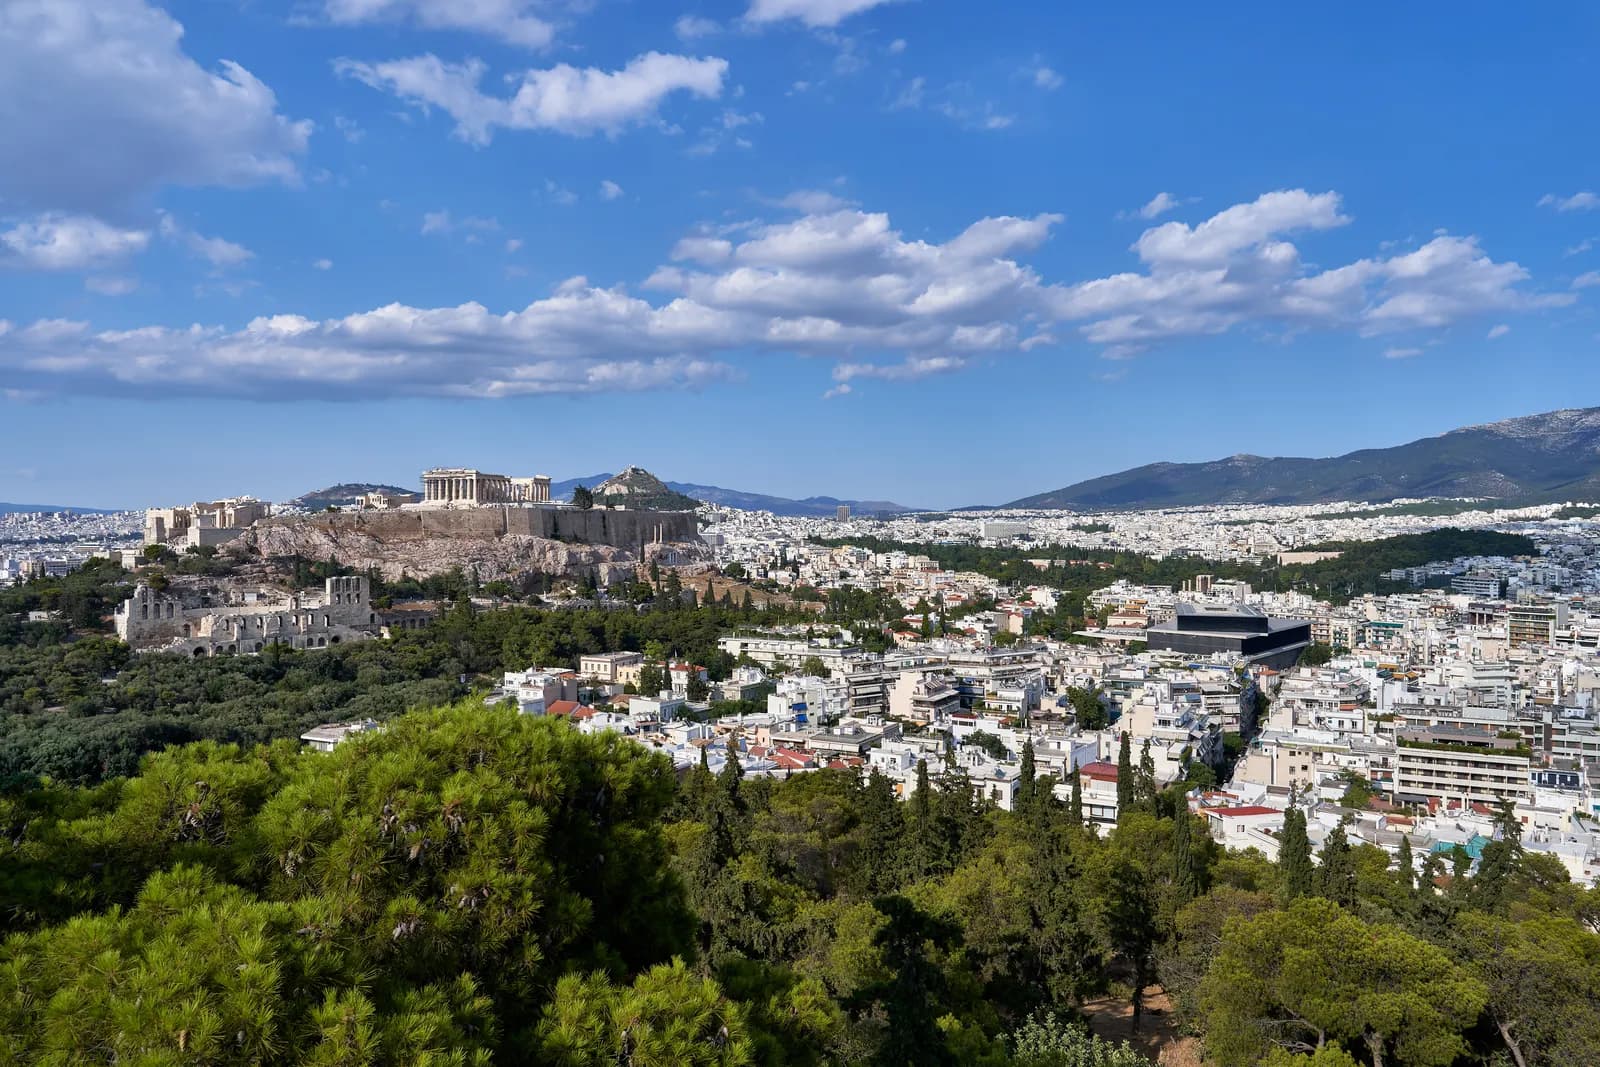
View of Greece
Photo: George E. Koronaios — Wikimedia Commons (CC BY-SA)
Capital
Athens
Currency
EUR
Region
Europe
Memberships
European Union, Schengen Area, Eurozone

Tax regimes at a glance

Each regime answers the same questions. A zero rate applies only to the income, person and period stated.

Your personal taxation

  • Income tax: general regime for residentsGeneral regime

    Who for?
    Individuals who have their permanent or main home, their habitual abode or the centre of their vital interests in Greece, or who stay there beyond the presence threshold over a reference period.
    Which income?
    Salaries and pensions taxed at a progressive scale revised from 2026; dividends subject to a final withholding tax; capital gains on the sale of securities taxed at a proportional rate.
    Which source?
    Residents: worldwide income. Non-residents: Greek-source income.
    Conditions
    Alternative residence criteria. Tax reduction for employees and pensioners, decreasing with income (not detailed here).
    Duration
    Permanent regime.
    Since when?
    Scale applicable to income from 2026.
    • more than 183 days Greece: annual presence above which tax residency is acquired
    • 9% Greece: rate of the first bracket of the salaries and pensions scale (from 2026)
    • 44% Greece: income tax 2026 (art. 15 §1 ΚΦΕ, salaries and pensions), rate of the 6th bracket
    • 5% Greece: withholding tax on dividends
    • 15% Greece: tax rate on capital gains from disposals

    Official source · minfin.gov.gr

  • Article 5Α ΚΦΕ: flat tax for high-net-worth investorsSpecial regime

    Who for?
    Individuals who transfer their tax residence to Greece without having been resident there during almost all of the reference years, and who invest in Greece (real estate, businesses, securities or company shares) at least the amount required by law; possible extension to family members.
    Which income?
    All foreign-source income, covered by a flat annual tax regardless of its amount; Greek-source income remains subject to the general regime. Exemption from inheritance and gift tax on assets located abroad.
    Which source?
    Foreign-source income at the flat rate; Greek-source income at the standard scale.
    Conditions
    Investment made or committed within the legal deadline; application to the tax authority; annual payment of the flat tax. The application and payment deadlines were amended by Law 5246/2025 (to be checked for each year).
    Duration
    Maximum duration counted from the year the application is filed.
    Since when?
    In force; extension to family members and inheritance exemption amended by Law 5222/2025 from 28 July 2025.
    • €100,000 Greece, regime for high-net-worth individuals: annual flat tax on foreign income
    • €20,000 Greece, Article 5Α regime: annual flat tax per attached family member
    • €500,000 Greece, regime for high-net-worth individuals: investment required in Greece
    • up to 15 years Greece, Article 5Α regime: maximum duration of the flat-rate regime
    • from 7 years Greece, Article 5Α regime: years of non-tax residence required over the reference period
    • 8 years Greece, Article 5Α regime: reference period for the non-residence condition

    Official source · aade.gr

  • Article 5Β ΚΦΕ: retirees coming from abroadSpecial regime

    Who for?
    Holders of foreign pensions who transfer their tax residence to Greece from a State linked to Greece by an agreement on administrative cooperation in tax matters, without having been resident there during most of the reference years.
    Which income?
    All foreign-source income, at a flat annual rate; Greek-source income remains subject to the general regime.
    Which source?
    Foreign-source income only.
    Conditions
    Application to the tax authority; annual payment of the tax. Cannot be combined with Articles 5Α and 5Γ.
    Duration
    Maximum duration in tax years.
    Since when?
    In force; filing and payment arrangements amended by Law 5246/2025.
    • 7% Greece, regime for foreign retirees: flat rate on foreign-source income
    • 15 years Greece, regime for foreign retirees: period of application
    • from 5 years Greece, Article 5Β regime (pensions): years of non-tax residence required over the reference period
    • 6 years Greece, Article 5Β and 5Γ regimes: reference period for the non-residence condition

    Official source · aade.gr

  • Article 5Γ ΚΦΕ: employees and self-employed people settling in GreeceSpecial regime

    Who for?
    Individuals who transfer their tax residence to Greece to take up salaried employment or a self-employed activity there, without having been resident there during most of the reference years.
    Which income?
    Income from salaries and from self-employed activity carried out in Greece: exemption of part of the taxable income.
    Which source?
    Greek-source income from work.
    Conditions
    Employment or activity in Greece; maintenance of tax residence; application to the tax authority.
    Duration
    Limited number of tax years starting from the year of the transfer.
    Since when?
    In force.
    • 50% Greece, workers relocating from abroad: share of employment income exempt from tax
    • 7 years Greece, workers relocating from abroad: duration of the partial exemption
    • from 5 years Greece, Article 5Γ regime (assets): years of tax non-residence required over the reference period
    • 6 years Greece, Article 5Β and 5Γ regimes: reference period for the non-residence condition

    Official source · aade.gr

Your company

  • Corporate income taxGeneral regime

    Who for?
    Companies and legal entities resident in Greece, and permanent establishments of non-residents.
    Which income?
    Taxable profit for the financial year; distributed dividends subject to withholding tax at the level of the shareholder.
    Which source?
    Resident companies: worldwide profit. Non-residents: profits of the permanent establishment.
    Conditions
    Standard rate; sector-specific regimes (notably maritime) not covered.
    Duration
    Permanent regime.
    Since when?
    In force.
    • 22% Greece: tax rate on the profits of legal entities
    • 5% Greece: withholding tax on dividends

    Official source · minfin.gov.gr

Compare with other countries:Foreign incomeCompany taxationRegimes for new residents

Key figures

  • Population10,400,000Verified on Nov 2, 2026
  • Flight from Parisabout3 hoursVerified on Nov 2, 2026

Taxation of individuals

A person is a Greek tax resident if they have their permanent or main home, their habitual abode or the centre of their vital interests there, or if they stay there more than 183 days3 within a twelve-month period. The criteria are alternative: physical presence is only one of them.

The scale for salaries and pensions is progressive. Its first bracket is taxed at 9%4. In the scale revised from 2026, the top marginal rate is 44%5, on taxable income above €60,0006.

Investment income and transfers of wealth

Dividends are subject to a withholding tax of 5%7, one of the lowest rates in the European Union. Capital gains on the sale of assets are taxed at 15%8.

Inheritance tax in the direct line — spouse, first-degree descendants — follows a scale with brackets whose top rate is 10%9 above the last threshold, after an initial exempt tier. This is a point that clearly sets Greece apart from France for the transfer of family wealth.

Corporate income tax is set at 22%10.

Three attraction regimes, three audiences

Greece does not have one regime for newcomers, it has three, and confusing them is the most frequent mistake.

  • Foreign retirees: a flat rate of 7%11 on all foreign-source income, for 15 years12, provided they have not been Greek tax residents for five of the six preceding years;
  • high-net-worth individuals: a flat annual tax of €100,00013 covering foreign-source income, conditional on an investment in Greece of at least €500,00014, and reserved for those who have not been Greek residents for seven of the eight preceding years; the flat tax is capped at up to 15 years15 and may be extended, by option, to the foreign income of family members, at a cost of €20,00016 per person per year;
  • working-age people coming to work in Greece: an exemption covering 50%17 of employment income, for 7 years18.

The prior-residence conditions differ from one regime to another — five years out of six, seven years out of eight — as does the income covered. The choice is therefore made upfront, based on the nature of the income, and it cannot be reversed from one year to the next.

Residence routes and visas

A French national needs no permit: freedom of movement applies. The following sections concern third-country nationals.

The investor residence permit

The permanent investor residence permit — commonly called the golden visa — is governed by Article 100 of the Migration Code, Law 5038/2023. Article 64 of Law 5100/2024 raised its thresholds and, above all, made them regional.

In the region of Attica, the district of Thessaloniki, Mykonos, Santorini and islands with a population above more than 3,10019, the threshold rose from from €500,00020 to €800,00021. In the rest of the country, it rose from from €250,00022 to from €400,00023.

The island criterion is based on the island's population, not on its fame: a small, highly touristic island may fall under the lower threshold.

The permit confers a right of residence, which can be extended to the family. It carries neither tax residence nor nationality: these are three separate questions, governed by three distinct sets of rules.

The reduced threshold mentioned for buildings undergoing a change of use or listed buildings, as well as the minimum surface area required for certain properties, do not appear on the government page consulted on 26 September 2026: we do not give figures for them.

Real estate

The Greek market has been one of the most sought-after in Southern Europe over the past decade, driven by the recovery after the debt crisis, by tourism and by the investment programme itself. The reform of the thresholds is a direct consequence: it aims to steer foreign demand away from areas where it weighs on prices.

Acquisition by a non-resident is not subject to general authorisation, except in border areas and certain islands, where a specific regime applies. The Greek tax number — the AFM — is a prerequisite for any transaction, as it is for opening an account.

Restrictions on use have also been introduced for properties acquired through the investor permit route, notably as regards short-term rental. They change the rental equation of an investment designed for yield, and fall under separate texts from those that set the thresholds.

We do not publish transfer taxes, the ENFIA property tax, or the taxation of rental income. At the time of writing, we were unable to consult an official page giving these scales in a clear and dated form.

Cost of living

The general price level remains below the eurozone average, with a marked gap between Athens and Thessaloniki on the one hand, and the highly touristic islands on the other, where the season drives prices far more than the local economy does.

We do not publish a typical monthly budget for Greece: we found no official series measuring a basket of expenses comparable to that of an expatriate. The figures in circulation come from self-reported databases that cannot be verified.

Two items deserve particular attention in an expatriate's budget. First, heating, the cost of which is often underestimated for a country reputed to be warm, as older homes are poorly insulated. Second, private healthcare, which many foreign residents take out in addition to the public system.

Procedures and timelines

  1. Obtain the AFM, the Greek tax number, a prerequisite for opening an account, signing a lease and any acquisition;
  2. open a Greek bank account, needed to pay local taxes and utility charges;
  3. for a third-country national, put together the residence permit file, having first determined the applicable zone if the chosen route is investment;
  4. register as a tax resident, then, where applicable, file the application for admission to the relevant attraction regime — retirees, high-net-worth individuals or working-age people — checking the prior-residence condition specific to each;
  5. keep proof of prior non-residence: it conditions access to all three regimes, and it is established by documents gathered before departure.

Law 5246/2025 has also changed the timetable of the regimes under Articles 5Α and 5Β. According to the specialist press, the deadline for filing the application for admission disappears and payment of the flat tax is postponed to the end of the year. We have not read these provisions in the official text: the timetable applicable to a file should be checked with the tax authority (AADE) before filing.

We do not publish processing times. Those of the Greek immigration services and tax authority vary according to the office concerned and the period, and we have no official, dated source with figures.

Points of caution

  • The three attraction regimes cannot be combined and their prior-residence conditions differ. Choosing the wrong one, or filing too late, closes off access to the others.
  • The investor permit does not make you a tax resident, and tax residence is not obtained through a permit: the flat-tax regime requires a separate procedure, with its own evidence.
  • The restrictions on short-term rental of properties acquired through the investment route must be checked before any yield calculation.
  • The Greek passport gives visa-free access to about 19124, but naturalisation is subject to its own conditions, unrelated to the duration of an investor permit.
  • Departure from France is assessed under French criteria and the applicable tax treaty. Registering with the Greek tax authority is not enough to establish that the household and the centre of economic interests have left France.

Finally, Greece has changed its investment thresholds, its tax scale and the rules on the use of the properties concerned within the space of two budget years. A project built over fifteen years rests on texts whose pace of revision is much shorter.

Advantages & disadvantages

Pros

  • 7%11 flat tax for foreign retirees for 15 years12

  • Golden Visa from from €400,00023 (areas outside the major cities)

  • One of the lowest costs of living in Western Europe

  • Exceptional Mediterranean setting and climate

Cons

  • Heavy, slow administration

  • Non-dom flat tax (€100,00013/year) only worthwhile for the very wealthy

  • Uneven public hospitals — private care recommended

  • Golden Visa thresholds raised to €800,00021 in sought-after areas

Frequently asked questions

How does the 7% retiree regime work in Greece?

Foreign retirees who transfer their tax residence to Greece are taxed at a flat rate of 7%11 on all their foreign-source income, pension included, for 15 years12. You must come from a country that has a tax treaty with Greece, such as France.

What is the minimum amount for the Greek Golden Visa?

from €400,00023 in the least sought-after areas, but €800,00021 in Athens, Thessaloniki and on the most popular islands.

Is the Greek non-dom flat tax worth it?

The flat tax of €100,00013/year on foreign income (requiring an investment of €500,00014) is only worthwhile for very high foreign income. Below that level, the retiree regime or ordinary taxation is more advantageous.

Do you have to live in Greece all year round to benefit from these regimes?

Greek tax residence in principle requires more than 183 days3 of presence per year, with a genuine home in the country.

Residence and citizenship by investment programmes

Data shared with the comparison tool: same amounts, same sources. Compare with other programmes

Μόνιμη άδεια διαμονής επενδυτή (άρθρο 100 ν. 5038/2023)

Residence · Open · Official page

Minimum entry
  • from €250,000 — investment, main applicantListed building (διατηρητέο) to be fully restored before the 1st renewal; a sale before restoration is void; circular 1/2026 (copy hosted by the press).newmoney.gr · Verified on Oct 13, 2026
  • from €250,000 — investment, main applicantNon-residential property (commercial/industrial) converted to residential use, with conversion completed after 5/4/2024 and before the application; all areas, no minimum floor area.migration.gov.gr · Verified on Oct 13, 2026
  • from €400,000 — investment, main applicantOutside high-demand areas; a single property, ≥ 120 m² of main floor area; short-term rental prohibited.migration.gov.gr · Verified on Oct 13, 2026
  • from €800,000 — investment, main applicantAttica, Thessaloniki, Mykonos, Santorini (Thira), islands with more than 3,100 inhabitants; a single property, ≥ 120 m²; short-term rental prohibited.migration.gov.gr · Verified on Oct 13, 2026
Government fees (main applicant)
Not provided
Family
Not provided
Processing time
Not provided
Required stay
Not provided
Permit duration
  • 5 years — permit duration, main applicantPermanent permit, renewable for as long as the investment is maintained.newmoney.gr · Verified on Oct 13, 2026

Banks and accounts

Banks and accounts for this country

See this country on the tax map

Please note

General information, as of the date shown. A draft reform is not a rule in force: check the conditions with the authorities or a professional before deciding. Terms of use and disclaimers

Sources and verification dates

  1. 1.

    Population : 10,400,000

    Verified on Nov 2, 2026

  2. 2.

    Flight from Paris : 3 hours

    Verified on Nov 2, 2026

  3. 3.

    Greece: annual presence above which tax residency is acquired : 183 days

    « An individual is considered Greek tax resident if she/he maintains permanent or main residence or usual abode or center of vital interests in Greece […]. Furthermore, subject to the above provisions, any individual who is present in Greece for a period exceeding 183 days, cumulatively during any twelve (12) month period, is considered to be a Greek tax resident as of her/his first day of arrival in Greece. However, respective provisions are not applicable in case of individuals who are present in Greece only for tourism, medical, medicinal or equivalent personal purposes on condition that their presence does not exceed the 365 days threshold. — Enterprise Greece (agence publique d'investissement, ministère des Affaires étrangères), « Brief Tax Guide Greece 2026 » (Code des impôts sur le revenu, loi 4172/2013, art. 4). »

    enterprisegreece.grVerified on Nov 2, 2026Verified source

  4. 4.

    Greece: rate of the first bracket of the salaries and pensions scale (from 2026) : 9%

    « For tax years 2026 onwards, taxable income from employment and pension is taxed according to the following scale — Income (€) / Tax Rate : 0 – 10.000 : 9% ; 10.001 – 20.000 : 20% ; 20.001 – 30.000 : 26% ; 30.001 – 40.000 : 34% ; 40.000,01 – 60.000 : 39% ; > 60.000 : 44% [taux réduits selon le nombre d'enfants à charge]. — Ministry of Economy and Finance, « Tax Guide – Income Taxation » (Law 4172/2013, Income Tax Code). »

    minfin.gov.grVerified on Nov 2, 2026Verified source

  5. 5.

    Greece: income tax 2026 (art. 15 §1 ΚΦΕ, salaries and pensions), rate of the 6th bracket : 44%

    « Με τις διατάξεις της παρ. 1 του άρθρου 15 του ν. 4172/2013 (Α΄167, Κώδικας Φορολογίας Εισοδήματος - ΚΦΕ), όπως τροποποιήθηκε με την παρ. 1 του άρθρου 3 του ν. 5246/2025 (Α΄198) και σύμφωνα με την παρ. 3 του άρθρου 47 του νόμου αυτού ισχύει για εισοδήματα που αποκτώνται από το φορολογικό έτος 2026, μεταξύ άλλων, ορίζεται ότι: […] Εισόδημα (Μισθοί, συντάξεις, επιχειρηματική δραστηριότητα) σε ευρώ | Φορολογικός Συντελεστής (%) | >60.000 | 44% »

    hellenicparliament.grVerified on Nov 2, 2026Verified source

  6. 6.

    Greece: income tax 2026 (art. 15 §1 ΚΦΕ, salaries and pensions), lower threshold of the 6th bracket : €60,000

    « Με τις διατάξεις της παρ. 1 του άρθρου 15 του ν. 4172/2013 (Α΄167, Κώδικας Φορολογίας Εισοδήματος - ΚΦΕ), όπως τροποποιήθηκε με την παρ. 1 του άρθρου 3 του ν. 5246/2025 (Α΄198) και σύμφωνα με την παρ. 3 του άρθρου 47 του νόμου αυτού ισχύει για εισοδήματα που αποκτώνται από το φορολογικό έτος 2026, μεταξύ άλλων, ορίζεται ότι: […] Εισόδημα (Μισθοί, συντάξεις, επιχειρηματική δραστηριότητα) σε ευρώ | Φορολογικός Συντελεστής (%) | >60.000 | 44% »

    hellenicparliament.grVerified on Nov 2, 2026Verified source

  7. 7.

    Greece: withholding tax on dividends : 5%

    « Dividends are subject to a withholding tax of five percent (5%). […] If the distribution of dividends is subject to withholding tax, the withholding tax exhausts the tax liability only for individuals and for the specific type of income of the taxpayer. »

    minfin.gov.grVerified on Nov 2, 2026Verified source

  8. 8.

    Greece: tax rate on capital gains from disposals : 15%

    « Income from capital transfer gains is taxed at a rate of fifteen percent (15%). »

    minfin.gov.grVerified on Nov 2, 2026Verified source

  9. 9.

    Greece: top rate of inheritance tax in the direct line (category A) : 10%

    « For Category A: Scales (EUR) Scale rate (%) [...] Excessive amount 10 »

    minfin.gov.grVerified on Nov 2, 2026Verified source

  10. 10.

    Greece: tax rate on the profits of legal entities : 22%

    « Profits from business activity acquired by legal persons and legal entities, except for the following cases b) and c), are taxed at a rate of 24%. For profits acquired in tax year 2021 and onwards, the rate is reduced to 22% (by virtue of article 120 of Law 4799/2021). »

    minfin.gov.grVerified on Nov 2, 2026Verified source

  11. 11.

    Greece, regime for foreign retirees: flat rate on foreign-source income : 7%

    « Annual flat tax rate of 7% on total foreign source income. »

    enterprisegreece.grVerified on Nov 2, 2026Verified source

  12. 12.

    Greece, regime for foreign retirees: period of application : 15 years

    « Duration of regime's applicability • Fifteen (15) tax years. »

    enterprisegreece.grVerified on Nov 2, 2026Verified source

  13. 13.

    Greece, regime for high-net-worth individuals: annual flat tax on foreign income : €100,000

    « 1.2 Special tax regimes at a glance — HIGH NET WORTH INDIVIDUAL (HNWI) REGIME : Not a Greek tax resident for the seven (7) out of eight (8) years preceding the transfer to Greece. […] Minimum investment of EUR 500 000 within a period of three (3) years. […] Preferential alternative taxation : A lump sum tax of EUR 100 000 on an annual basis (extinguishing tax liability on global foreign source income). Plus a lump sum tax of EUR 20 000 on an annual basis, in case a relative (spouse, children, parents) utilizes respective provisions. Duration of regime's applicability : Fifteen (15) tax years. — Enterprise Greece, « Brief Tax Guide Greece 2026 » (art. 5A du Code des impôts sur le revenu). »

    enterprisegreece.grVerified on Nov 2, 2026Verified source

  14. 14.

    Greece, regime for high-net-worth individuals: investment required in Greece : €500,000

    « HIGH NET WORTH INDIVIDUAL (HNWI) REGIME : […] Can prove that they or their relatives or a legal entity in which they hold the majority of the shares, invests in real estate or moveable assets or shares of legal entities based in Greece. Minimum investment of EUR 500 000 within a period of three (3) years. — Enterprise Greece, « Brief Tax Guide Greece 2026 » (art. 5A). »

    enterprisegreece.grVerified on Nov 2, 2026Verified source

  15. 15.

    Greece, Article 5Α regime: maximum duration of the flat-rate regime : 15 years

    « για δεκαπέντε (15) φορολογικά έτη, με έναρξη από το έτος υποβολής της αίτησης »

    Ανεξάρτητη Αρχή Δημοσίων Εσόδων (ΑΑΔΕ), « Φορολογικά κίνητρα για νέους φορολογικούς κατοίκους (οδηγός, 12/11/2025) »Verified on Nov 2, 2026Verified source

  16. 16.

    Greece, Article 5Α regime: annual flat tax per attached family member : €20,000

    « ποσό φόρου ίσο με είκοσι χιλιάδες (20.000) ευρώ για κάθε συγγενικό πρόσωπο »

    Ανεξάρτητη Αρχή Δημοσίων Εσόδων (ΑΑΔΕ), « Φορολογικά κίνητρα για νέους φορολογικούς κατοίκους (οδηγός, 12/11/2025) »Verified on Nov 2, 2026Verified source

  17. 17.

    Greece, workers relocating from abroad: share of employment income exempt from tax : 50%

    « Eligible to income tax exemption on 50% of employment income earned in Greece during any tax year. »

    enterprisegreece.grVerified on Nov 2, 2026Verified source

  18. 18.

    Greece, workers relocating from abroad: duration of the partial exemption : 7 years

    « ATTRACTING FOREIGN INDIVIDUALS TO WORK IN GREECE : […] Eligible to income tax exemption on 50% of employment income earned in Greece during any tax year. […] Duration of regime's applicability : Seven (7) tax years. — Enterprise Greece, « Brief Tax Guide Greece 2026 » (art. 5C). »

    enterprisegreece.grVerified on Nov 2, 2026Verified source

  19. 19.

    Greece, Golden Visa: island population above which the higher threshold applies : 3,100

    « όλα τα νησιά με πληθυσμό άνω των 3.100 κατοίκων »

    stegasi.gov.grVerified on Nov 2, 2026Verified source

  20. 20.

    Greece, Golden Visa: former threshold in high-demand areas, before law 5100/2024 : €500,000

    « αυξάνεται το όριο ελάχιστης επένδυσης σε ακίνητα... από 500.000€ σε 800.000€ »

    stegasi.gov.grVerified on Nov 2, 2026Verified source

  21. 21.

    Greece, Golden Visa: real estate investment threshold in Attica, Thessaloniki, Mykonos, Santorini and populous islands : €800,000

    « αυξάνεται το όριο ελάχιστης επένδυσης σε ακίνητα... από 500.000€ σε 800.000€ »

    stegasi.gov.grVerified on Nov 2, 2026Verified source

  22. 22.

    Greece, Golden Visa: former threshold in the rest of the country, before law 5100/2024 : €250,000

    « αύξηση από 250.000€ σε 400.000€ »

    stegasi.gov.grVerified on Nov 2, 2026Verified source

  23. 23.

    Greece, Golden Visa: real estate investment threshold in the rest of the country : €400,000

    « αύξηση από 250.000€ σε 400.000€ »

    stegasi.gov.grVerified on Nov 2, 2026Verified source

  24. 24.

    Greek passport: visa-free destinations : 191

    « Henley Passport Index — classement des passeports par nombre de destinations accessibles sans visa préalable (données IATA), consulté à la date indiquée. Valeur reprise de l’index de l’ancien site (barème à 227 destinations). »

    henleyglobal.comVerified on Nov 2, 2026Verified source