International mobility news

Paraguay

Moving to Paraguay in 2026: territorial taxation, accessible residency and a low cost of living

Paraguay applies territorial taxation (foreign income is not taxed), a 10% tax rate and one of the most accessible permanent residencies in South America. A very low cost of living completes the picture.

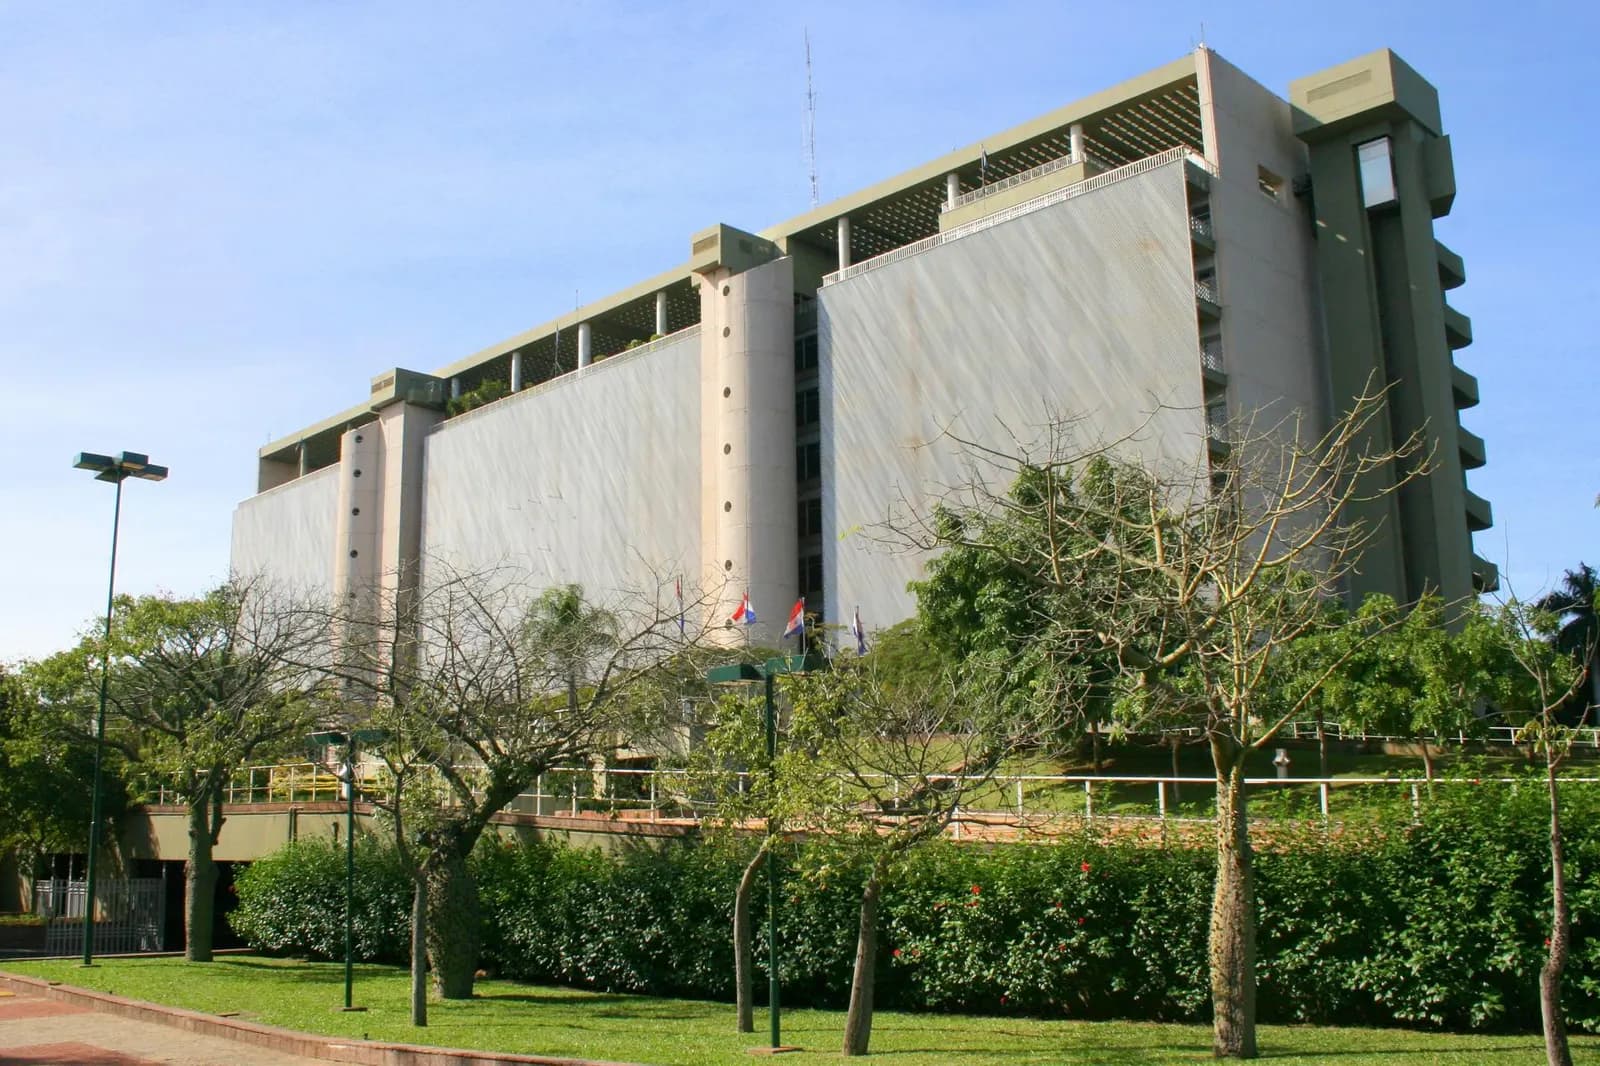
View of Paraguay
Photo: FF MM — Wikimedia Commons (CC BY-SA)
Capital
Asunción
Currency
PYG
Region
Americas

Tax regimes at a glance

Each regime answers the same questions. A zero rate applies only to the income, person and period stated.

Your personal taxation

  • Personal income tax (IRP): territorial taxationGeneral regime

    Who for?
    Individuals resident in Paraguay receiving Paraguayan-source income above the filing threshold.
    Which income?
    Income from personal services (salaries, fees); capital income and gains (IRP-RGC category) taxed separately at a proportional rate.
    Which source?
    Territorial: income derived from activities carried out, assets located or rights used in Paraguay (Article 6 of Law 6380 of 2019); foreign-source income is not taxed.
    Conditions
    Short progressive scale for personal services; tax residence must be established in a way that can be enforced against the authorities; immigration residence is not enough. Bracket thresholds not verified.
    Duration
    Permanent regime.
    Since when?
    Law 6380 of 2019, applicable since 2020 (IRP-RGC since 2021).
    • 8% Paraguay: rate of the first bracket of personal income tax
    • 10% Paraguay: top bracket rate of the IRP on personal services income
    • 0% Paraguay: taxation of income not from Paraguayan sources
    • 120 days

    Official source · dnit.gov.py

  • Investor Pass (investor residency)Special regime

    Who for?
    Foreign investors making an investment in Paraguay.
    Which income?
    No tax advantage of its own: accelerated residency procedure.
    Which source?
    Not applicable.
    Conditions
    Minimum investment depending on the route chosen: productive investment, financial instruments, real estate or tourism; the investor certificate is issued within a short statutory period.
    Duration
    Depends on the residence permit obtained.
    Since when?
    Launched in 2026 (announced in May 2026); conditions to be confirmed against the official text.
    • from $70,000 Paraguay — Investor Pass: productive investment route
    • from $200,000 Paraguay — Investor Pass: financial instruments route
    • from $200,000 Paraguay — Investor Pass: real estate route
    • from $150,000 Paraguay — Investor Pass: tourism route
    • up to 5 days Paraguay — Investor Pass: statutory time limit for issuing the CIE certificate

    Official source · ferrere.com

Your company

  • Corporate income tax (IRE)General regime

    Who for?
    Companies, corporations and individuals carrying on a commercial, industrial or service activity on a regular basis.
    Which income?
    Net income for the financial year.
    Which source?
    Territorial: income from activities carried out in Paraguay; certain foreign-source income linked to investments of Paraguayan capital is covered by the law.
    Conditions
    Single rate; simplified regimes for small businesses (IRE SIMPLE, RESIMPLE) not detailed here.
    Duration
    Permanent regime.
    Since when?
    Law 6380 of 2019, applicable since 2020.
    • 10% Paraguay: business income tax rate

    Official source · dnit.gov.py

  • Tax on dividends and distributed profits (IDU)General regime

    Who for?
    Partners and shareholders receiving dividends or profits from a company subject to the IRE; the distributing entity withholds the tax.
    Which income?
    Distributed dividends, profits and returns.
    Which source?
    Distributions from Paraguayan entities.
    Conditions
    The rate differs depending on whether the recipient is resident or non-resident; it is added to the IRE already paid by the company, the total remaining moderate.
    Duration
    Permanent regime.
    Since when?
    Law 6380 of 2019; DNIT reminder of April 2026.
    • 8% Paraguay: tax rate on dividends distributed to a resident beneficiary
    • 15% Paraguay: rate of the tax on dividends and profits (IDU) for a non-resident beneficiary

    Official source · dnit.gov.py

Compare with other countries:Foreign incomeCompany taxationRegimes for new residents

Key figures

  • Population6,900,000Verified on Nov 2, 2026
  • Flight from Parisabout14 hoursVerified on Nov 2, 2026

Personal taxation

Paraguay applies strict territorial taxation, set out in Article 6 of the tax modernization law: income of Paraguayan source is income derived from activities carried out within the territory of the Republic. Foreign-source income does not form part of the tax base, at a rate of 0%3.

This is the foundation of the country's appeal, and it is written into the law, not into a brochure. For a freelancer or an annuitant whose income comes from abroad, this is a rare architecture in South America, where most states tax residents on their worldwide income.

Personal income tax is progressive and short. Its first bracket is taxed at 8%4, with the higher brackets remaining moderate.

Companies and dividends

Corporate income tax is a single rate of 10%5 on net profit, one of the lowest in the region.

Distributions are taxed separately, through a tax on dividends and distributed profits, at a rate of 8%6 where the recipient is resident and 15%7 where the recipient is not, the tax being withheld by the distributing company.

The whole, 10%5 on profit and 8%6 on distribution for a resident partner, remains well below European levels, and it is this combination, more than the scale applying to individuals, that explains why structures are set up there.

We do not publish the Paraguayan rules on inheritance and gift taxation, nor the exact bracket thresholds of the individual income tax scale: they do not appear in the extracts of the law available to us.

A point of method is worth making for any territorial system, and Paraguay is no exception: it protects income whose source is abroad, not income whose source is local. A freelancer based in Asunción who invoices Paraguayan clients is carrying on an activity developed within the territory, and the resulting income is taxable there. Territorial taxation rewards relocating a residence, not relocating an activity.

The question becomes more complicated where the activity is carried out from Paraguay for foreign clients. The location of the source then depends on the analysis adopted by the tax authority, and that analysis should be secured before the move rather than argued over after an audit.

Residence routes and visas

Paraguay has long been presented as the simplest and cheapest permanent residency on the continent. The scheme has been reformed, and one should reason on the current regime rather than on the accounts of arrivals in previous years.

The main route remains permanent residency granted to people who can show means of subsistence, with a documentary file covering identity, the absence of a criminal record and financial capacity. Specific routes exist for investors and for family reunification.

The amounts and conditions required for Paraguayan permanent residency, as well as those of the investment routes, do not appear in the official sources we were able to consult: we do not quantify them. This point has been amended several times and must be checked with the General Directorate of Migration before any commitment.

One thing should be understood before taking any steps: obtaining Paraguayan residency and obtaining a cédula (identity card) are two distinct stages, the second determining the practical use of the first, whether for opening an account, registrations or contracts.

Finally, permanent residency does not in itself confer tax residence. The latter depends on its own criteria, and Paraguayan territorial taxation takes effect only once that status has been acquired and can be enforced against the authorities.

Real estate

Acquisition by a foreigner is free for urban property. A restriction does exist, however, on land located in border zones, where acquisition by nationals of neighbouring countries is regulated.

The market is dominated by Asunción and Ciudad del Este, the latter drawing its activity from the Brazilian border and cross-border trade. The dynamics there are very different, and a property bought in one cannot be compared with a property bought in the other.

The main point of vigilance is the chain of title. The Paraguayan registry requires careful verification, and using local counsel independent of the seller is not an excessive precaution but an ordinary condition of security.

Agriculture, moreover, accounts for a significant share of foreign investment. This sector has its own constraints, such as title, access to water and labour, and is not analysed in the same way as a residential investment.

We do not publish Paraguayan transfer taxes, property tax or the taxation of rental income: they do not appear in our extracts.

Cost of living

Paraguay is one of the cheapest countries in South America. Services, labour and local food are very affordable relative to a European income.

We do not publish a typical monthly budget: we have not found an official Paraguayan series measuring a basket of expenses comparable to that of an expatriate.

Three factors temper this finding. First, imported goods, whose price includes transport in a country with no coastline. Second, healthcare: private facilities in Asunción handle routine medicine, but serious cases frequently lead to a transfer to Brazil or Argentina. And third, the climate, whose very hot summers make air conditioning a permanent expense.

Being landlocked is the country's structural constraint: air links to Europe require a connection, and supply of specialised goods is slower and more costly than elsewhere in the region.

On the other hand, monetary stability there has been better than in several neighbouring countries, which limits the erosion of a budget calculated in local currency.

Procedures and timelines

  1. Check the conditions currently in force with the General Directorate of Migration, as the regime has been reformed;
  2. gather the civil status and criminal record documents, legalised and translated; this is the longest step and it is prepared in France;
  3. obtain the cédula after residency: it determines the practical use of the status;
  4. open a local bank account, a step that requires the cédula;
  5. deal with the departure from France according to its own criteria: Paraguayan territorial taxation takes effect only after an actual transfer of tax residence.

The last point is the one that decides everything. A French national who obtained Paraguayan residency without moving their household or their centre of economic interests would remain domiciled in France, and local territorial taxation would be of no use to them.

We do not publish processing times: we have no dated, quantified official source for Paraguayan residencies.

Points of vigilance

  • Territorial taxation is written into the law, in Article 6: it is a solid advantage, but it requires actually being a Paraguayan tax resident.
  • The residency regime has been reformed: the amounts and conditions circulating in older guides are no longer valid.
  • Permanent residency, the cédula and tax residence are three distinct stages.
  • Taxation of profits at 10%5 followed by distributions at 8%6 must be read as a whole.
  • The Paraguayan passport brings no mobility gain for a European national.

Finally, Paraguay is a destination where the gap between the advertised simplicity and the administrative reality is significant. The country is welcoming and the tax regime is genuinely favourable, but the procedures call for patience, reliable local advice, and acceptance of an environment where the informal economy plays a larger role than in Europe. This is not an obstacle; it is a parameter to take into account before leaving, not to discover on arrival.

Advantages & disadvantages

Pros

  • The simplest and cheapest permanent residency in the world

  • Territorial taxation: 0%8 on foreign income, 10%9 maximum on local income

  • Minimal cost of living

Cons

  • Landlocked, few direct flights to Europe

  • Limited infrastructure and healthcare

  • Little appeal for a “premium” lifestyle

Frequently asked questions

Is foreign income taxed in Paraguay?

No: the country applies territorial taxation, and only Paraguayan-source income is taxed (at 10%9).

Is residency easy to obtain?

Yes: Paraguay offers one of the most accessible permanent residencies in South America.

What is the cost of living?

Among the lowest in South America.

Residence and citizenship by investment programmes

Data shared with the comparison tool: same amounts, same sources. Compare with other programmes

Investor Pass — foreign investor certificate and permanent residency

Residence · Open · Official page

Minimum entry
  • from $70,000 — investment, main applicantApproved business plan and at least 5 formal jobs created (Ferrere law firm, May 2026).ferrere.com · Verified on Nov 2, 2026
  • from $150,000 — investment, main applicantTourism project with an approved business plan (Ferrere law firm).ferrere.com · Verified on Nov 2, 2026
  • from $200,000 — investment, main applicantAcquisitions for personal or family use excluded; no jobs or business plan required (Ferrere law firm).ferrere.com · Verified on Nov 2, 2026
  • from $200,000 — investment, main applicantCapital kept in Paraguay for at least 2 years with annual reports; no jobs or business plan required (Ferrere law firm).ferrere.com · Verified on Nov 2, 2026
Government fees (main applicant)
Not provided
Family
Not provided
Processing time
  • up to 5 days — processing time, main applicantWorking days from submission of a complete application, unless observations are raised; regulatory time limit for the CIE, not for residency (Ferrere law firm).ferrere.com · Verified on Nov 2, 2026
Required stay
Not provided
Permit duration
Not provided

Banks and accounts

Banks and accounts for this country

See this country on the tax map

Please note

General information, as of the date shown. A draft reform is not a rule in force: check the conditions with the authorities or a professional before deciding. Terms of use and disclaimers

Sources and verification dates

  1. 1.

    Population : 6,900,000

    Verified on Nov 2, 2026

  2. 2.

    Flight from Paris : 14 hours

    Verified on Nov 2, 2026

  3. 3.

    Paraguay: taxation of income not from Paraguayan sources : 0%

    « Artículo 6.º Fuente. Constituirán rentas de fuente paraguaya las que provienen de actividades desarrolladas en la República, de bienes situados o de derechos utilizados económicamente en la misma. […] Artículo 60. Tasa. La tasa aplicable para las rentas y ganancias del capital será del 8% (ocho por ciento). — Ley N.º 6380/2019, art. 6 et 60 : les plus-values de source étrangère échappent à l'impôt ; celles de source paraguayenne sont imposées à 8 %. »

    dnit.gov.pyVerified on Nov 2, 2026Verified source

  4. 4.

    Paraguay: rate of the first bracket of personal income tax : 8%

    « Artículo 69. Tasas. […] Renta Neta Tasa aplicable 1. Hasta ₲ 50.000.000 8% »

    dnit.gov.pyVerified on Nov 2, 2026Verified source

  5. 5.

    Paraguay: business income tax rate : 10%

    « Artículo 21. Tasa. La tasa del IRE será del 10% (diez por ciento), sobre la renta neta. »

    dnit.gov.pyVerified on Nov 2, 2026Verified source

  6. 6.

    Paraguay: tax rate on dividends distributed to a resident beneficiary : 8%

    « Artículo 43. Tasas. La tasa IDU será del: 1. 8% (ocho por ciento) cuando el perceptor de los dividendos, utilidades o rendimientos sea una persona física, jurídica o entidad residente en el país. »

    dnit.gov.pyVerified on Nov 2, 2026Verified source

  7. 7.

    Paraguay: rate of the tax on dividends and profits (IDU) for a non-resident beneficiary : 15%

    « La tasa es del 8% para contribuyentes residentes en el país y del 15% para no residentes. »

    Dirección Nacional de Ingresos Tributarios (Paraguay), « DNIT recuerda vigencia del IDU y detalla cómo cumplir correctamente con este impuesto »Verified on Nov 2, 2026Verified source

  8. 8.

    paraguay.fiscalite.pct.0 : 0%

    « Artículo 1.º Hecho Generador. Créase un Impuesto a la Renta Empresarial (IRE), que gravará todas las rentas, los beneficios o las ganancias de fuente paraguaya […] Artículo 6.º Fuente. Constituirán rentas de fuente paraguaya las que provienen de actividades desarrolladas en la República, de bienes situados o de derechos utilizados económicamente en la misma. — Ley N.º 6380/2019, art. 1 et 6 (principe de la source ; l'IRP suit la même règle, art. 47-48). Les revenus de source étrangère ne sont pas imposés. »

    dnit.gov.pyVerified on Nov 2, 2026Verified source

  9. 9.

    paraguay.divers.pct.10 : 10%

    « Artículo 69. Tasas. El impuesto correspondiente a las rentas derivadas de la prestación de servicios personales se determinará mediante la aplicación de tasas progresivas vinculadas a una escala de rentas netas. […] 3. Igual o mayor a ₲ 150.000.001 10% »

    dnit.gov.pyVerified on Nov 2, 2026Verified source