Romania
Moving to Romania in 2026: low taxes, the EU and cost of living
As an EU member, Romania combines one of the lightest tax burdens in Europe, a dynamic technology sector and a very low cost of living. Settling is unrestricted for EU citizens.
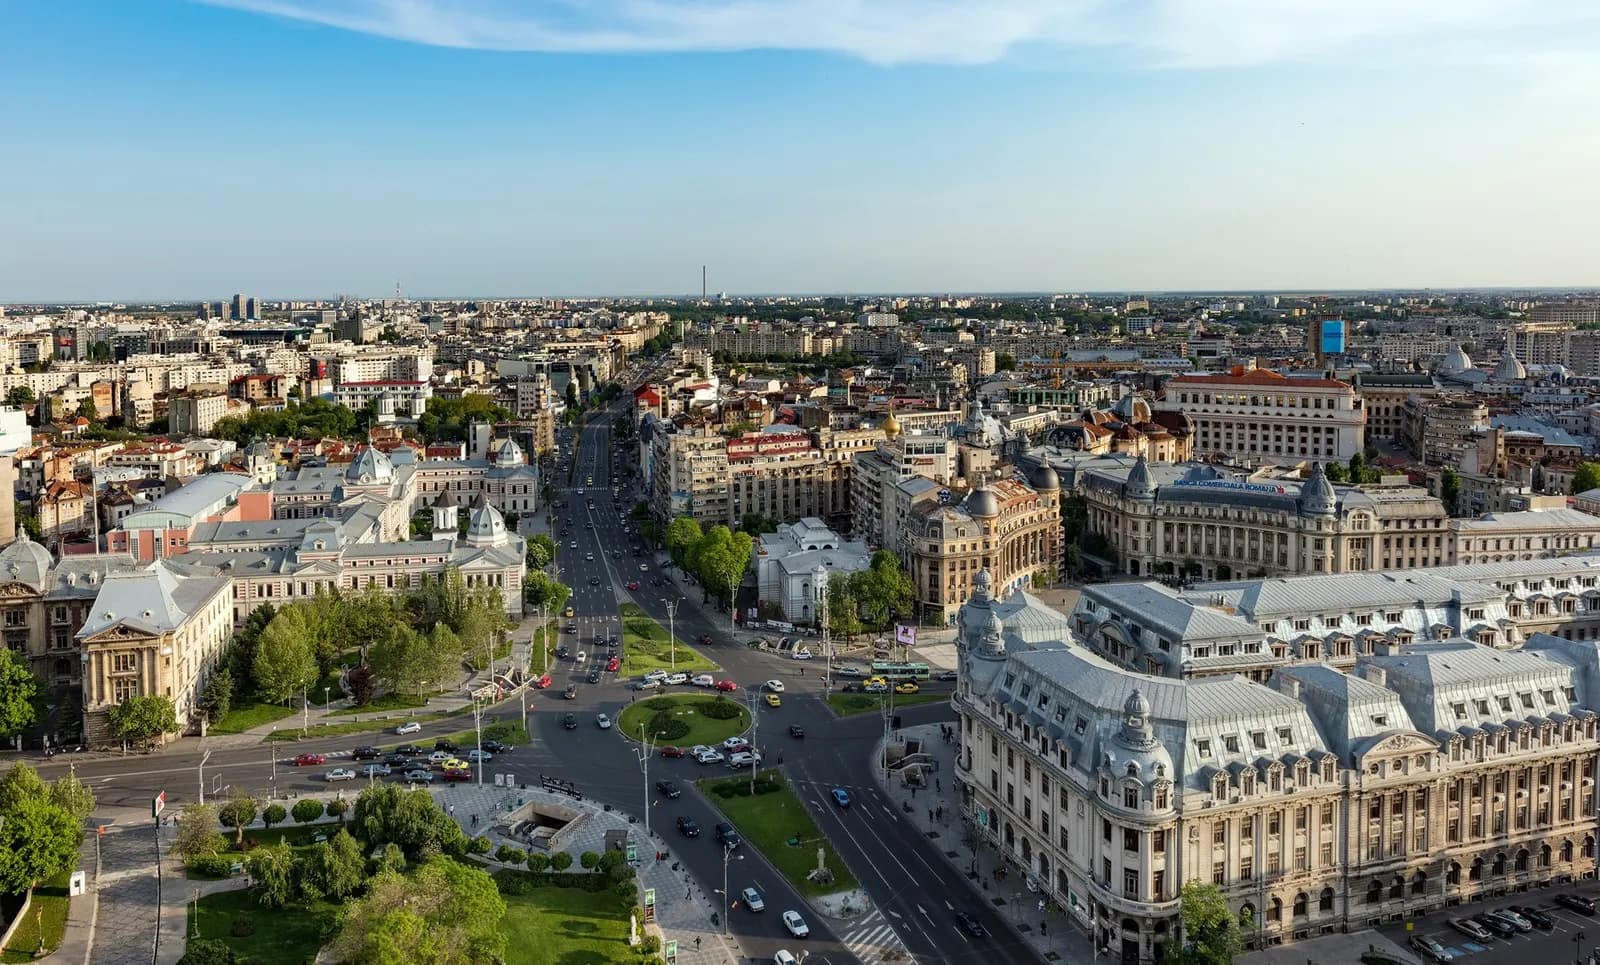
- Capital
- Bucharest
- Currency
- RON
- Region
- Europe
- Memberships
- European Union, Schengen Area
Tax regimes at a glance
Each regime answers the same questions. A zero rate applies only to the income, person and period stated.
Your personal taxation
Income tax: proportional rateGeneral regime
- Who for?
- Individuals who are resident within the meaning of Article 7 of the Tax Code: domicile, centre of vital interests, or a stay exceeding the statutory threshold over a twelve-month period.
- Which income?
- Income in each category (salaries, self-employment, rent, investment income), taxed category by category.
- Which source?
- Residents: worldwide income. Non-residents: Romanian-source income.
- Conditions
- Single rate under Article 64, with no progressive scale; social contributions (pension, health) not verified and decisive for the real cost.
- Duration
- Ordinary regime, with no time limit.
- Since when?
- In force.
- 10% Romania: flat income tax rate (art. 64 of the Tax Code)
- 183 days Romania: length of stay establishing tax residency (art. 7 of the Tax Code)
Dividend taxGeneral regime
- Who for?
- Recipients of dividends paid by a Romanian company, in particular the shareholder-manager of a micro-enterprise.
- Which income?
- Dividends distributed.
- Which source?
- Dividends of Romanian source withheld at source; treatment of foreign dividends not verified.
- Conditions
- Rate increased by Law 141/2025 for dividends distributed from 2026; added to corporate tax and any health contributions.
- Duration
- Ordinary regime.
- Since when?
- Rate applicable to dividends distributed since 1 January 2026; lower rate previously.
- 16% Romania: dividend tax rate (from 1 January 2026, Law 141/2025)
Your company
Corporate income taxGeneral regime
- Who for?
- Romanian companies not under the micro-enterprise regime, and permanent establishments.
- Which income?
- Taxable profit.
- Which source?
- Romanian companies: worldwide profits; permanent establishments: profits attributable to Romania.
- Conditions
- Rate under Article 17 of the Tax Code; minimum turnover tax rules for large companies not verified. VAT was increased on 1 August 2025 by Law 141/2025.
- Duration
- Ordinary regime.
- Since when?
- In force.
- 16% Romania: corporate profit tax rate (art. 17 of the Tax Code)
Micro-enterprise regime (turnover tax)Conditional
- Who for?
- Romanian legal entities whose revenue in the previous financial year does not exceed the ceiling, which have at least one employee, whose capital is not held by the State, and whose majority shareholders place only one company under the regime.
- Which income?
- Revenue (turnover) rather than profit.
- Which source?
- All of the company's revenue.
- Conditions
- Ceiling assessed on the previous financial year's revenue, in lei equivalent; excluded activities (banking, insurance, gambling, hydrocarbons in particular); financial statements filed on time. Since 2026, a single rate: the second rate and the distinction by activity have disappeared. The regime penalises low-margin activities.
- Duration
- As long as the conditions are met, assessed year by year; exit in the year the ceiling is exceeded.
- Since when?
- Rules in force since 1 January 2026 (lowered ceiling and unified rate); verification of 2025 financial year revenue.
- 1% Romania: rate of the micro-enterprise regime on turnover (art. 51)
- up to €100,000 Romania: income ceiling for the micro-enterprise regime (from 1 January 2026)
Compare with other countries:Foreign incomeCompany taxationRegimes for new residents
Key figures
- Population19,000,000Verified on Nov 2, 2026
- Flight from Parisabout3 hoursVerified on Nov 2, 2026
Taxation of individuals
The Romanian Tax Code, in Article 7, defines a resident as an individual who has their domicile in Romania, has the centre of their vital interests there, or stays there for at least 183 days3 during any twelve-month period ending in the calendar year concerned.
Income tax is proportional. Article 64 of the Tax Code sets the rate at 10%4, applied to the taxable income of each category. There is no progressive scale: the same rate applies to the first leu earned and the last.
It is one of the lowest income tax rates in the European Union, and it is the sole reason Romania appears in expatriation comparisons. The appeal is not a special regime reserved for newcomers, as in Portugal or Italy, but the ordinary law applied to everyone.
This difference in nature is decisive and rarely understood. A special regime is limited in time, conditional on recent arrival, and can be closed to new entrants overnight — Portugal has shown as much. An ordinary-law rate does not expire: it can only change through a reform affecting the whole population, which makes any change politically costly.
Companies
Corporate income tax is set by Article 17 of the Tax Code at 16%5 of taxable profit.
A special regime, known as the micro-enterprise regime, applies below the turnover thresholds defined in Article 47. It replaces tax on profit with a levy based on revenue, at a single rate of 1%6 since 1 January 2026: the second rate and the distinction by activity have disappeared.
This regime has built Romania's reputation among digital freelancers. Its logic must nonetheless be understood: the levy applies to turnover, not to results. A low-margin activity is therefore penalised, whereas a consulting activity with no costs benefits greatly.
Since 2026, the regime's revenue ceiling has been set at the lei equivalent of up to €100,0007, assessed on the previous financial year's revenue. The company must also employ at least one employee, and certain activities are excluded — banking, insurance, gambling and hydrocarbons in particular. These rules have been amended several times in recent years: they must be checked at the date of the project with the national tax administration agency.
Dividends have been taxed since 1 January 2026 at a rate of 16%8, increased by Law 141/2025 and withheld at source by the distributing company: the increase raises the cost of extracting profits from a micro-enterprise.
We do not publish Romanian social contribution rates: they do not appear in the extracts available to us, even though they weigh heavily on the real return of the micro-enterprise regime.
This last gap is important to flag. Comparing the Romanian rate of 10%4 with the French scale without including contributions and dividend taxation leads to a false conclusion. The figure in isolation is worthless.
Residence routes and visas
Romania is a member of the European Union. A French national enjoys free movement there: no visa is required, and the right of residence derives directly from the treaty.
Beyond three months, the formality consists of registration with the General Inspectorate for Immigration, which issues a registration certificate. This is not an authorisation but a declaration: the right exists before the procedure.
The substantive condition is that of European law: having sufficient resources and health cover, or carrying on an activity. After five years of continuous residence, the right of permanent residence is acquired.
Romania has also joined the Schengen area, first for air and sea borders, then for land borders. This integration ends the checks that complicated road journeys to Western Europe, a practical point for anyone who keeps ties in France.
For a self-employed person, the step that really shapes the process is therefore not residence but registration: setting up a company or registering as an authorised individual, obtaining a tax number, opening a business bank account. This is where the delay and the difficulty lie.
We do not publish registration timeframes: we have no dated, quantified official Romanian source.
Real estate
A national of the European Union may freely acquire buildings in Romania. The historical restrictions on agricultural and forest land have been gradually lifted for Europeans, subject to conditions of use.
The market is dominated by Bucharest, followed by Cluj-Napoca, Timisoara and Brasov. Cluj has seen a marked increase, driven by its technology sector and its university, and its prices can no longer be compared with the national average.
Two technical points of caution stand out. The first is the restitution of properties nationalised under the communist regime, the source of a long-standing dispute that has not entirely disappeared: the chain of ownership must be traced back. The second is the construction quality of large housing estates built before 1990, some of which present a documented seismic risk — Bucharest lies in an active seismic zone and has an official classification of at-risk buildings.
This second point is specific and serious. A building classified in a high seismic risk category is identified by a marker placed on the facade; buying such a property exposes the buyer to heavy reinforcement works and a difficult resale. Checking the classification comes before any offer.
We do not publish Romanian transfer duties, property tax, or the tax regime for rental income: they do not appear in our extracts.
Cost of living
Romania is among the least expensive countries in the European Union, and the gap with France is real for housing, services and labour. It has nonetheless narrowed in the large cities, where technology-sector salaries have pushed prices up.
We do not publish a typical monthly budget: we have not found an official Romanian series measuring a basket of expenses comparable to that of an expatriate.
The currency is the leu, not the euro. Income received in euros therefore benefits from an exchange-rate differential, but is also exposed to its movements; adopting the euro is a stated objective with no firm deadline.
Value added tax was also increased on 1 August 2025 by Law 141/2025: its standard rate is now 21%9, an increase to factor into any consumption budget.
Three items deserve attention. Healthcare, where the public system is underfunded and pushes residents towards a rapidly growing private sector. International schooling, concentrated in Bucharest and costly. And energy, where prices have fluctuated sharply.
On the other hand, Romanian digital connectivity is excellent, and it is a constant argument among remote workers based in the country. Flights to France are frequent and inexpensive from Bucharest, Cluj and Timisoara.
Procedures and timeframes
- Enter and settle without any visa formality, as free movement applies as of right;
- beyond three months, apply for the registration certificate from the General Inspectorate for Immigration;
- decide on the form of activity — a company under the micro-enterprise regime or under ordinary law — taking into account contributions and dividend taxation, and not just the headline rate;
- check the turnover thresholds in force, which have changed several times;
- deal with the departure from France according to its own criteria and the France–Romania tax treaty.
The third point is where unpleasant surprises arise. A structure calibrated on the 1%6 rate loses most of its appeal once the manager's remuneration and the distribution of profits are taken into account. The calculation must be made on net disposable income, not on the company's tax.
Points of caution
- The 10%4 rate is ordinary law, not a temporary regime: this is a difference in nature from the Portuguese or Italian schemes.
- The micro-enterprise regime taxes turnover, not margin: it penalises low-margin activities.
- Its thresholds have been changed several times recently: the rule must be checked at the date of the project.
- Bucharest's seismic risk is the subject of an official classification of buildings: it should be checked before any purchase.
- Free movement exempts from a visa but not from registration beyond three months.
Finally, Romania suffers from an image that no longer matches its economic reality, and this gap is precisely what makes it interesting. The country combines European Union membership, free movement, the Schengen area, first-class digital infrastructure and one of the lightest personal tax regimes in the Union. What one gives up lies elsewhere: a slow administration, a failing public healthcare system, and tax legislation so unstable that the rules have to be rechecked every year rather than taken for granted.
Advantages & disadvantages
Pros
10%10 flat tax, very low cost of living
Francophile country, French lycée in Bucharest
Some of the fastest internet in the world
Cons
Micro-enterprise regime significantly tightened in recent years
Weak public hospitals
Tax instability (budget deficit → regular increases)
Frequently asked questions
What is the tax system like in Romania?
Romania applies a reduced-rate income tax and an advantageous micro-enterprise regime for small companies, among the lightest in the EU.
Can a French citizen settle there easily?
Yes: as an EU citizen, they simply register locally.
Is the cost of living really low?
Yes: Romania is among the cheapest countries in the EU, with very fast internet.
Banks and accounts
See this country on the tax map
Please note
Sources and verification dates
- 1.
Population : 19,000,000
Verified on Nov 2, 2026
- 2.
Flight from Paris : 3 hours
Verified on Nov 2, 2026
- 3.
Romania: length of stay establishing tax residency (art. 7 of the Tax Code) : 183 days
« c) este prezentă în România pentru o perioadă sau mai multe perioade care depășesc în total 183 de zile, pe parcursul oricărui interval de 12 luni consecutive, care se încheie în anul calendaristic vizat »
static.anaf.roVerified on Nov 2, 2026Verified source
- 4.
Romania: flat income tax rate (art. 64 of the Tax Code) : 10%
« ART. 64 - Cotele de impozitare (1) Cota de impozit este de 10% și se aplică asupra venitului impozabil corespunzător fiecărei surse din fiecare categorie pentru determinarea impozitului pe veniturile din: a) activități independente; a1) drepturi de proprietate intelectuală; b) salarii și asimilate salariilor; c) cedarea folosinței bunurilor; d) investiții; e) pensii; f) activități agricole, silvicultură și piscicultură; g) premii; h) alte surse. »
static.anaf.roVerified on Nov 2, 2026Verified source
- 5.
Romania: corporate profit tax rate (art. 17 of the Tax Code) : 16%
« ART. 17 - Cota de impozitare Cota de impozit pe profit care se aplică asupra profitului impozabil este de 16%. »
static.anaf.roVerified on Nov 2, 2026Verified source
- 6.
Romania: rate of the micro-enterprise regime on turnover (art. 51) : 1%
« ART. 51 - Cotele de impozitare — (1) Cota de impozit pe veniturile microîntreprinderilor este de 1%. ; ART. 47 - (1) […] o microîntreprindere este o persoană juridică română care îndeplinește cumulativ următoarele condiții, la data de 31 decembrie a anului fiscal precedent: […] c) a realizat venituri care nu au depăşit echivalentul în lei a 100.000 euro — Legea nr. 227/2015 privind Codul fiscal, art. 51 al. (1) et art. 47 al. (1) c) (texte consolidé ANAF, dernière mise à jour OUG nr. 38/2026). »
static.anaf.roVerified on Nov 2, 2026Verified source
- 7.
Romania: income ceiling for the micro-enterprise regime (from 1 January 2026) : €100,000
« Limita veniturilor realizate, reprezentând echivalentul în lei a 100.000 euro începând cu 1 ianuarie 2026, se verifică pe baza veniturilor realizate de către persoana juridică română la data de 31 decembrie 2025. »
ANAF – DGRFP Galați / AJFP Buzău, « Regimul fiscal al impozitului pe veniturile microîntreprinderilor (16 juin 2026) »Verified on Nov 2, 2026Verified source
- 8.
Romania: dividend tax rate (from 1 January 2026, Law 141/2025) : 16%
« Începând cu 01.01.2026, se va aplica o cotă de impozitare de 16%. »
ANAF – DGRFP Galați / AJFP Vrancea, « Modificări referitoare la impozitul pe dividende »Verified on Nov 2, 2026Verified source
- 9.
Romania: standard VAT rate (art. 291 of the Fiscal Code, since 1 August 2025) : 21%
« iar nivelul acesteia este 21%. »
Parlamentul României (publiée par l’ANAF), « Legea nr. 141/2025 privind unele măsuri fiscal-bugetare (Monitorul Oficial nr. 699 din 25 iulie 2025) »Verified on Nov 2, 2026Verified source
- 10.
roumanie.cout-vie.pct.10 : 10%
Verified on Nov 2, 2026